An overview of the best vested benefits accounts in 2026
| Criteria | Finpension | Viac | Frankly | Descartes |
|---|---|---|---|---|
![]() | ![]() | ![]() | ![]() |
|
| 💰 Account interest rate | 0.00% | 0.05% | 0.01% | No account |
| 💼 Custody account fees | 0.49% flat rate | 0,0-0,43% | 0,43% | 0.2–0.41 TP3T plus product costs |
| Opening fee | Free of charge | Free of charge | Free of charge | Free of charge |
| 🏛️ Foundation Location | Schwyz (tax advantageous) | Basel | Zurich | Schwyz (tax advantageous) |
| ⭐ Key strength | Up to 100% shares & 2 trusts | Best integration | Best app | Equilibrium approach |
| 🔍 Special feature | Flexible investment strategies (20 to 100% shares) | Seamless integration with pillar 3a | User-friendly app | Depot solution only |
| 🔗 To the provider | Read review | Read review | Read review | Read review |
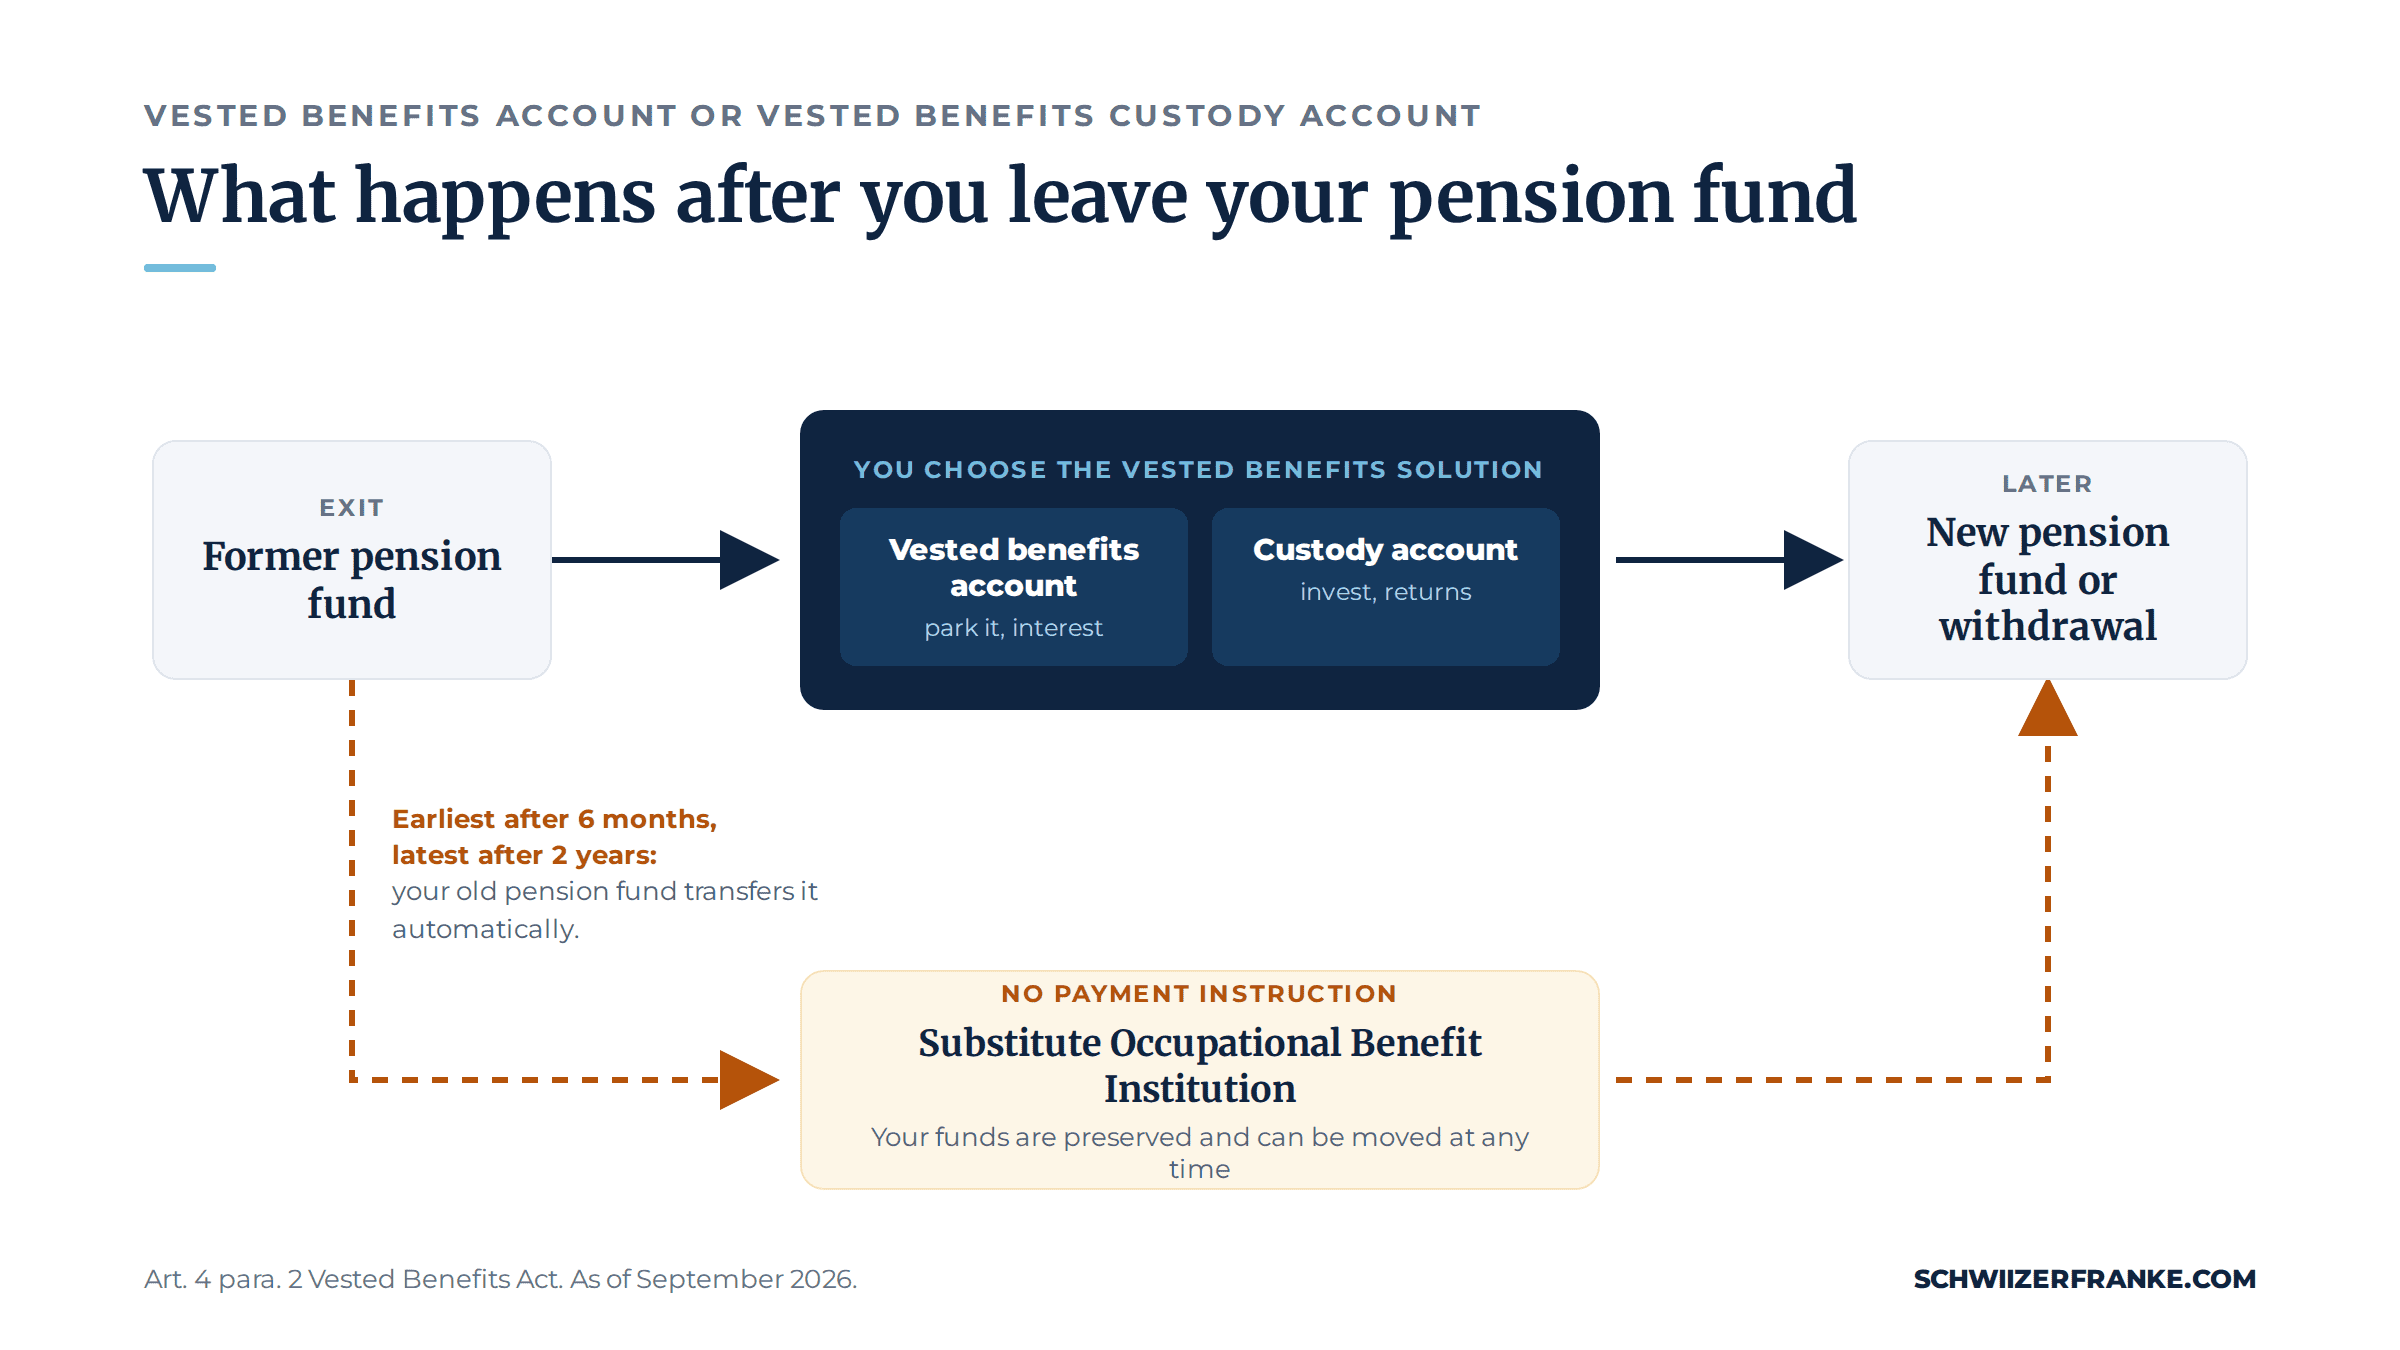
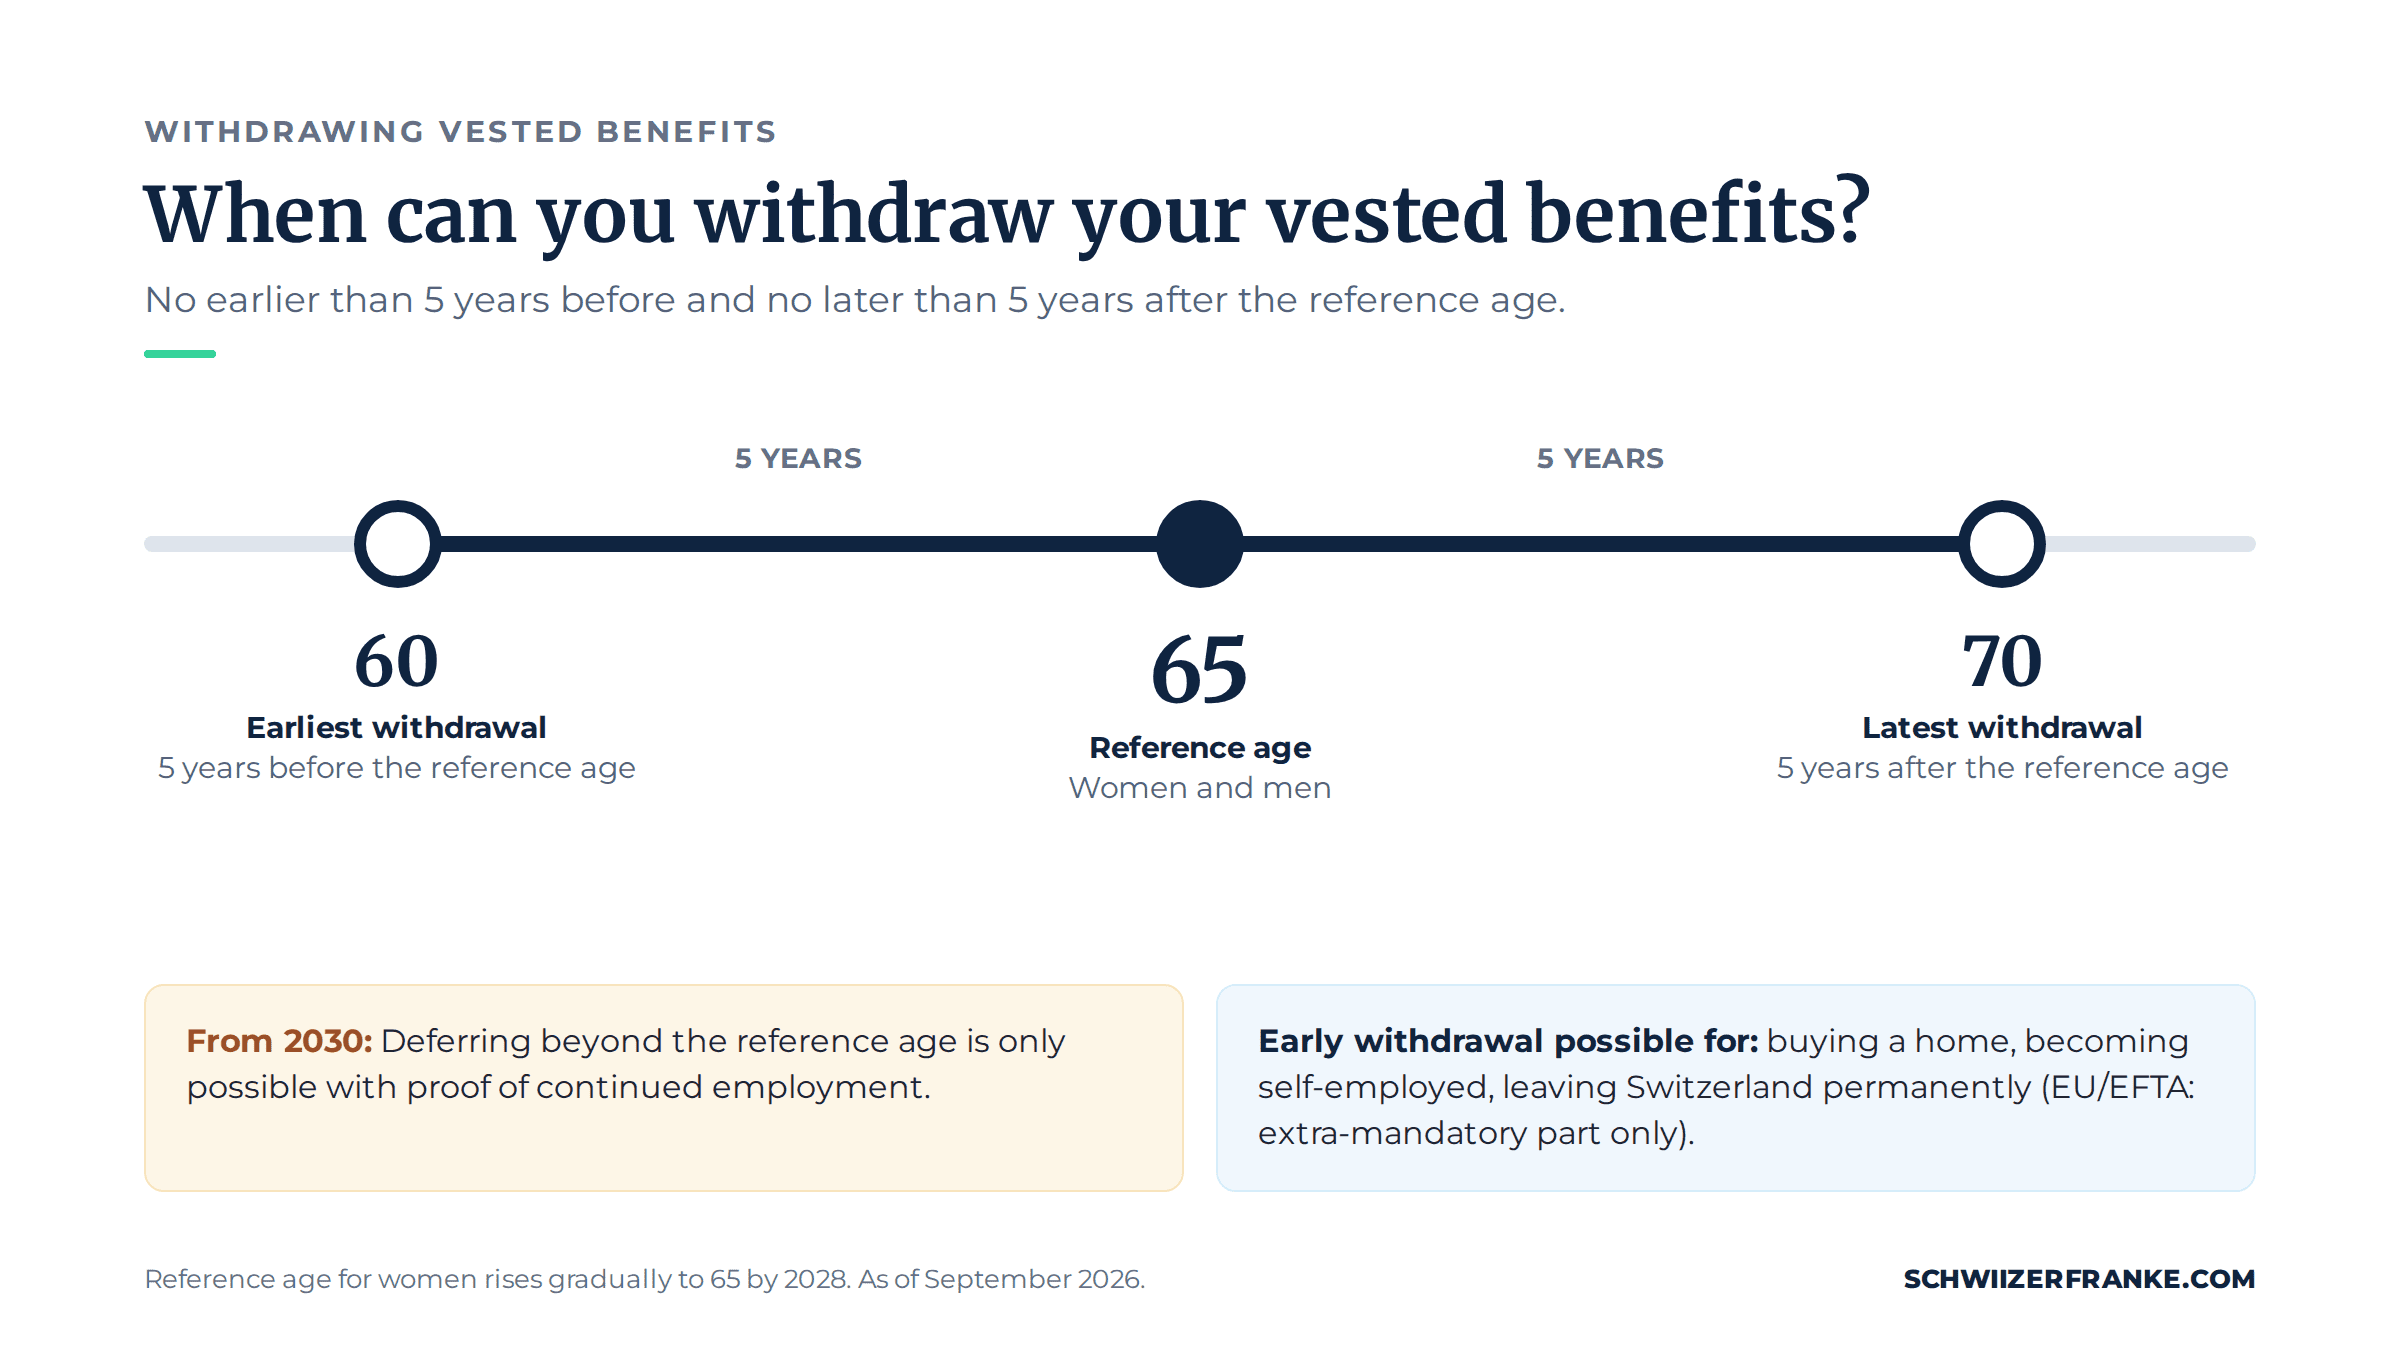
If you take a break between two jobs, you must transfer your pension fund assets to a vested benefits account. You can choose which one you want. When you leave your pension fund, you may also split your pension savings in the second pillar between up to two vested benefits accounts. This is particularly useful if you have more than CHF 100,000 in your pension savings and are unsure when the new pension fund will take over your capital.
To help you find the provider that suits you best, we have put together a vested benefits account comparison. Here you will find the best providers, as well as a comparison of accounts and custody accounts.
💡 Tip for balances over CHF 100,000
| Vested benefits account | Up to CHF 100,000 per person is protected in the event of insolvency (2nd class of claims); no deposit guarantee |
| Vested benefits deposit | ✅ Securities held in a custody account, such as shares and fund units, are excluded from the bankruptcy estate in the event of bankruptcy, regardless of their value |
| Suitable for | A balance of more than CHF 100,000 in an account |
💡 Schwiizerfranke assessment: If your vested benefits balance exceeds CHF 100,000 in a single account, it may be worth splitting it between two providers. This spreads the risk and gives you greater flexibility when it comes to future withdrawals or transfers. Please note: splitting your balance is only possible when you leave the pension fund; an existing vested benefits balance cannot be split retrospectively.