



The emergency fund is a form of saving for emergencies and unplanned special expenses. Again and again you have been asked: How much money should you have saved by 30?
There is no blanket answer to this question. What can be answered is what the median does:
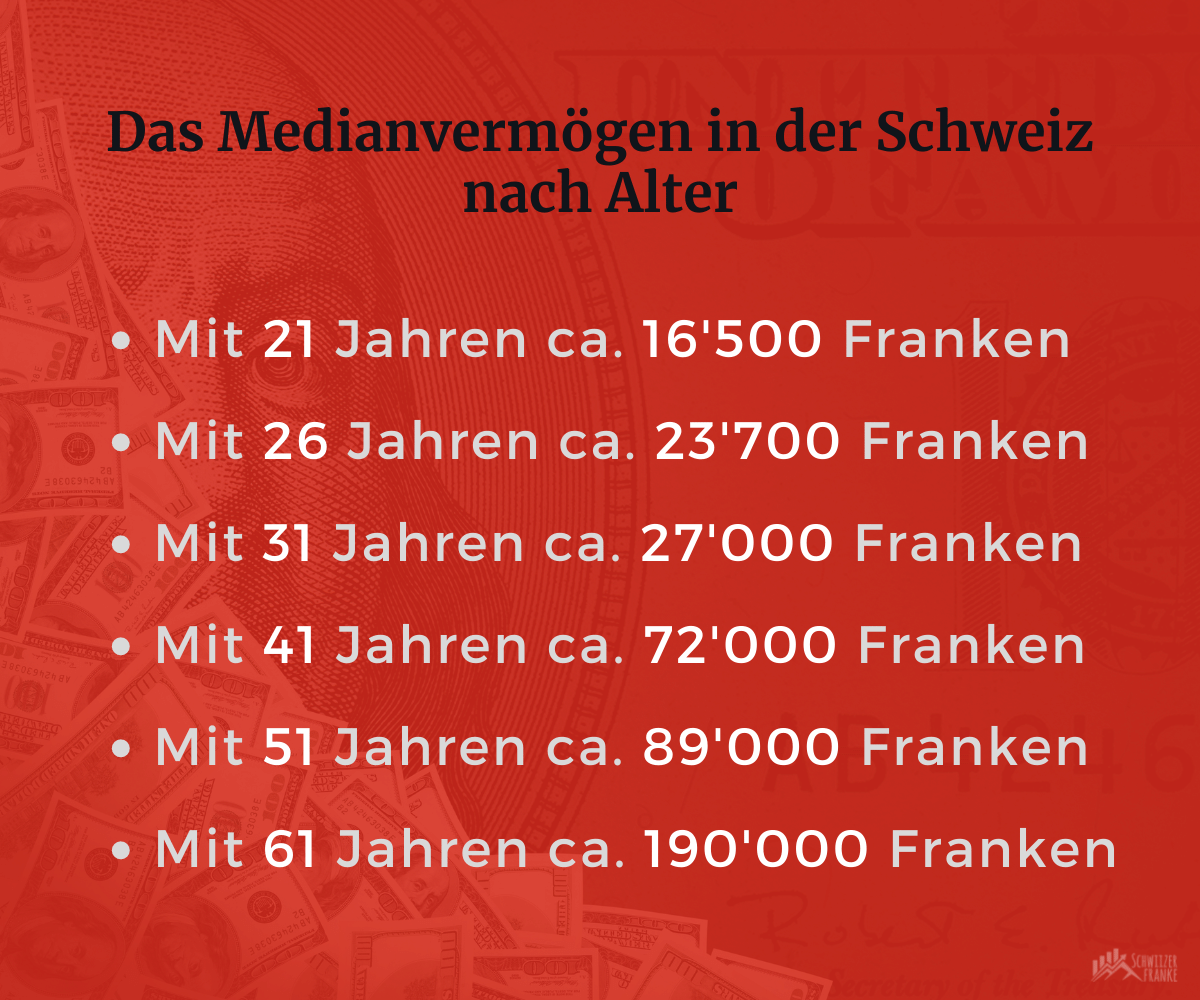
Swiss citizens have a median wealth of around CHF 227,000 across all age groups. This also includes money from pension plans, such as the pension fund. How much money one should have saved by the time one is 30 depends entirely on one's Personal financial goals and possibilities.
Want to buy a home? Just save something to supplement your pension or for specific life goals? Then write down your goal and get going with our Savings tips and Investment ideas to the implementation.
Don't be put off by generic numbers. After all, many 30-year-olds have only been in the workforce for a short time. An important advantage for young people is the long investment period. The Pillar 3a, you should therefore start as early as possible. to take advantage of this.
Free Pension-Guide
Planning for the future with peace of mind
12 pages with a self-assessment test. Find out where you’re missing out when it comes to 3a, your pension fund and your benefits.
The guide will be sent to you as a PDF via email. You will then receive the Wealth Letter every Wednesday. You can unsubscribe at any time.
Please take a moment to confirm your address
We’ve just sent you an email. Just click on the link in it, and your guide will appear.
Can’t find it? Have a look in your spam folder. Sender: «Eric von Schwiizerfranke».
Hello Eric
Thanks for the article! I’ve got a question about emergency savings for married couples: how do you handle this – does each of you have your own emergency savings, or do you have a joint savings account for this purpose? (I’m referring to a savings account solely for a financial buffer, not the joint account for monthly bills.)
What concerns me here is the issue of death: many banks freeze joint accounts until the estate has been settled. This means the surviving partner would have no access to the funds precisely when they need the reserve most urgently. However, if each person sets aside six months’ worth of living expenses for themselves, a great deal of money ends up sitting idle without earning any interest.
How do you view this risk, and what solution would you recommend to couples? Are there any banks where the surviving partner can continue to access the joint account?
Greetings
Marco
Hello Marco
Yes, that is a real risk, which is why I wouldn’t leave it to chance. Fortunately, there are plenty of options these days Accounts with no ongoing costs. Therefore, in addition to a Joint account Always hold accounts in your own name and keep your savings in them.
Hello Eric
What is your opinion on parking part of the nest egg (approx. 50-70 %) with Monefit? One disadvantage is certainly the currency (Euro). However, the 7.5 % return with daily partial payout compensates for this. The withdrawal conditions with €1,000 immediately available and the residual payout within 10 days also seem quite attractive.
Hello David,
Monefit is not a traditional Swiss banking solution, but a EUR-based investment/loan platform with a significantly higher risk than a normal savings account. In addition to the currency risk (EUR/CHF), you also bear provider and liquidity risks - there is a reason for the high 7.5%.
For the Swiss in particular, this is often unattractive due to the strong franc. And when it comes to emergency savings, I would personally prioritise maximum security, rapid availability and a focus on CHF. So for me it's a clear no.
Hey Eric,
Thanks for the great post, as always! A nest egg account such as a savings account or a pot in Zak would be a simple solution but.... so inflation eats our savings! In July 2022 inflation in CH was 3.4%. This is purchasing power that we automatically lose when we open an account in cash.
In EUR I know the nice option of Nexo, there you can also load euros, they are liquid assets, and the positive interest is as high as 8%. Great. Unfortunately they do not allow CHF (yet).
With about research I found this stock/token: realunit
Do you/anyone know more about this? As far as I understand they invest mainly in gold. The ERC20 token would be interesting.
Other ideas to protect the nest egg from inflation are more than welcome 😉
Watch out Luca!
A nest egg is there for emergencies. If you put your nest egg into high-(!) risk investments, the money can be lost in extreme cases.
Your nest egg should be safe and always available in liquid form. For example, in a normal bank account.
Nexo is a crypto platform and has no place here under the topic of nest eggs! Please don't be fooled by 8%'s supposedly secure "interest rates". There is no return without risk and a total loss cannot be ruled out with a crypto investment.
I hope you and all who read along here understand that.
Therefore, always keep your nest egg safely in an account. Of course there is inflation, but this must not tempt you to make risky investments with your nest egg. Furthermore, there are already (and surely soon with more) banks that pay out interest on your account balance in CHF again.
Yuh is a first of them.
Dear greetings
Eric
Hello Eric
Thank you for your reply and suggestions!
So as long as I understand there is no other way than to keep the nest egg in a bank account in cash and... unfortunately suffer from inflation 🙁
Is it really so?
But I understand what you're saying about Nexo. What about Realunit? They don't look like risky investments...
Hello Luca
Real Unit looks to me, after a quick glance, like a classic robo advisor. You suggest an equity allocation of around 40% - using a rough rule of thumb, I wouldn't invest any money here that I would need again in the next 4 years. So definitely not an option for a nest egg either.
Inflation protection can be achieved via investments be made.
However, I would advise you not to invest money that should always be available at short notice for emergencies (like the nest egg).
Which should also go into calculating the nest egg ( I call it my Murphy account ):
- Health insurance deductible
- Are you dependent on a car but your clunker could give up the ghost at any time?
- How is your general health? Do you have to reckon with large dental bills, for example?
- What about insurance? If you don't have contents insurance, could you quickly refurnish your home after water damage?
- personal risks of a different kind...
In my experience, Mr. Murphy especially likes to visit people who are not prepared for him. Or could it be that those who are prepared do not see his visit as catastrophic but only as a nuisance???
great, thanks for your contribution Alain!