



Our Yuh App Review Summarized
With the Yuh app, you can conveniently and with a single provider manage your Savings and Investment account receive, in the Pillar 3a provide for and even Payments make. Since the integrated pillar 3a was added to the 2023 pension plan, banking, investments and pension provision are offered in full at Yuh.
Regular updates and new features (such as Savings plans or Yuh Pillar 3a) are launched and the app is continuously optimised. Those who had their first Yuh experience at launch now benefit from significantly more functions within the app.
The Yuh fees are flat or at least very simple and straightforward. The transparency of the costs, as well as the design, appeal specifically to young customers.
The conclusion of our short version:
Yuh.com makes it easy to get started with investments in shares, ETFs or cryptocurrencies. You can set up savings goals quickly, and the banking services on offer are attractive.
Thanks to the new fee structure introduced in July 2026, Yuh is no longer just an attractive option for small amounts. For purchase amounts of CHF 10,000 or more, the trading fee drops to 0.35%; for amounts over CHF 20,000, it drops to 0.25%. There is therefore no single portfolio size at which switching to Swissquote becomes worthwhile. However, anyone looking for a wider range of products, limit orders or more trading features is still better off with Swissquote or Saxo.
Nevertheless, the app can be a supplement thanks to Yuh ETF savings plans or quick access to cryptocurrencies. Our Yuh review is therefore consistently positive.
All details and explanations following!
Hi Eric
It’s been a while since the last comment on this post. 😊 I’ve been using Yuh as my main account for a while now and I’m really happy with it; I’ve signed up for Neon for my holidays and I’m really well covered. As for limit orders, they’ve been available on Yuh for a while now. Perhaps you’d like to add that.
Thank you, Sabine – the limit orders have been updated 🙂
Hello, everyone,
For several weeks now, you can only register if you are resident in Liechtenstein, Austria or Switzerland.
Do you have any further information on when this will be possible again?
The support team was unable to provide me with any details over the phone.
Where can I get this free tax statement? I can't generate it without incurring costs (CHF 25).
Kind regards
Anré
Yes, this new Yuh eTax tax statement unfortunately still costs CHF 25 at the moment, but hopefully it will soon be free of charge. The eTax statement (is basically a PDF that you just have to upload with your tax return and everything is automatically recorded) is worthwhile if you have made a VERY large number of trades etc. Otherwise you can do without it if necessary.
Hello Eric
I'm following your tip with the Core-Sattelite strategy. Core is in ETFs with True Wealth, and I have just opened a Yuh account for Sattelites. The interface is clearly laid out.
But I was surprised that you can only buy a small selection of shares. Especially when you study the various financial blogs and websites, it would be nice to be able to buy less well-known CH shares.
Yuh has its own investment portfolios, but they cost over 1% per year. True Wealth seems to me to be more favourable for investing in ETFs.
I also think it's a shame that you can't set stop limits when buying shares. I would like to see automation so that I can automatically buy a stock when it falls below a limit. So I would say that Yuh is less suitable for active trading. But for me as a beginner, it's probably a case of "back and forth empties your pockets" anyway.
Hello Klaus,
Thanks for your feedback! Absolutely, "back and forth empties the pockets", that's why I stick to passive investing with ETFs.
Yuh offers quite a good selection here. Ultimately, however, Yuh is a platform for beginners and belongs to Swissquote and Postfinance. Swissquote will therefore always remain the more "professional" platform with more features and more products etc.
Hello, I have a pillar 3a account with YUH with the Feurig strategy and I would be interested to know how quickly a change of strategy is implemented for pillar 3a. I have only found the information that the change takes place on Thursday. Does this mean that if the stock markets crash, you have to wait until Thursday and then switch to the daily prices of the following Thursday?
In the 3a, such active trading should be avoided - after all, your investment horizon is usually very long.
A long-term strategy should take centre stage.
All in all, a good bank for trading with a user-friendly app.
I've been with Swissquote for 10 years - but as a normal investor, Yuh's offering is sufficient for me, and the essential functions are also available.
But you also have many advantages.
+ Free credit card with multiple currencies
+ No custody account fees
+ Sufficient investment offer
+ Competitive interest rates on cash
+ Clear app without a lot of bells and whistles
Disadvantages
- High exchange fees (0.95%)
App certainly still has room for improvement (performance display missing, for example)
With the code at the opening you will receive free cryptos (Swisscoins)
Hi Eric, thanks for your interesting blog. I already have NEON and am very happy with it. Now I've also opened a Yuh account and wanted to enter the code YUHFRANKE. The app simply skipped it. I couldn't enter the code anywhere and the support chat insists that you can only use the code during the opening process. Do you have a tip for this or are we both now looking down the tube?
Hello Pete,
Thank you for your positive feedback on the blog! 🙂
It's a pity that it didn't work with Yuh when you opened it. I can ask if there's anything I can do to get it credited anyway.
Kind regards,
Eric
Hello everybody
It says that if you have a growing or larger portfolio, it is better to switch directly to Swissquot, for example. my question now is how do you define large? What amount are we talking about here? 10,000 or 100,000? You also say that it is better to buy in larger amounts, but not so often, from 500 and more because of the fees, which I find a lot as an inexperienced person in this area. Are there any things to bear in mind when investing so much money where?
Hello Maurice
There is definitely a lot to consider. It is therefore essential that you "invest" some time in your financial education before you invest large sums of money. Here you will find a first guide, or feel free to come to the next FinanzFahrplan (in german) Course.
I would be interested to know which banking apps can be used on two or more smartphones at the same time.
I have installed Yuh on Android and iOS and use it.
What I would still like to see with Yuh is an analysis tool like Wise, for example. This would allow you to clearly see what you've spent your money on. Otherwise I am extremely satisfied with Yuh!
I have been using yuh for 2 months and also have the yuh twint app.
It works perfectly
So nothing with us app 😊
Hello Eric
I can only agree with you, so far Yuh is running really well! Thank you for your assessment.
My question:
Where can I find the new 3a at yuh?
Hi Michaeal
You can find the new Yuh 3a solution directly in the Yuh app. If you don't see it: Update your app in the Appstore, then you should see the Yuh Pillar 3a 🙂
I thought I had the latest version 🤷🏽♂️
Thanks for the tip, it's finally here 😊
I have the same question. I can't find this option even though I have the latest app version. Under which point should this be displayed? Also, when I opened the account with your code, I "only" received 250 coins - this is just for information.
did you enter the code from above?
There should be a button for "Save" at the top left (like on the right for graphics). The button only appears if you are under 65 ;-). It was only there for me for a short time and is no longer there now that I'm over 65.
What about investments over a longer period, e.g. 10 years?
Should Yuh no longer exist in this form, what will happen to the investments?
Normal Deposits Fuse?
Do I own cryptos shares etc. effectively or is it like Revolut and I have no possibility to push the cryptos e.g. also on a hardware wallet....
Hello Stef
this has nothing to do with yuh, but I'm happy to clarify briefly:
Securities (shares, ETFs, etc.) never become part of the insolvency estate, they always belong to you. So you have nothing to fear here.
Account deposits (cash) are subject to deposit protection.Yuh has deposit protection up to CHF 100,000.
Good day,
I have a question about the sale of shares. Are there any additional fees, i.e. a brokerage fee? And how high would this be?
Thanks for the info and have a nice day.
Hello Yannick, order fees are also due when selling. You can see the fees incurred clearly before you execute the order.
Hi, Eric,
Thanks for the quick reply, how much would these be approximately? Also 0.5%?
Kind regards
Maybe you can still use Swissqoins if you used the credit code above?
It's best to check in the app: Call up the security, select Sale and check the charges there 🙂
Use Twint with Yuh. To do this, download the UBS Twint app, register and enter the IBAN of your Yuh Mastercard.
Unfortunately, this is not possible!
TheYuh Debit Mastercard does not work in the UBS Twint app because no debit cards are accepted.
Greetings Ernst
Hello Ernst
Please try again. When combined with Neon, the debit card also works in the UBS App
Yuh now has its own Twint app :-), so you no longer need to use the UBS Twint app. An alternative is also the prepaid app from Twint!
Thanks for the tip!
When I read all the bad reviews on the Yuh app, it almost makes me sick and I wonder if you have really put this app through its paces yourself. Is your big Yuh experience report really about "great experiences" or just about generating as many Swisscoins as possible for you when someone opens an account based on this experience report?
Hello Rene,
Based on your somewhat negative attitude, I assume that you have already had bad experiences elsewhere. You have read my honest and personal experience. There are other positive experiences here in the comments as well.
In the end, experiences are always individual. In the end, you will have to test Yuh yourself to get the final answer for you personally.
Best regards 🙂
I am new to YUH: The question has arisen for me as to which ETF I should currently save with around CHF 300 per month for the lowest possible fees and high diversification? There are, for example, several Global Blue Chips ETFs.
Hello Dominic
Do you want to start with just one ETF? Or do you want to create a real strategy directly? Here is a ETF Guide for Beginners.
Preferably with only one or two ETFs in Yuh. Aim for a lot of diversification and low fees. What would be your tips?
Hi Dominic, it is difficult to map a sensible investment strategy with just 1 or 2 ETFs. A Broker like Swissquote offers a much broader choice and should therefore definitely be considered for a sensible investment strategy.
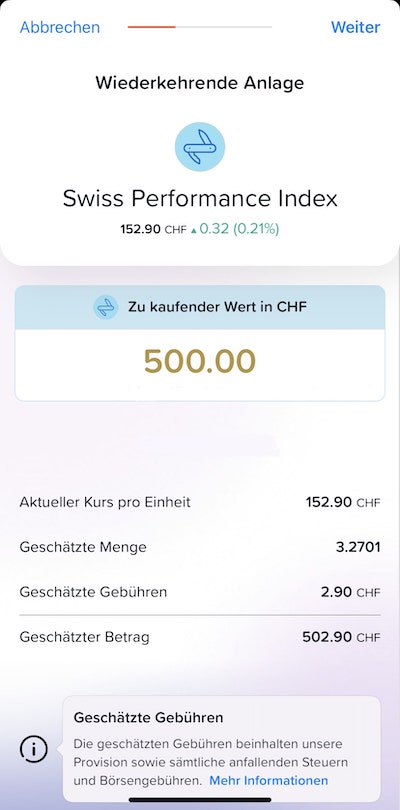
The broadest possible diversification with just a single ETF would probably be possible with an All World ETF (e.g. the Vanguard All World). A smaller admixture could be achieved with equities from emerging countries (so-called emerging markets) or a focus on Swiss equities (e.g. with the SPI - Swiss Performance Index).
However, if you have a significant investment amount, a "clean" structure of your portfolio is very worthwhile, as not only the return but also the risk can be optimised. In the Wealth Letter regularly provides free tips on this topic.
I would also be interested. I would prefer 1 or 2 ETFs?
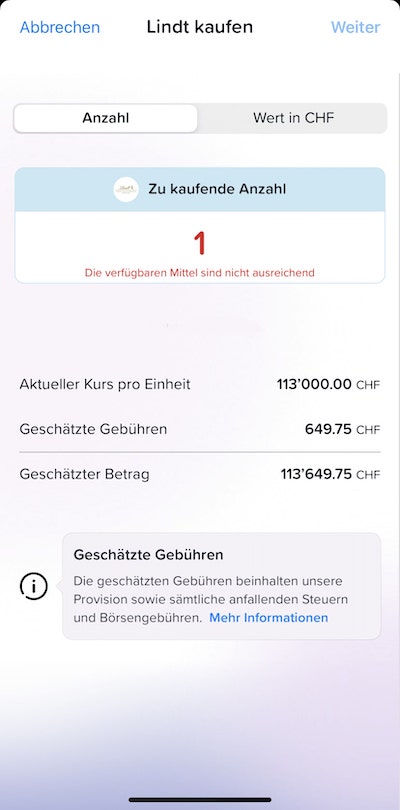
One question, can you register full shares with Yuh? E.g. the Lindt share. If you have 1 full share do you get the case or not, because the share is managed by Yuh?
and is there a possibility to send or transfer shares or cryptos. e.g. from Yuh to Swissquote and vice versa?
lg
Hello Cyrill,
Neither function is yet possible with Yuh. Unfortunately, entry in the share register is not yet possible, nor is the transfer of securities. Perhaps this will change in the future...? You can already do both at Swissquote. Best regards!
No, to get the case you have to be registered in the Lindt share register. Registration is not possible with Yuh.
Hello
I am German and live in Switzerland. I have opened a YUH account. In about a year's time, I would like to deregister in Switzerland and emigrate to the Philippines. Can I still keep the YUH account active and make payments/transfers? Thanks for an answer. Greetings
Officially, probably not. Just try it or talk to the bank.
Dear greetings
Hello
One more question about security at Yuh. Are the investments also considered special assets and are they "protected" in the event of bankruptcy or is the situation different because the investments are only managed in trust?
Kind regards
Beat
Hello Beat
Regular securities such as shares are considered special assets and are protected in the event of insolvency.
Best regards 🙂
Hello Eric
Also fractional shares?
Very good question! I had to do some research on this - what I found: Fractional shares would then not be transferable to other securities accounts, but they are in the special assets and therefore safe in the event of insolvency.
Addendum: There are various ways in which fractional shares can be implemented. Depending on the type of implementation, an issuer risk may arise here.
Hello
I am new to yuh.
Can anyone tell me where, how to find all 13 currencies?
Hello Beat. If you click on the corresponding currency symbol (e.g. Euro) under "Payments", it will then list all available currencies. Greetings.
Servus,
if I deposit € into the YUH account, do the euros remain or are they converted into CHF?
If they stop, what are the charges for this change
Greetings
Martl
Hello Marta
You can also start savings goals in other currencies such as euros and deposit in euros.
Do you have any information on this in the meantime? I would also be interested to know if I can transfer USD from my main bank to Yuh and have it stay there so that I can buy ETFs and/or cryptos in USD without exchange rate fees. After all, Yuh charges 0.95% in fees here.
The $ or euros remain as long as you have enough CHF in the "Pay" account for your expenses. If there is not enough CHF in the account, $ or euros will be taken from the account and changed (0.95%). As far as I know, the account with the highest balance is used. So if you want to leave the foreign currency, it is important that you always have enough CHF.
Alternatively, you can transfer your $ or Euros to "Savings", where it will always remain. If you then need the $ or euros, simply transfer them back.
Today I transferred $ 100 from my house bank to yuh account as a test. I did this after phoning both banks to enquire about any transfer fees. Both banks in unison - no fees.
Result: $ 100 gone at house bank, no fees. $ 95 received by Yuh.
After consulting with Yuh, I was told that a third party bank in the background would/could charge fees between 5 and 25 $.
Hello
Super great blog post, thank you!
Something else that might be worth mentioning is the negative interest rates for capital of CHF 100,000 or more. From this amount onwards, it makes sense to switch to Swissquote!
Kind regards
Ronny
Thanks for your input.
The negative interest rates only count on cash deposits. Very few users will place that much cash with Yuh and with the current interest rate turnaround, it won't be long before the negative interest rates are lifted.
Hello Eric,
One more information I would like to add. you cannot open an account with NEON and ZAK if you are not residing in Switzerland (if you are holding G type Visa or "Grenzgängerbewilligung". however you can do that with Yuh and Revolut.
your blog is quite informative. thank you.
Best regards
T
I bought into crypto on Saturday at 5 pm and the price is going up nicely, unfortunately the transaction takes an hour during which time the price could go into negative territory, .... and after 2 hours I still have no way of getting out with a profit.
Hi Peter, did you consider the official trading hours?
Hello Schwiizer Franke
Thank you for the interesting article. Since I am currently looking for a new custody provider with ETFs and have already researched quite a bit, I would have a few questions about the text.
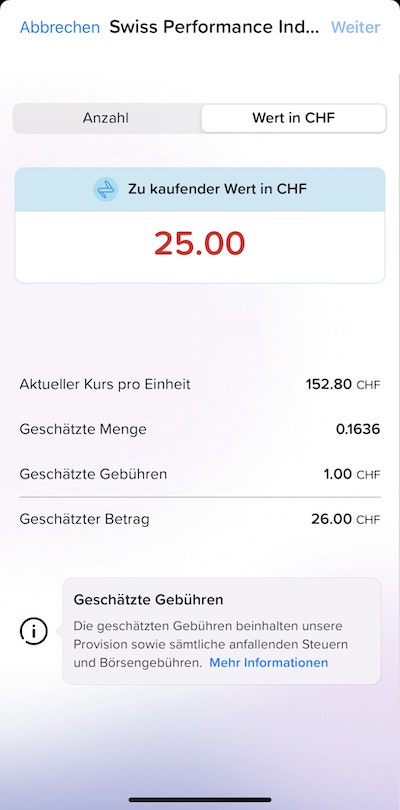
Since there are no custody fees at Yuh, but at least for CHF investments only the percentage fees for deposits (0.5%), I wonder how one can come to 4% costs for a 500 CHF investment. Where do the additional costs come from?
Additionally, I don't quite understand why the size of the portfolio matters at Yuh if there are no fees for this. With Swissquote, I pay at least CHF 9 per ETF deposit plus at least CHF 5 per month in custody fees. Isn't it then the case that at a low portfolio level, investments at Swissquote are only worthwhile from CHF 2,800 per month compared to Yuh, and at a high portfolio level only at even higher amounts?
Hello Christian
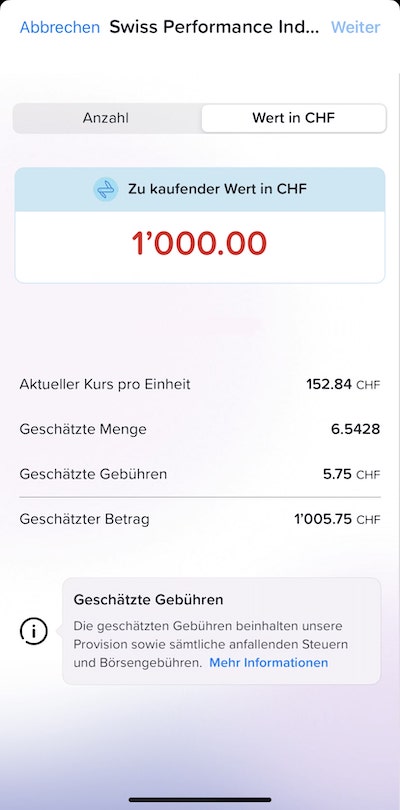
You can calculate the 4% in the example: The ETF purchase of CHF 25 with CHF 1 fees results in a percentage of 4% fees on this purchase. The figures you have taken are not from the example - please look at the screenshot again if you have any questions 🙂 This example is intended to illustrate that small purchases are much more expensive in percentage terms than larger ones.
Hello Eric
Had written to yuh, they don't have a tax statement, but they do have a property statement. Is the tax statement now available? For larger positions, it would be good to know exactly. These are very different.
Hello Mia
According to my information, the tax statement does not yet exist. However, you can use the statement for the annual financial statement for the tax return in order to enter and document your positions.
Maybe something has changed here? If someone knows something, feel free to comment!
Thank you for the detailed article.
I just started using Yuh with 10k deposit, and after a few days I got this message:
"we need to ask you a few more questions. Unfortunately this step is mandatory, and we will be forced to block all payments if you do not answer the questions on the following screens within a month if you do not answer the questions on the following screens. Why do we need this now? This is a routine check triggered automatically, usually the first time that you receive or transfer large amounts of money. We are legally required to gather this information. We will treat it with utmost confidentiality."
The questions are quite personal (job, company name, etc). I never had this with the trading account of my bank, and I wonder why Yuh is legally required to ask these questions. Is this normal?
From what investment amount in the portfolio do you recommend switching to Swissquote?
Hello Loredana,
The switch is not mandatory, as the two platforms complement each other in some cases. For example, Swissquote does not (yet) offer savings plans.
Your question is a good one, but it is difficult to answer in a nutshell. It depends not only on how large a portfolio is, but also how often it is traded. Yuh has no custody fees, but Swissquote does.
I'll be happy to take your question on board and add a few sample calculations to the article - feel free to check back in a few days!
Kind regards
Eric 🙂