



Zak Bank Cler Experience Report 2026: Review, Test & Code
Zak from Bank Cler brings a breath of fresh air to the Swiss banking world. Our Zak Bank Cler experience report shows why this innovative app stands out from the rest and offers a real alternative in the digital banking sector.
In the Zak Review, we take a look at the account, the app, fees and making payments abroad. Our Zak experience has been positive for everyday life in Switzerland. However, there are some drawbacks when using it abroad.
| Behind Zak | Bank Cler, regulated by FINMA, deposit protection up to CHF 100,000 |
| Account management | Free of charge, Zak Plus for CHF 8 a month |
| Card and cash | Zak Visa Debit is free of charge. Withdraw and deposit cash free of charge at Bank Cler ATMs |
| Abroad | 2% Exchange rate premium on card payments, including Zak Plus |
| Interest | 0.05% on the account up to CHF 25,000, 0.2% on Zak Savings up to CHF 100,000 |
| Savings pots | ✅ Yes, which can be shared with partners and friends. Not a traditional joint account |
| Branches | ✅ All Bank Cler branches |
| Investing and 3a | ✅ Zak Invest From CHF 5 commission, custody fee 0.25% per annum with no upper limit. Zak retirement savings (Pillar 3a) in the app |
| TWINT | Via the separate «TWINT Bank Cler» app» |
| Promo code | CHFRAN, CHF 50 starting balance |
| Who is it suitable for? | Anyone looking for a free Swiss account backed by a bank and, above all, who makes payments within Switzerland |
Table of contents
What makes Zak stand out as an online and smartphone bank?
Zak is Bank Cler’s smartphone account. With Zak, Bank Cler launched Switzerland’s first fully-fledged smartphone bank in 2018. Today, Bank Cler offers a comprehensive range of digital and offline banking services. As a Zak customer, you also have access to all Bank Cler branches.
Zak is constantly introducing new, useful features. Solutions such as the savings pots really stand out. These are particularly useful for couples looking for a Swiss joint account. This makes it easy to split money between people, provided both partners have a Zak account.
Further down, you can read our Zak Bank Cler review in detail, including our criticisms.
Bank Cler Zak advantages
Account and card
- Free account: No account maintenance fees or other ongoing costs; you can open one from the age of 12. With the referral code from Schwiizerfranke, you’ll receive a starting balance.
- Credit card and debit card in one: The Zak Visa Debit is free of charge and also works with mobile payments on your smartphone.
- Withdrawing and depositing cash: Both are free at Bank Cler cash machines. Very few smartphone banks allow you to make deposits.
- Fully-fledged online bank: Zak is a sophisticated online banking solution. You can carry out all your banking transactions on your smartphone, including eBill and QR invoices.
Save and Share
- Partner account / savings accounts: Sharing the weekly shop with your partner or splitting the restaurant bill with friends? It’s easy to do with the shareable Zak savings pots.
- Zak: Interest and Saving: The Zak account offers 0.05% interest on balances up to CHF 25,000. With ’Zak Savings«, the rate is 0.2% up to CHF 100,000, with a withdrawal limit of CHF 50,000 per calendar year. This has a positive impact on our experience with Zak Bank.
Bank in the background
- Swiss bank: Swiss deposit protection up to CHF 100,000 and Swiss regulation.
- Branches: Zak is all about digital, online and smartphones. If you do ever want in-person advice, the app will show you the nearest Bank Cler branch.
- Zak Invest: From January 2026, you’ll be able to invest directly via the app in over 12,000 shares, ETFs and funds, starting from CHF 5 per trade on SIX. Please note the custody fee of 0.25% per year. More details in my Zak Invest experience report.
- Zak's Precautions: You can manage your Pillar 3a directly in the app, either as an account or through securities.
Criticism in the Zak Bank Cler experience or negative in the Bank Cler Zak test?
Whether it’s PostFinance, Yuh, Neon or Bank Cler: Each bank specialises in certain areas and offers competitive rates there. For other services, it charges fees. There are five things that bother us about Zak:
- International fees: According to the price list, Zak converts card payments made abroad at the Visa reference rate plus a 2% exchange rate surcharge. For CHF 2,000 in overseas payments per year, this amounts to around CHF 40. Withdrawing cash from ATMs abroad costs an additional CHF 5 per transaction. For frequent card payments abroad, there are cheaper alternatives.
- Zak Plus reduces ATM charges, not the exchange rate mark-up: Zak Plus, at CHF 8 per month, waives ATM fees in Switzerland and abroad. The surcharge of 2% remains.
- Custody fees at Zak Invest: 0.25% per year with no upper limit. For CHF 10,000, that works out at CHF 25; for CHF 100,000, it’s already CHF 250 per year. For larger portfolios, a traditional broker is cheaper.
- Costs at Zak Vorsorgen: According to the price list, the 3a scheme involving securities costs around 1.25% per year. Specialised 3a providers are significantly cheaper in this respect.
- Restricted international payments: Bank transfers can only be made in Swiss francs and euros; international transfers are only possible within the SEPA area.
Is this a deal-breaker? Not for most people. If you mainly spend money in Switzerland, the foreign transaction fees will hardly affect you. We’ll show you exactly how much the card costs abroad further down in the Zak Bank Cler review.
If you travel abroad frequently, it’s worth opening a second account to complement . Neon charges 0.35% abroad, making it significantly cheaper. Both accounts are free to maintain.
Especially when travelling, it is advisable to have several cards in case one card is not accepted.
Partner account Switzerland: Which is the best?
As a couple or family, finding a Swiss joint account – in other words, a shared account – isn’t exactly easy. At UBS and similar banks, a joint account isn’t exactly cheap, as this comparison of partner accounts shows.
Once they’ve started using the service, customers are, of course, firmly tied in. After all, the effort involved in switching – whether for a couple or a whole family – is by no means insignificant.
At Neon Neon Duo offers a paid solution for CHF 3 per month per person. Yuh has been offering a free joint account called Yuh&Me since 2026.
Zak takes a different approach: The savings pots function as the Zak partner account. Here, you can manage joint expenses with your partner or split a bill between friends and pay it straight away.
Just like with PayPal or Twint, you can also request money from others and receive it in real time via «Zak Instant». This works provided both parties have a Zak account. Zak does not offer a standard joint account (an account with multiple cards).
The Zak savings accounts offer you
- Sharing Zak with partners and friends (free of charge)
- Instant payment service for real-time transfers
- Split, manage and settle expenditure in groups
Here's how: Download the app, open a free account & Code: CHFRAN don't forget!
Zak Bank Cler fees
Zak’s fee structure is simple. There are two account options: the free Zak and Zak Plus for CHF 8 a month. Zak Plus is particularly worth it if you often withdraw cash from third-party ATMs.
You can find the exact costs here in the PDF factsheet Bank Cler. An overview of the main Zak fees and differences:
| Zak | Zak Plus | |
|---|---|---|
| Price | free of charge | CHF 8 per month |
| Zak Visa Debit | free of charge | free of charge |
| Cash from Bank Cler ATMs | free of charge | free of charge |
| Withdrawing cash from other banks’ cash machines in Switzerland | CHF 2 per withdrawal (Euro: CHF 5) | free of charge |
| Cash abroad | CHF 5 per withdrawal | free of charge |
| Exchange rate surcharge abroad | 2% | 2% |
| Payments in Switzerland and SEPA payments in euros | free of charge | free of charge |
| Zak Invest Brokerage (SIX) | 0.25%, min. CHF 5 | 0.125%, min. CHF 2.50 |
| Extras | none | Priority Support, free coffee in-store |
Additional charges may apply from third-party ATM operators. Anyone switching back from Zak Plus to Zak can do so once free of charge within 12 months; each subsequent switch costs CHF 40.
Zak Visa Debit Card
Every Zak account comes with the free Zak Visa debit card. This combines a standard debit card with a credit card: you can also use it for online shopping, hotels or hire cars, provided the merchant accepts Visa Debit.
- Free card with no annual fee
- Free cash withdrawals from Bank Cler ATMs
- Mobile payments with Apple Pay and Google Pay
- You can temporarily block the card free in the app
- A replacement card costs CHF 20; a permanent block arranged via a customer service adviser costs CHF 50
- All further information can be found directly at Bank Cler
Zak abroad: How much the Visa Debit costs
Zak used to offer a Zak Visa Prepaid as well. Nowadays, everything is handled via the Zak Visa Debit. That’s why we’re taking a look here at the current Zak fees abroad, for card payments and for cash.
- Card payments abroad: Visa reference rate plus a 2% exchange rate surcharge. For a purchase of CHF 500, this amounts to around CHF 10.
- Cash abroad: CHF 5 per withdrawal plus a 2% surcharge. With Zak Plus, the CHF 5 fee is waived.
- Withdrawing euros in Switzerland: Free at Bank Cler cash machines; CHF 5 at other cash machines, plus a 2% surcharge in each case.
This is fine for the occasional purchase abroad. If you frequently pay by card whilst abroad, Zak isn’t the best choice. A second card with a lower surcharge will quickly prove its worth. You can find an overview in our comparison of prepaid cards.
Zak vs. Postfinance
PostFinance is one of Switzerland’s largest banks, offering a wide range of services and its own network of cash machines. But how does Zak compare with PostFinance?
Zak is the more streamlined account: with no basic fee and managed entirely via smartphone. In return, PostFinance offers more under one roof, such as the option of online brokerage.
A comparison between Zak and PostFinance therefore depends on what you need. We set out the current fees for both accounts in the Bank comparison opposite.
Here's how: Download the app, open a free account & Code: CHFRAN don't forget!
Our financial tips for 2026
"Intelligent people learn from the mistakes of others".
We have compiled our top selection for you from all our tests and experience reports:
Zak vs. Neon
The Zak vs. Neon comparison is particularly fascinating! Here, two of Switzerland’s best-known smartphone banks are pitted against each other. The detailed Neon review tells you everything you need to know about Neon. But what’s the overall verdict in the Zak vs. Neon showdown?
Both are regulated in Switzerland and both offer free accounts. An overview of the differences:
| Zak | Neon Free | |
|---|---|---|
| Account management | free of charge | free of charge |
| Map | Visa Debit, free of charge | Mastercard, one-off fee of CHF 20 |
| Card payments abroad | 2% serve | 0.35% surcharge |
| Cash in Switzerland | Free at Bank Cler cash machines; otherwise CHF 2 | CHF 2.50 at cash machines, free at the checkout at Coop and Lidl |
| Deposit cash | Yes, at Bank Cler cash machines | no |
| Branches | Yes, Bank Cler | no |
| Partner account | joint savings accounts, free of charge | Neon Duo, CHF 3 per month per person |
| TWINT | «TWINT Bank Cler» app» | Prepaid TWINT |
You can see that no clear result can be reached in this head-to-head comparison. Neon is clearly ahead when it comes to international transaction fees. In return, Zak offers cash deposits, savings pots and access to Bank Cler’s branches. What’s more important to you?
The good news: Both providers have free accounts. Lots of people use them side by side. 🤓
Zak Twint & Google Pay & Apple Pay
Zak Twint allows you to simply pay in online shops, shops with a Twint terminal or simply send money between your Zak Twint and another Twint user (regardless of whether they use Zak or not).
Zak TWINT runs via the separate app «TWINT Bank Cler», which you link to your Zak account. The money is debited directly from your account; you don’t need to top anything up.
Zak Apple Pay and Zak Google Pay are also available for making payments with your Zak Visa Debit card.
Zak App Test & Experience Account Opening
You might think that by 2026, it will be perfectly normal for customers to be treated like royalty and to be able to open a bank account with ease.
Schwiizerfranke has already put quite a few banks to the test, and one thing stood out: digitalisation and customer-friendliness aren’t prioritised everywhere. But at Bank Cler with Zak, they certainly are!
Zak account opening
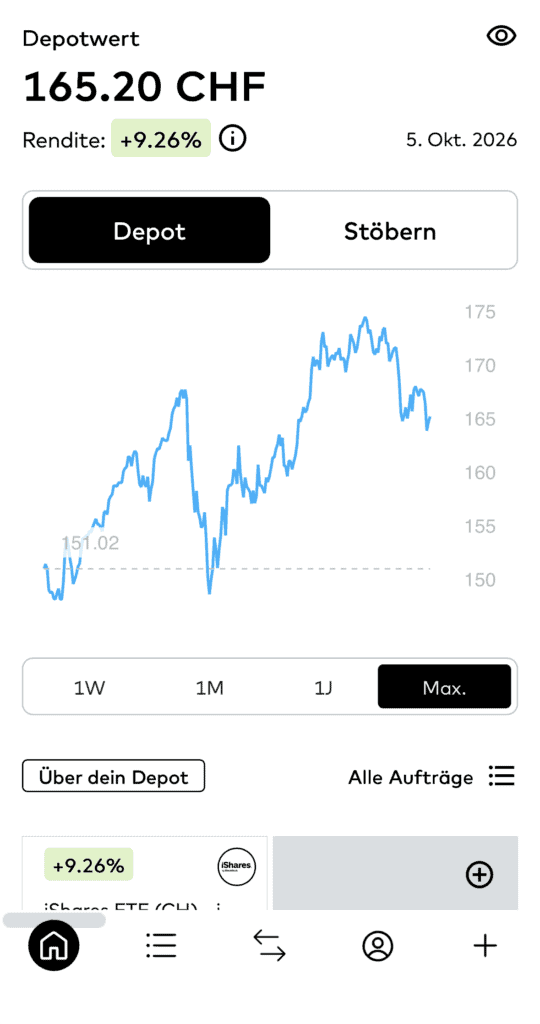
When you have Zak App If you download the app and want to open a Zak account, you’ll be asked to enter the usual details. Here, you’ll also have the option to Code "CHFRAN to enter CHF 50 starting credit to obtain. The Zak experience has been a positive one.
After just a few minutes, you'll be at the end of the data entry process and can be connected to an employee directly in the app. The identity is confirmed via Videoident and that's it! Your Zak account is open.</span
Only a few days later your Zak card will be sent to you by post.
Zak Bank Cler Field Report
Our Zak Bank Cler review: The Zak app is straightforward and works reliably. You can quickly access your account balance, savings pots and payments. You can also use the app to manage your documents, block cards, find a bank branch, take out insurance or take advantage of offers from partners, known as «Zaktionen».
The aspects we are less keen on are listed above in the ‘Criticisms’ section: in particular, the costs incurred abroad and the fees associated with investing and the 3a pillar.
Zak App Tutorial
Open a Zak account: 5 steps to a free account
Want to open a Zak account? Here’s how to do it, straight from the Zak app:
- Download the app: Download the Zak app from the App Store or Google Play Store.
- Register: Enter your details and the referral code CHFRAN Enter a starting balance of CHF 50.
- Confirm identity: Video identification using a passport or identity card takes around 5 minutes.
- Depositing money: Transfer an initial amount into your new Zak account.
- Setting up savings accounts: For example, for holidays, taxes or joint expenses.
Time required: Less than 10 minutes. The Zak Visa Debit card arrives by post a few days later.
Conclusion of the Zak Bank Cler field report
What are the takeaways from this Zak Bank Cler review? Zak is a free Swiss account backed by Bank Cler. Savings pots, cash deposits, a savings account, Pillar 3a and Invest are all in one app, and there’s a branch if needed.
The Zak Bank Cler review shows that, for everyday life in Switzerland, Zak is a convenient banking solution. When making payments abroad, Zak is significantly more expensive than particularly cheap alternatives, with a 2% surcharge. If you travel a lot, it’s better to use Zak alongside a second account.
Zak Review Rating: 4.2 out of 5. Zak stands out as a Swiss everyday current account with a straightforward account opening process, an easy-to-use app, savings pots and branches. Points are deducted for international transaction fees, for Zak Invest when dealing with larger sums, and for the restrictions on international payments.
In a nutshell, then: our experience with Zak has been positive. Our day-to-day experience with the Zak account: reliable, straightforward and well-suited for many people as a main account or savings account.
What have been your experiences with Zak? Please do let us know in the comments!
Will you make Zak your second account and test it?
FAQ
How does TWINT work with Zak Bank in Switzerland?
TWINT works with Zak via the separate TWINT Bank Cler app - not directly in the Zak app. You need to install both apps and link the TWINT app to your Zak account. Unlike Yuh, there is no integrated TWINT function.
Swiss franc test (February 2025): The link took 3 minutes, but works reliably. Payments at Coop, Migros and SBB machines work without any problems.
Swiss speciality: Zak also supports the QR-bill perfectly - simply scan with the camera and pay. International neobanks like N26 or Revolut can't do that.
Is Zak Bank Cler safe and reputable?
Yes, Zak is absolutely safe. Zak is part of Bank Cler (formerly Coop Bank), which has been operating in Switzerland since 1927 and is regulated by FINMA. Your deposits are protected up to CHF 100,000 by the Swiss Deposit Guarantee Scheme.
Insider info: As one of the few financial blogs with direct contact to Bank Cler, we can confirm this: The security standards correspond to large Swiss banks such as UBS or Credit Suisse.
How much does Zak Bank actually cost?
The basic account and the card are free of charge. Fees apply in the following cases:
- Foreign payments: 2% Surcharge on the exchange rate, including with Zak Plus
- Cash withdrawals from other banks: CHF 2 per withdrawal in Switzerland, CHF 5 abroad
- Card replacement: CHF 20
- Card blocking: CHF 50 for a permanent block via a customer adviser. Temporary blocking via the app is free of charge
- Zak Plus: CHF 8 a month, and all cash withdrawals from ATMs are free of charge
- Zak Invest: Brokerage fees from CHF 5, custody fee 0.25% per annum
Zak Plus is worth it if you make around four withdrawals a month from third-party cash machines in Switzerland.
Our financial tips for 2026
"Intelligent people learn from the mistakes of others".
We have compiled our top selection for you from all our tests and experience reports:
The Zak Bank Cler experience report was created in cooperation with Bank Cler. At Schwiizerfranke.com we are independent and free. That's why we only recommend offers that we use ourselves and with which we are completely satisfied. Disadvantages for you? No. Advantages? Yes, because the collaboration enabled us to use the CHF 50 Zak voucher code for the Zak app. organize for you!
How much does a tax statement actually cost here?
Hello Sany
At Zak Invest, it costs CHF 75 – but you don’t need one for the «standard» Zak account; the standard, free statement is sufficient here.
Many thanks for the summary. However, I do not find the report objective enough in one crucial point: the article does mention the trading fees from CHF 5, but the custody account fee of 0.25% p.a. is treated as a side note. The problem is that this fee is not capped. For investors with a larger portfolio, Zak quickly becomes a cost trap compared to other brokers or neobanks. While the fee for a CHF 10,000 custody account is still a moderate CHF 25, for CHF 100,000 it is already CHF 250 per year - just for custody. Zak may be okay at best for occasional investors with very small amounts, but for serious asset accumulation it performs significantly worse in comparison to competitors (such as Neon, Yuh, Saxo etc. with 0% custody account fees) due to the percentage-based, uncapped custody account fees.
Hello Roger,
That is absolutely the case. Very few people will have such large assets under management with a neo-broker app, but if they do ...
In any case, all Zak Invest topics are only touched on here in the general banking experience report. The details (and also the fees) can be found in the Zak-Invest experience report described in more detail 🙂
Hi Eric
Is your code CHFRAN still valid?
LG
Of course 🙂
I don't understand why UBS is always portrayed as expensive in situations like this. We pay CHF 15 per month for a «Family» account, which gives us two private accounts and unlimited savings accounts as well as free credit cards. That seems to me to be a much better offer than most other banks.
If you think that CHF 15 is the only fee you pay, you are sadly mistaken.
Account management fees are only part of the bigger bill. The UBS offer is not bad, on the contrary, but it comes at a price. Here are a few insights into the UBS test report.
I am looking for a bank with a balance preview in the app, like CS used to have, based on actual invoices and standing orders. I transferred to UBS, and these hypothetical insights are of no use to me. In addition, the bank charges 30 centimes for each domestic transfer/standing order, plus CHF 5/month for account management. This costs me 10-12 Swiss francs every month.
I had opened an account with YUH, but there is no balance preview there either. Furthermore, even with support, I cannot get the TWINT app to work.
I've also been using neon (free) for a few years now, but I haven't quite brought myself to transfer everything to neon Bank yet (there's no balance preview either).
This is important feedback, which I will gladly pass on to my contacts at the online banks! Neon, for example, has AI insights that offer very exciting analyses of spending – previewing your balance should actually be easy to implement!
Hello Deb
The balance preview is also very important to me. If you are still looking, Migros Bank has it.
Greetings
Nadine
Hi Eric
Thank you for your comments:-)
I opened the account and immediately created Zak Savings -> the annual withdrawal amount is now CHF 50,000.
Your code for CHF 50 worked great and was credited within 24 hours:-)
Many thanks and best regards Thomas
I'm glad - thanks for the feedback 🙂
Hello, Eric,
I am looking for a suitable account for my 87 year old mother. She is with a traditional bank and therefore has relatively high expenses. We pay her bills via app or LSV and we have one ATM visit per month. What would be an optimal simple solution that we could set up for our mum and that we also have access to or can help her pay bills? Some interest would also be great of course? Is there anything sensible for senior citizens?
Many thanks
Urs
Hello Urs,
then I would suggest you take a look at the Bank comparison to see. Free cash withdrawals + interest with free account management are available there!
Because of her age, you will have to see how she can handle online banking etc. (unless you take over all the tasks involved).
Otherwise a suitable local bank?
Are you sure this is the 2025 experience report? "Zak offers +1.00% interest on your normal Zak account" - this is probably no longer true as of February 2025. Currently it's probably more like 0.1% up to 25k, then 0% (https://www.cler.ch/de/info/zinssatze-fur-privatkunden#zahlen).
Thanks for pointing that out, Joe. The interest rates were recently adjusted (again) - the article is now up to date again.
Thank you Schwizerfranke for the useful contributions.
I'm still looking for a place for my nest egg and came across ZAK because of the high interest rate.
Is a ZAK account only suitable as a savings account and possibly as a second salary account (with several incomes)?
Hello Cusi,
definitely, Zak has very exciting functions, such as the savings pots or, for example, the savings account with quite high interest rates.
If you spend a lot of time abroad, there are more favourable exchange rates at alternative banks, but otherwise you'll do very well with Zak.
At the moment, it's definitely worth checking out the latest ZAK/Cler reviews on Trustpilot. Something seems to have gone very wrong recently.
https://ch.trustpilot.com/review/cler.ch
Thanks for the tip - it's important, but be careful: This is how it looks on Trustpilot for almost every bank, because usually only disgruntled customers report online (satisfied customers don't write, while disgruntled customers write back). very out loud - unfortunately that's the way it is on the Internet).
According to the report, Bank Cler has over 250,000 clients, while only 175 people have commented on Trustpilot, i.e. less than 0.07%. Just to put it into perspective.
Hello,
Can you inform me if it is possible to open an account as a french national and resident and if yes the foreign transfers fees please.
Thanks,
Jean
Hello everyone - can the "partner account" be used as a direct debit? In other words, if my partner and I want to pay mortgage interest by direct debit from a partner account, does ZACK Bank also make sense here as a Zak partner account?
Many thanks and greetings
Hello, I would be interested in Zak as a partner account. As I understand it, it is not possible to open a joint account, is it? The account would then be in the name of a partner (also relevant for tax purposes)?
But would it theoretically be possible to use a second debit card?
Previously, two accounts had to be opened (which are then also allocated to each individual for tax purposes). Joint expenditure can then be managed via a linked savings pot. This means that two debit cards are also available, but these belong to separate accounts.
so i've tried Zak now and so far i'm pretty dissatisfied. the good thing was i was able to open it with my temporary residence permit, but otherwise i don't find anything good about it.
The app has been down several times in the last few weeks and I find it very confusing. You can't find bank details, only the IBAN, which is often not enough. The pots are not intuitive and not suitable for saving. I will cancel the account again as soon as I have found a new one.
Thank you for your feedback.
Each app has its own design, of course, and is ultimately a matter of taste.
Regarding help in the Zak app, I can highly recommend the chat function. If you enter "BIC" there, for example, you will instantly receive the BIC of Bank Cler.
You can find an alternative smartphone bank with savings function here.
ZAK is unfortunately out of the question for me just because of the bad exchange rates and/or hidden foreign currency fees.
Nevertheless, I registered with ZAK as a test (keywords "skin in the game") and in July 2022 I made two credit card payments in euros less than three minutes apart (in the same online shop).
ZAK (Visa prepaid) charged CHF 27.14 for EUR 26.87, Neon (Mastercard prepaid) charged only CHF 26.29 for EUR 26.89.
All in all, ZAK added 3,31% to the Neon price in this example! This is really not a good price, and larger sums can add up to quite a bit.
Hello, Eric,
Thanks for the review. What about negative interest rates? Haven't found anything on this...
Hi Karin, as far as I know there are currently no negative interest rates at Zak. Currently, there are even signs of an interest rate turnaround by the US Federal Reserve, so the issue may soon no longer be relevant anyway. If you want to be sure, just ask Zak. Or you can switch again if negative interest rates are charged.
Zak has now replaced the Maestro card with a (full-fledged?) VISA debit card and the costs abroad have also been reduced. Could you take this into account in the article, or adjust? Thank you.
The update is already in progress 🙂 Thanks for pointing it out!
Yuh... Hello, I would recommend the new Yuh app from PostFinance/Swissquote, I think it's absolutely amazing. lg
Hey Reto, I'm currently testing Yuh myself. However, I find it difficult to make a direct comparison. Yuh is a combination of bank account and trading platform. That sounds exciting (it may be for many - don't get me wrong), but I personally quickly come up against the limits of Yuh's attractive offering.
If you use Yuh as a bank account, it bothers me if I can only withdraw cash once a week. If you use Yuh for trading, it bothers me that the fees are higher and the offer is narrower than with comparable brokers (such as Swissquote direct).
For the entry certainly interesting because everything is kept simple and simple, or for digital minimalists (fewer apps / accounts on the phone). Nevertheless, Yuh has its justification and I am generally pleased that some movement comes into the online broker market in Switzerland because here we lag behind the offer in our neighboring countries years.
What makes yuh special to you 🙂 Thanks for your feedback!
Hello,
I understood that the ZAK Prepaid VISA card you described is available as a plastic card. But Bank Cler said it was only available virtually. Is that so?
Thanks for the answer
Hello Silvi
The prepaid card is a virtual card. It can be digitally attached to your normal Zak card if you wish: You top up the virtual card with credit and can therefore "delete" it again very easily. This is particularly advantageous if you pay at places where you are concerned about the security of your payment data.
Does that help you? 🙂
Dear greetings
Yes, merci vielmal
Hi Schwiizerfranke!
Couple of questions:
- does your Zak referral code still work if I were to open an account now? (is it still 50 opening balance?)
- do you know whether Zak plan on having their own Twint ? (i.e. not the UBS free for all)
Thanks!
Hi Chris
thanks for your message!
Yes and yes! The code is still working and TWINT is available already now with Zak!
Cheers 🙂
Hello Eric
Does this still apply a year later, meaning does the Zak Referral Code still work today?
Greetings and thanks
Hello Nicolas, yes the code still works today and credits you CHF 50 🙂
All right, thank you 👍
I do not agree with Bank ZAK. Response time from customer service takes 1 week and app partly does not work properly.
Anyway, I cancelled the account with them again today. Too unreliable for me.
Hello Schwiizerfranke
Can I also create a rental or deposit account with ZAK (or NEON)?
My landlord wants either that, or a bank guarantee (for 150 CHF+ per year)
Hello, Bernd,
with Zak and neon not directly. Zak belongs to Bank Cler, where you can do this for example: https://www.cler.ch/de/privatkunden/sparen/mietersparkonto
The same applies to the Migrosbank or other places, just pay attention to the fees.
Many greetings
Eric
Which banks are currently most worthwhile in Switzerland? At the moment I and my wife each have an account with ZKB with various savings accounts, 3a as well as a joint household account (a 2 cards)... but it also costs around 100.- pP..... per year. Lg
Hello, Christoph,
Thank you for your message!
An account or a bank must of course always fit your needs. The ZKB account with all Add Ons is certainly justified. But if you say that the 100CHF is bothering you then you can consider a change.
For this I can recommend to open the new account first and test it on the side and then move everything bit by bit. This gives you the possibility to test and avoids chaos or forgotten bills etc.
In general, it can also be said that a comparison of the individual products is often worthwhile. As with insurance, it is often a good idea to look at the products in detail. In other words, choose a good, suitable bank account and consider the 3a solution separately. This way, you can choose the variant that best meets your requirements.
To answer your question: A recommendation suitable for everyone cannot be made. For example, I use Zak and Neon as bank accounts, and Viac for pillar 3a.
Many greetings!
Hello Schwiizerfranke
I'm actually thinking about trying out Zak and Neon. I have a question about Neon. In your experience report you write: "We negotiated with Neon and landed a deal for you: Free account incl. cards and 10CHF starting credit as a gift with the code Schwiizerfranke" Is that still the case? Since Neon advertises the card on their website with 10 Fr for the plastic, so the card probably costs 10 Fr?
Hello Georg,
Thank you for your message and for studying the articles carefully!
Yes, the offer at Neon is still valid (if this changes, we will change the article) You will get 20CHF as an indirect gift. The card is free of charge and the 10HF starting balance will be credited to your account a few days after opening the account. Provided you enter the code Schwiizerfranke.
With Zak, you can enter the code CHFRAN after opening an account and you will be credited with 50CHF 🙂
Many greetings and see you soon!
Eric
Hi, Eric,
thanks for the answer, then I will try only neon for now (need the card mainly to make online purchases in foreign currency)
George