finpension invest experience

Finpension Invest experiences: Test report 2026

Are you looking for a smart way to invest your money? With ยซFinpension Investยป Since 2024, Finpension has been offering a solution that allows you to convenient, affordable and with very exciting functions can.

In this review, youโ€™ll gain an in-depth insight into our experience with Finpension Invest: fees, pros and cons, and how the service compares with other providers.

In a nutshell: Finpension Invest is a robo-adviser for your personal assets, regulated by FINMA. You can invest from as little as CHF 1, pay a management fee of 0.39% plus product costs of around 0.08 to 0.10%, and can hold up to 10 portfolios.

๐Ÿ† finpension Invest: Key facts at a glance
RegulationFINMA-licensed securities firm
Minimum investmentCHF 1
Total costs p.a.0.47% to 0.49%
Custody feeTax deductible
US withholding taxDA-1 reporting available, credit subject to the tax authorityโ€™s approval
portfoliosUp to 10 incl. joint portfolio
Pillar 3a / Vested benefitsโœ… Yes
Childrenโ€™s investment account / Childrenโ€™s portfolioโœ… Yes, is registered in the parentsโ€™ names
Private MarketsFrom CHF 1
AttentionOnly with residence in Switzerland
Promo codeCHFRZ5: CHF 25 fee credit
Who is it suitable for?Swiss investors who want everything in one place
๐Ÿ’ก Schwiizerfranke assessment: finpension Invest is our favourite. DA-1 reporting, tax-deductible custody fees and up to 10 portfolios set it apart from the competition. All providers in comparison โ†’

Table of contents

What is Finpension Invest?

My Finpension Invest review: ยซFinpension Investยป is Finpensionโ€™s investment solution for your non-pension assets, available since May 2024. Finpension is a leading provider of pension solutions in Switzerland. This offering allows you to invest your disposable assets (i.e. not in your pension scheme) at a very low Entry threshold of just one franc into a Broadly diversified portfolio to invest. Whether you want to invest in traditional markets using ETFs and index funds or in exciting private markets (private equity), ยซFinpension Investยป offers a flexible and convenient solution.

The solution is not only in the Finpension Appbut, as stated by the Final pension provision used to working in a Web solution available for the computer.

Finpension is from the FINMA licensed as an investment firm. This means that Finpension manages your investment account itself, without a partner bank acting as an intermediary. Since January 2025, Finpension has also been a member of Swiss Interbank Clearing (SIC). As a result, deposits are credited more quickly and you receive a separate IBAN for each portfolio.

Thanks to the Finpension Invest savings plan feature, contributions can be made automatically. In addition, a Automated payout plan for positive experiences with Finpension Invest.

What makes the Finpension investment solution special is its unique Tax optimisation with Finpension Invest ETFs โ€“ more on this in a moment. In addition, there are tax-deductible custody fees and the option to already from CHF 1 in private markets Investing: two ways in which Finpension stands out from many other providers.
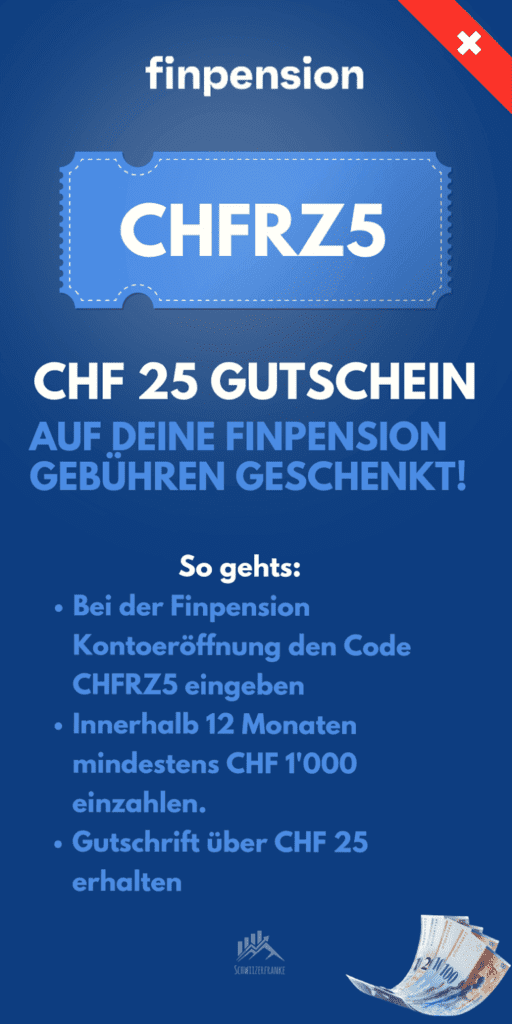
Finpension voucher code Finpension voucher Finpension Invest code finpension invest referral code finpension invest voucher
CHFRZ5

Finpension Invest fees and cost structure

The clear fee structure makes it easy to understand the Finpension Invest costs to understand and compare.

Finpension Invest fees at a glance:

Cost type Fee Note
Asset management 0,09% - โ€“
custody 0,30% tax deductible
all-inclusive fee 0,39%
Product costs (TER of ETFs) 0.08โ€“0.10% depending on the strategy
Total costs per year approx. 0.47โ€“0.49%
Currency exchange no surcharge Finpension will cover the costs
Transaction fees none excluding stamp duty and stock exchange fees

The tax-deductible custody fee gives you an additional benefit of approximately 0.075% at a marginal tax rate of 25%.

This transparent cost structure is a good basis for a positive Finpension Invest Test Report. After all, low costs are the basis for long-term successful investments.

Finpension Invest Tax optimisation: look-through reporting

Reclaim US withholding tax: the hidden Finpension Invest advantage

With US dividends, you usually lose money due to withholding tax. Finpension has developed a ยซlook-throughยป reporting system in collaboration with BlackRock, which allows you to reclaim these taxes, provided your tax authority recognises it.

Step Withholding tax How
Without optimisation 30% US withholding tax
With Ireland ETFs 15% double taxation agreement
With Finpension DA-1 Reporting up to 0%* Flat-rate tax credit (*provided this is recognised by the tax authorities)

What are the specific benefits?

With a US dividend yield of 2%, this results in a Yield advantage of up to 0.30% on your US holdings. With an investment of CHF 100,000 and around two-thirds of your portfolio in US shares, that works out at around CHF 200 a year, with very little extra effort via the DA-1 form.

You will receive the report free of charge at the start of the year. Important: Recognition of this report has not yet been clarified nationwide in Switzerland. According to Finpension, one canton has accepted the report, whilst another tax authority has rejected it. An appeal has been lodged against this decision with the aim of obtaining a judicial ruling. You should therefore make a conservative estimate of 15% and treat the additional credit as a potential bonus. You can find details of the procedure directly at Finpension on the blog.

Top recommendations for 2026

Your key to success! Discover our top recommendations from real testimonials.

Comparison of Finpension Invest with other providers in Switzerland

To better understand Finpension Invest's positioning in the market, it is worth comparing its offering with other leading providers of passive investment solutions in Switzerland. We have looked at some of the most relevant platforms to give you a good Finpension Invest comparison.

Comparison of digital asset managers: Finpension Invest vs. Findependent vs. True Wealth vs. Viac Invest

ProviderTotal feesMinimum investmentUS withholding taxSpecial features
Finpension Invest0.47โ€“0.49%CHF 115%, with DA-1 or, where applicable, 0%Community portfolio, private markets, tax optimisation
True Wealthapprox. 0.37โ€“0.62%ยฃ8,50015% (or 0% with Saxo)Individual portfolios, children's portfolios
Findependentapprox. 0.41โ€“0.65%CHF 50015%Up to 5 investment pots, ESG focus
Selma Finance0.64โ€“0.90%ยฃ2,00015%AI analysis, simple onboarding
VIAC Investapprox. 0.34โ€“0.52%CHF 130%Integration with VIAC 3a, including stamp duty and currency conversion

Total fees = management fee plus product costs, depending on the strategy and investment amount. As at September 2026.


Finpension vs Findependent: Which is better?

In a direct comparison between Finpension and Findependent, Finpension is usually cheaper for small and medium-sized investment amounts, whilst for large portfolios the two are very similar. The main difference is that Finpension offers withholding tax reporting, whereas Findependent does not. Furthermore, with Finpension, you can start with as little as CHF 1, rather than CHF 500. Findependent, on the other hand, manages the first CHF 2,000 free of charge.

Finpension Invest vs VIAC Invest

VIAC followed suit in 2024 and also launched a robo-advisor. The overall costs are similar, but there is a difference when it comes to withholding tax: VIAC mainly uses Swiss funds for US shares, which means that a large proportion of US dividends 30% Withholding tax are incurred. Finpension uses Irish ETFs and incurs a loss of just 15%. These can even be reduced to 0% will be recognised, provided your tax authority accepts this.

To be fair: VIAC charges a management fee of just 0.25% and has stamp duty and currency conversion already included, which partly offsets the tax disadvantage. When it comes to US withholding tax, Finpension has a clear advantage. Whether itโ€™s the better choice overall also depends on your strategy and personal preferences.

Detailed comparison points of the Finpension investment solution

  • Fee structure: Finpension Invest stands out thanks to its low-cost all-in fee and the fact that its custody fees are tax-deductible. This offers a cost advantage over many providers, particularly for long-term investments.
  • Investment access and minimum volume: Whilst Finpension Invest allows investments to start from as little as CHF 1, thereby offering particularly low barriers to entry, many other providers set higher minimum investment amounts, which makes it more difficult for retail investors to get involved.
  • Innovative features: What makes Finpension Invest unique is its direct access to private market investments and the use of tax-optimised ETFs, which are often not available from traditional providers. Furthermore, not all providers offer payout plans. Finpension therefore offers a highly innovative investment solution and has continuously added new features since its launch, such as the collective portfolio.
Finpension Invest Build your own investment strategies
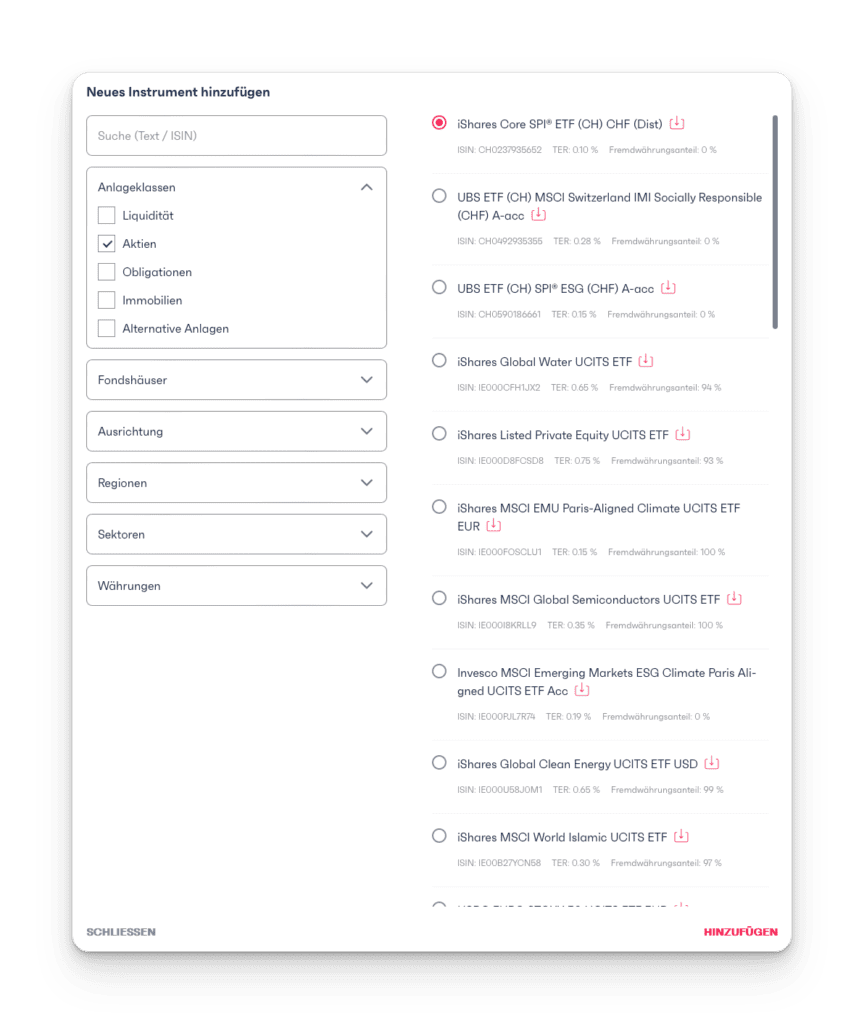
With ยซSelf Selectยป, you can choose each investment individually and thus build your own personal ETF portfolio, for example.

Why choose Finpension Wealth?

  • Flexibility and diversification: With the possibility of investing from one franc and even investing in private markets (companies that are not listed on the stock exchange), Finpension Invest offers an extremely high degree of flexibility and diversification of risk.
  • Tax advantages: The tax-deductible custody fee can increase the net return, which is a key advantage, particularly in a low-interest-rate environment. The ยซlook-through reportsยป for tax optimisation can also have a positive impact on the return, provided your tax authority recognises them.
  • eTax extract: The extremely convenient digital eTax Finpension tax statement is available free of charge in the app.
  • Transparency and cost control: No hidden costs and complete transparency of Finpension fees ensure a clear and fair offer.

Finpension voucher

To do this, use the Finpension Invest voucher code CHFRZ5 when opening your account (or within 24 hours afterwards in your profile) and deposit at least CHF 1,000 within one year.

Our financial tips for 2026

"Intelligent people learn from the mistakes of others".

We have compiled our top selection for you from all our tests and experience reports:

Special functions and Finpension Invest advantages

Finpension Invest is introducing a number of innovative developments โ€“ some of which have already been mentioned above โ€“ to the world of digital wealth management. Here is an overview of the key benefits of Finpension Invest:

  • Create up to 10 individual portfolios: This flexibility allows you to pursue specific financial goals with precision, be it for retirement, the next car purchase or even a children's portfolio. You will learn this concept of targeted investments in the Financial Roadmap course at Finanzuni.ch and therefore stands out particularly favourably in the Finpension Invest Review.
  • Joint portfolios for couples: From 2025, two people will be able to manage a portfolio together โ€“ perfect for married couples and life partners. Both will have full access to make deposits, change the investment strategy and make withdrawals without needing to consult each other. In the event of one partnerโ€™s death, the other partner retains access, which helps to avoid financial difficulties during the transitional period. Each person receives a separate e-tax statement for their individual tax return. Finpension Joint portfolio is an offering that is not available from most other robo-advisors and significantly simplifies joint saving towards investment goals.
  • Portfolio diversity and customised strategies: You can customise the Finpension Invest strategies to suit your needs. You can adopt the ready-made portfolios, or tailor them as you wish; with ยซSelf Selectยป, you can even choose the individual ETFs from the shortlist yourself.
  • Tax optimisation: Finpension is even campaigning at a political level to reduce the tax burden on ETFs subject to withholding tax in the US. One canton has already accepted the reporting, whilst Finpension is seeking a judicial ruling from another tax authority. The so-called ยซlook-through reportsยป for your tax return form the basis for this โ€“ and, incidentally, you receive them free of charge. These are innovative and are designed to ensure lower taxes. Furthermore, the clear distinction between the custody fee (0.30%) and the management fee (0.09%) within the all-in fee of 0.39% is helpful. This is because you can usually deduct the 0.30% custody fee on your tax return.
  • Savings plans and flexible payment plans: With a Finpension Invest savings plan, you can automatically invest your money each month. And should you ever want to make withdrawals, you can set up flexible payout plans. Do you need, for example, an extra CHF 500 a month on top of your AHV and pension scheme benefits? No problem โ€“ simply set up an automatic payout plan. One-off withdrawals or transfers between your Finpension pension scheme and your Invest account are also possible.

Finpension voucher

  • Access to private markets: Normally, private markets (companies that are not listed on the stock exchange) are only accessible for very large sums and only to selected investors. With Finpension Invest, you gain access to private market funds (private equity) that would otherwise not be available to retail investors. As these carry a higher level of risk and the money is tied up for a fixed period, you must pass a knowledge test. If you answer any questions incorrectly on the Finpension platform, the investment opportunity will not be available to you. Here is some information nonetheless:
Advantages of private markets:
  • Higher return potential: Often higher expected returns than traditional markets.
  • Diversification: Offers an additional opportunity for risk diversification, as most companies are not even listed on the stock exchange.
Private Markets Disadvantages:
  • Higher fluctuation and risks: Private investments can be less transparent and more difficult to value.
  • Liquidity restrictions: These investments are often less liquid than public markets, so they cannot be traded at any time, as you are used to with shares.

In this Finpension Invest review, youโ€™ll no doubt notice just how innovative the solution is. The service has been live since May 2024 and has received a steady stream of exciting updates ever since. To ensure we donโ€™t just highlight the positives, letโ€™s take a look at the drawbacks and missing features:

What are the disadvantages of Finpension Invest?

Even a top provider isnโ€™t perfect. You should be aware of these drawbacks of Finpension Invest:

  • Only for residents of Switzerland: If you wish to open a Finpension Invest account, you must be resident in Switzerland and liable for tax there. US persons are excluded. This restriction applies not only to foreign nationals without Swiss residence but also to Swiss nationals who are leaving Switzerland permanently. If you emigrate and deregister, you must also close your account with Finpension.
  • Robo-advisers instead of brokers: As with all robo-advisors, Finpensionโ€™s fees are calculated as a percentage of your assets. For very large portfolios, a low-cost broker charging a flat-rate custody fee may offer a better deal than Finpension. In that case, you select your own investments and handle purchases, rebalancing and tax documentation yourself. If you donโ€™t want to do that, a robo-advisor like Finpension is the best option for you. More on this in the next section.
  • DA-1 advantage not yet secured: Whether you can claim a credit for the remaining US withholding tax via your tax return depends on your tax authority. The matter is still being clarified across Switzerland.

All in all, these are restrictions that are of little significance to most investors with a savings plan or small to medium-sized assets.

For whom is Finpension Invest suitable and for whom is it not?

Finpension Invest is suitable for for people who want to invest their assets in a convenient and uncomplicated way. The functions allow very uncomplicated investment.

Savings plans for building up your assets, a wide range of investment options, low costs, features that can be combined with pension schemes, right through to automatic payout plans. Theyโ€™ve thought of everything!

Finpension Invest is not suitable for people who would like to invest actively in individual securities because there are no functions available for active trading (limit orders etc.) of individual securities.

Furthermore, Finpension Invest is less suitable if you are building up a very large portfolio, want to keep fees as low as possible and prefer to manage your investments yourself. This is because, as with all robo-advisors, the percentage management fee adds up when dealing with large sums. Whilst brokers also charge fees for ETFs and transactions, holding a large portfolio in particular costs less. For example, an ETF costs just 0.15% TER per year plus the custody fee. For very large portfolios, youโ€™re better off with a good Online brokers โ€ฆso it works out cheaper, provided you donโ€™t mind the extra effort.

Our financial tips for 2026

"Intelligent people learn from the mistakes of others".

We have compiled our top selection for you from all our tests and experience reports:

Conclusion on the Finpension Invest experience

Finpension Invest provides you with an innovative and flexible investment solution with which you can inexpensive and Convenient assets can set up. In my tests, Finpension Invest ranks amongst the best robo-advisors in Switzerland.

Is Finpension reputable? Absolutely. finpension AG manages over CHF 6 billion on behalf of more than 75,000 clients (as at August 2026), has been in the black since 2019 and, as a FINMA-licensed securities firm, is directly supervised by the Swiss Financial Market Supervisory Authority.

Functions for transactions from and to Finpension pension accounts (3a and 1e) are available. Tax advantages can have a positive impact on the Finpension Invest return.

The range is rounded off by smart Savings plans and payout plans that are ideally suited to living off your capital in retirement.

Access to Private Markets is also outstanding and innovative, but should be approached cautiously and, if so, only with a small admixture, as there are increased risks.

If youโ€™re interested in getting started, please feel free to use the following Finpension Invest voucher code, CHFRZ5, to receive a CHF 25 credit towards fees. That way, youโ€™ll not only save on Finpension Invest fees, but youโ€™ll also be supporting further research, such as this!

We are all looking forward to your personal Finpension Invest test and your comments on it!

FAQ

At Finpension Invest you can already from CHF 1 invest in a range of investment strategies, which makes Finpension particularly accessible. This also applies to the Savings plan and even for Private Markets. This makes Finpension Invest ideal for those starting out with small amounts.

Private Markets are shareholdings in companies that are not listed on the stock exchange, for example via Private Equity. They offer additional Diversification and often offer higher potential returns, but are less liquid, which are more difficult to assess and involve higher risks. Hereโ€™s how to add them to Finpension Invest:

  1. Open a separate portfolio: Private markets are held in a separate portfolio. To do this, select the โ€˜Private Marketsโ€™ strategy when choosing your portfolio.
  2. Answer the multiple-choice questions: Before you can get started, youโ€™ll need to answer a few questions to demonstrate your knowledge of this asset class. Only then will the service be activated.
  3. Select a fund: You can then choose between the private equity funds offered by Partners Group (ยซPartners Fundยป) and Schroders (Schroders Capital Semi-Liquid Global Private Equity) choose, already from CHF 1.

Our tip: Private markets are suitable, at best, as a small amount to a broadly diversified ETF portfolio.

Yes, there is one Free Finpension Invest tax statement. The digital eTax statement (E-tax statement) can be found directly in the app and can be easily imported into your tax return.

In addition, at the start of the year you will receive the detailed DA-1 Reporting on the US dividends from your ETFs. This allows you to claim the flat-rate tax credit and reduce your tax liability, provided your tax authority accepts the reporting.

Finpension Invest offers you the following straight away two tax benefits:

  • Deductible custody fee: The fee of 0.39% is broken down into 0.30% for custody and 0.09% for asset management. The 0.30% Custody fee You can usually claim this as a deduction on your tax return. With a marginal tax rate of 25%, this amounts to a benefit of around 0.075% per year.
  • Optimisation of ETF withholding tax: Thanks to Irish ETFs, you pay just 15% rather than 30% in withholding tax on US dividends. With the free DA-1 Reporting you can also apply for the flat-rate tax credit and the withholding tax except for 0% reduce, provided your tax authority accepts the report. One canton has already accepted it; the process of clarifying this across Switzerland is still ongoing.

Yes, regarding the purchase. As soon as you have transferred your credit from the Pillar 3a, the Freedom of movement (FZ) or the 1e Pension Scheme are entitled to receive, you can withdraw the capital paid out at Finpension Invest continue to invest the remaining assets. Regular withdrawals are possible no earlier than five years before the AHV reference age; early withdrawals may be made, for example, to purchase a home, to set up in self-employment or in the event of permanent emigration.

Particularly handy: If youโ€™re already at Final pension provision, you can transfer the money you have received directly into your Invest portfolio and, with a Payment plan to receive a regular pension.

Important: Whilst the money is tied up, only one change is permitted within the pension scheme It is possible, for example, to switch from another 3a scheme to finpension 3a.

There is both a Finpension App for iOS and Android, as well as a Desktop solution in your browser. Finpension Invest is integrated into the existing platform: If youโ€™re already using the Pillar 3a Or, with the freedom of choice offered by Finpension, you can find the Finpension investment solution within the same app and view your entire portfolio at a glance.

With a Payment plan You specify the amount to be paid out regularly from your portfolio into your reference account. This is how you generate regular income from your investment capital, ideal for planning your finances in Retirement.

Hereโ€™s an example: youโ€™re still CHF 500 a month short of your AHV and pension scheme pensions. You can have this amount paid out automatically, whilst the rest of your assets continues to be invested and can benefit from market movements. In addition, individual withdrawals are possible at any time.

Important: Choose an amount that will ensure your capital lasts long enough, even in years when the stock market performs poorly.

Yes, with Finpension Invest you can invest up to 10 different portfolios set up, which are tailored to specific Savings goals such as retirement planning, childrenโ€™s education or buying a property.

Each portfolio is assigned a own investment strategy tailored to your investment horizon, your own savings plan and your own IBAN. You can name the portfolios whatever you like, for example ยซBuying a house 2030ยป. Couples can also set up a Joint portfolio lead.

Yes, Finpension is a reputable company. The finpension AG is a FINMA It is a licensed investment firm and is directly supervised by the Swiss Financial Market Supervisory Authority. The company manages over CHF 6 billion on behalf of more than 75,000 clients (as at August 2026) and has been in the black since 2019.

Your money is doubly protected:

  • Securities: Legally, your ETFs and funds belong to you and are held separately from Finpensionโ€™s assets. In the event of Finpensionโ€™s insolvency, they do not form part of the insolvency estate.
  • Cash: Uninvested funds are protected by the Swiss Deposit protection covered up to CHF 100,000.

Yes. With Finpension Invest, you can open a Children's portfolio open, already from CHF 1 and with a savings plan. The portfolio is running at your name, you simply name it after your child, for example ยซLucaโ€™s savings portfolioยป. That way, you retain full control over when and how you hand over the money later on.

Thanks to an investment horizon that is often 18 years or more, a high equity allocation. You can find more providers in our Child account comparison.

24 responses
  1. Dear Eric,
    Iโ€™m retiring next year and will be taking my 2nd pillar pension as a lump sum (3 million). Would investing in Finpension Invest be a good option? Or, given this amount, would you recommend a personal, private financial adviser? Or would another robo-adviser, such as Selma, be a better option?
    Many thanks for your feedback. Best regards, Jรถrg

    1. Dear Jรถrg
      Congratulations on your upcoming retirement and that fantastic pension payout!
      Finpension Invest is, of course, a robo-advisor (like True Wealth, Selma and the like)โ€ฆ Whatโ€™s best for you depends on a whole host of factors, so I canโ€™t really say off the top of my head.
      In any case, thereโ€™s a lot of money at stake, so the decision should be carefully considered.
      Financial planning can quickly pay off here; if anything, the FinanzFahrplan (in german) an exciting option for you.

      If you have any specific questions, please feel free to send me an email!
      LG
      Eric

  2. Hi, Eric,
    Thanks for the summary.
    I did the KYC with Saxo in March. But although I had set up a savings plan, they never invested. Support enquiries were never answered either. That's why I'm now moving and looking for a (now) simpler alternative.

    You write in the cost comparison above at True Wealth: 0.53-0.72%. TW itself advertises with 0.25% - 0.50% and possibly external production costs of 0.13%. How do you arrive at your above estimate?
    Thanks and regards, Danny

    1. Hello Danny,
      that always depends on the products used. TW has also recently reduced the costs - the article update is already in progress and will soon be live!
      The easiest way to compare Robo comparison.

  3. Ciao Eric

    WowWowWow, mega as always! Thank you very much!

    I am with TW and basically very satisfied, but for the children's custody account I came across the joint custody account of finpension invest.

    Do you know how it is with the tax return? I understand that both receive an e-tax statement for the joint custody account. Is the allocation there already 50/50% or do you have to make the positions and everything yourself? That would probably make an e-tax statement with 100% on it manual work again.
    Thanks a lot!

    1. Thank you very much, that makes me very happy!

      In the joint portfolio of finpension Invest, both persons receive
      each have their own e-tax statement in the document area. In the tax
      declaration, each person then declares their individual share.

      For married couples, the effort involved is minimal because you will be working together anyway.
      are predisposed.

  4. Hi Eric

    Wow. Very helpful. I've only just discovered your site.

    I am looking for a favourable children's portfolio without having to deal with individual stock selection. Finpension Invest would probably be a good solution, as investments in private markets are also possible. Very exciting.

    True Wealth is too high for the kids with 8,500 starting capital. I see TW as very attractive for a 3a solution with 100% equity exposure. That's probably pretty unbeatable, or do you see any disadvantages here (apart from the fact that you can only define 1 strategy for all 3a accounts with True Wealth)?

    What would you favour for building a larger ETF portfolio (up to 100k)? The idea would be to diversify broadly with low fees, automatic investment via a savings plan and automatic reinvestment.

    Thank you for all your information. Very appealing and helpful.

    Kind regards
    Renรฉ

    1. Thank you for your great feedback, Renรฉ!

      If you are weighing up these providers, you are already in the ยซelite classยป. The fees differ only minimally and should of course continue to be compared ... but I would then focus primarily on your personal preferences.
      For example, the minimum volume, how easy the tax return is made (keyword eTax statement) and, for example, whether you are already with one provider and would like to add another (both have advantages: less provider overhead vs. clear separation) ...

      So there is no general recommendation, but hopefully this will help you to find the right one for you. you make the right choice ๐Ÿ™‚

      LG Eric

  5. Hello Eric
    Firstly, thank you for your blog and the helpful information!
    I am planning a one-off investment of approximately CHF 150,000 in the near future. The idea is to invest in a World or ACWI ETF. Either Xtrackers MSCI World UCITS ETF 1C (IE00BJ0KDQ92) or SPDR MSCI All Country World UCITS ETF (IE00B44Z5B48), both of which would be available via Saxo Bank in CHF on the Six, both have a TER of 0.12%. The second option would be with Finpension Invest (we already have our 3a deposit there) in the Global 100% ETF fund, which would cost 0.49%. Based on this information, it is clear to me which option would be preferable. However, when I look at the past performance of these three products over the last five years, the picture looks very different. I am aware that future value developments cannot be predicted based on past performance. But if my information is correct, the Xtracker World in CHF made around 55%, the SPDR ACWI in CHF around 60% and the Finpension 65%. This means that Finpension would still be considerably more profitable despite higher recurring costs.
    What do you think? Thank you for your feedback.

    Kind regards, Marco

    1. Hello Marco

      Thank you very much for your positive feedback, I am very pleased ๐Ÿ™‚

      Regarding your question: You correctly mentioned that the future can never be deduced from the past. Even five years is almost too short a time frame for a forecast; I always try to look back at time series of 15โ€“30 years, if available.
      That's why I would take a different perspective; what does a digital asset manager do for you and why do you think you can beat its performance?.
      For many providers, cost is the decisive factor. However, with a provider as inexpensive as Finpension, this argument hardly counts anymore.

      Saxo vs. Finpension is very exciting in terms of costs, because both are extremely inexpensive โ€“ even if they offer completely different solutions. In this ยซduelยป, I would rather ask what you want to do yourself and what you don't. Digital asset managers not only aim to achieve maximum performance, but also try to keep volatility within limits, offer you tax-optimised investments and reduce the effort involved to an absolute minimum. If that suits you, you're definitely in good hands here.

      We will then be able to evaluate which strategy delivered the best performance in 10 years' time ๐Ÿ™‚

      1. Hello Eric
        Thank you for your feedback. I will take the viewpoint and perspective you mentioned into account in my considerations and decision.
        Kind regards, Marco

  6. Hi, Eric,

    Thanks to the numerous optimisations, according to Finpension, up to 1 % additional return can be achieved annually - enough to fully compensate for the fees. For a core-satellite portfolio in particular, the question arises as to which solution is more suitable in the long term. Because with a traditional broker with, for example, 6 ETFs, manual rebalancing and no fractional shares, the effort involved can quickly increase - both in terms of time and operationally. How do you see it?

    Best regards

    Marc

    1. Hello Marc,
      Whether it really is 1% and what the net return looks like in the long term remains to be seen. I am very enthusiastic about the solution and am currently running a test. Accordingly, I will keep updating this post with my results and findings ๐Ÿ™‚

  7. Hello Eric
    What does "Furthermore, Finpension Invest is not suitable if you are building up a large portfolio..." mean? . Respectively, from what amount do you consider a portfolio to be a large portfolio?

    Kind regards
    Sandro

    1. Hello, Sandro,
      That depends very much on what the alternative would be. A rough house number, which applies to many robo advisors in this price segment, is around CHF 70t. Depending on the strategy and frequency of investing, a favourable broker cheaper.

      However, if you generally want to save yourself the effort, you can also rely on a low-cost robo advisor such as Finpension Invest in the long term with a clear conscience.

  8. Thanks for the great contribution and the explanation! Registration worked great. Thanks for the code and the credit! Deposit credited directly the next day and fee credit noted transparently.
    If you would still like to join this year and benefit from a โ‚ฌ25 fee credit together!

    Timo ๐Ÿ™‚

  9. Godo evening,

    I would like to start using Finpension Invest (I already have 3a pillar with a quality fund) and I'd like to know your opinon on the fund Finpension equity 100. This idea is to invest for a child for at least 18 years, around 200 CHF every month.

    Is this a solid fund? I mean is it similar to a world etf with decent expected growth of 7%p.a.? Or would you choose a particular etf?

    If compared to neon bank invest in etf FTSE world is Finpension expensive?

    Thank you for your time

    1. Hi Nic,

      Finpension Invest is a solid choice, especially as a securities custodian-they optimise fees, including currency exchanges, to keep costs low. The Equity 100 fund is diversified similarly to a world ETF and fits a long-term growth strategy like yours. While no returns are guaranteed, it targets around 7% annually, in line with market expectations for broad equity exposure.

      1. Hi Eric, thank you for your answer.

        What do you think is more expensive in the long term, let's say 20 years?

        FTSE all world, Neon invest
        or
        Finpension global 100?

        I understood that Finpension is doing a great job in optimazing taxes, but the management fees are 0.39, then you have to TER 0.08, in this way is 0.47% every year, while Neon is 0.

        1. Hi Nic,
          Finpension Invest is a robo-advisor offering tax-efficient investing with optimised fees and a well-diversified portfolio, ideal for long-term growth. The fee includes portfolio management and other services.
          Neon Invest is a brokerage-only service, meaning you handle all investments yourself. While an investment through Neon can be trading-fee-free, there is more work for you to do.

          So this comparison is truly apples and oranges ๐Ÿ™‚

  10. Hello Eric

    Thank you for your assessment of Finpension! You write "...Finpension Invest is not suitable if you are building up a large portfolio"
    When is a portfolio considered large?

    Merci and keep it up!

    1. Hello Galliker,
      Thank you very much for your positive feedback and your question!
      Finpension Invest is also suitable for large portfolios - I wrote in the article: ... if you want to keep the fees very low.
      (just to be clear once again ๐Ÿ™‚ )

      If we were talking purely about fees and wanted to optimise them to the maximum: Let's say our ETF portfolio has an average TER of 0.25% per year. If a robo advisor charges 0.40% per year, in this very simplified example 0.15% per year would be free for portfolio management.
      As a comparison: at Swissquote, custody account management costs CHF 80 per year, which would mean that the "break-even" point would be reached at a custody account volume of CHF 53,333. After that, a flat custody account fee would be more favourable than a percentage fee on the assets under management.

      However, this calculation does not take many factors into account. Probably the most important: the "labour hours" required to set up and maintain the depot yourself.
      Hopefully this simplified view will still give you an idea.

      This is suitable for many beginners and can pay off: Gaining initial experience comfortably with a robo advisor such as Finpension Invest and if the custody account becomes very large and the fees need to be reduced, you can still switch to a broker (and invest on your own).

  11. Hello Eric

    Thanks for your good blogs!
    Wouldn't it make sense to invest in short-dated CHF government bonds, so you wouldn't have to go interest rate hopping and also have a correlation advantage if these bonds are combined with equities?
    However, I have so far realised that these bonds are rather expensive. Approx. 0.8% of the amount at both Swissquote and Saxobank.
    Do you have a more elegant solution so that you don't have to go interest rate hopping? ๐Ÿ˜‰

    Kind regards Kili

    1. Hello Kili,
      Thank you for your question!
      Two requests: Can you please give a little more context to the question? And can you please post it directly to the appropriate post? I don't think it belongs to the Finpension investment solution here, does it?
      Thank you very much!

Write a comment

Your e-mail address will not be published. Required fields are marked with * marked.