A new digital Pillar 3a scheme has been in place since 19 October 2026. findependent charges 0.29 % per year, which is lower than finpension, VIAC and frankly. The difference is just one-tenth of a per cent. In our calculation example, this still amounts to around CHF 10,000 over 35 years.
We have analysed all 15 ‘funds of funds’ investment solutions. Our analysis shows that the 0.29 % figure does not apply to every strategy. And the real benefit lies not in the fee, but in the funds themselves.
Key points at a glance
- 0.29 % per year including fund fees. It’s cheaper than finpension, VIAC and frankly.
- Effectively 0.29 % only for 99 % shares. As with other providers, the strategies comprising 20 to 80 % shares include a property fund with additional costs. This brings the total to around 0.36 %.
- Special pension funds (IPF) for US and Japanese shares. You do not lose any withholding tax on their dividends. In the «Global» focus, this applies to 64 % of your portfolio.
- New, with no performance history of its own. The securities are held by ZKB and belong to the legally separate pension fund.
- Using the code «schwiizer3a» The first CHF 2,000 are permanently exempt from management and custody fees.
findependent 3a at a glance
You may be familiar with findependent as an app for investing your personal savings; you can find our findependent review here. According to their own figures, they have over 30,000 customers. For Pillar 3a, findependent has set up its own pension foundation, based in Aarau. The funds are provided by Swisscanto and are held in custody by the Zürcher Kantonalbank.
| Feature | findependent 3a |
|---|---|
| Fee | 0.29 % per year, including fund costs (TER) |
| Fund | Swisscanto index funds, classes excluding TER |
| Share quota | 20 % to 99 % |
| Investment focus | Standard, Switzerland or Global |
| Ready-made solutions | 5 risk levels × 3 focus areas = 15 variants |
| Own solution | comprising 33 index funds |
| portfolios | up to 5, for staggered collection |
| Minimum amount | CHF 1 |
| Trade | weekly, usually on Tuesdays |
| Proportion of cash | 1 % |
| Custodian bank | Zurich Cantonal Bank |
| 3a account | No, just securities |
| Freedom of movement | planned |
findependent fees explained in plain language
The 0.29 % includes almost everything: administration, custody, the foundation, transactions, strategy changes and deposits. The fund costs are also included, as findependent uses fund classes with a TER of 0.00 %.
This eliminates two costs that you’ll be familiar with from ETF solutions:
- No transfer fees: The funds are traded in Swiss francs.
- No stamp duty or stock exchange levies: They are index funds, not ETFs.
You do not pay any visible fees when buying or selling. As with all providers offering Swisscanto index funds, the issue price is slightly higher than the fund’s net asset value. This means that your trading costs are not borne by the other investors.
However, the currency risk remains. If a fund invests in US shares, its value fluctuates in line with the dollar, even if you buy it in Swiss francs.
For 50,000 Swiss francs, you pay around CHF 145 per year. With finpension, at 0.39 %, it would be around CHF 195; with VIAC, at up to 0.44 %, it would be around CHF 220.
There is one exception: the property allocation. All strategies comprising between 20 and 80 % shares include 10 % Swiss property holdings, invested via the «Swisscanto Index Real Estate Fund Switzerland indirect». The fund itself has a TER of 0.00 %. However, it invests in listed Swiss property funds, which have their own ongoing costs. According to the fund’s key information document, these currently stand at 0.71 %. Based on 10 % of the portfolio, this amounts to around 0.07 % in additional costs.
For 99 % shares, you pay 0.29 %. In strategies involving 20 to 80 % shares, the figure is around 0.36 %.
findependent clearly states this and has confirmed it to us upon enquiry. To be fair: other digital 3a providers also use this or a similar property fund, such as finpension and VIAC, with a 4 to 5 % share. There, too, around 0.03 to 0.05 % is added, which is only mentioned in a footnote. findependent therefore remains cheaper than finpension. The difference is that findependent invests the entire 10 % property portfolio in Switzerland, whilst finpension and VIAC invest part of it abroad.
What a 0.1 % fee amounts to over 35 years
A sample calculation: You pay in CHF 6,000 per year for 35 years. The investments yield 4.5 % per year before fees. The return is the same across all providers; only the fees differ.
| Annual fee | Balance after 35 years | Difference from 0.29 % |
|---|---|---|
| 0.29 % (fund-dependent, 99 % shares) | around CHF 480,000 | Basic |
| 0.39 % (finpension) | around CHF 470,000 | around CHF 10,000 less |
| 0.44 % (VIAC, maximum) | around CHF 465,000 | around CHF 15,000 less |
| 1.10 % (example of an expensive bank fund) | around CHF 406,000 | around CHF 74,000 less |
The figures show two things. Switching from a bank-managed fund to a digital 3a account makes a big difference. Switching between digital providers makes significantly less of a difference. Ten thousand francs is, nevertheless, no rounding error.
But the fee isn’t the only thing. The calculation assumes the same return across all providers. In reality, the strategy usually matters more: the equity allocation, the proportion invested in Switzerland, the currencies involved, and which funds are included. Even a difference of 0.5 % in annual return, either way, more than offsets any difference in fees between digital providers several times over. First choose the strategy that suits you, and only then select the cheapest provider for it.
Charges for collection and special cases
| Case | Costs |
|---|---|
| Deposit, change of strategy | free of charge |
| Payment upon retirement | free of charge |
| Transfer to another pension scheme | free of charge |
| Early withdrawal for home ownership (WEF) | CHF 500 per case |
| Pledge | CHF 500 per case |
| Benefits when moving abroad | CHF 750 per case |
| Self-employment allowance | CHF 750 per case |
| Extraordinary expenses | CHF 200 per hour or part thereof |
If you’re planning to make a WEF early withdrawal in the next few years, make sure to factor in the CHF 500. With frankly, for example, WEF early withdrawals are free of charge.
The 15 investment solutions in detail
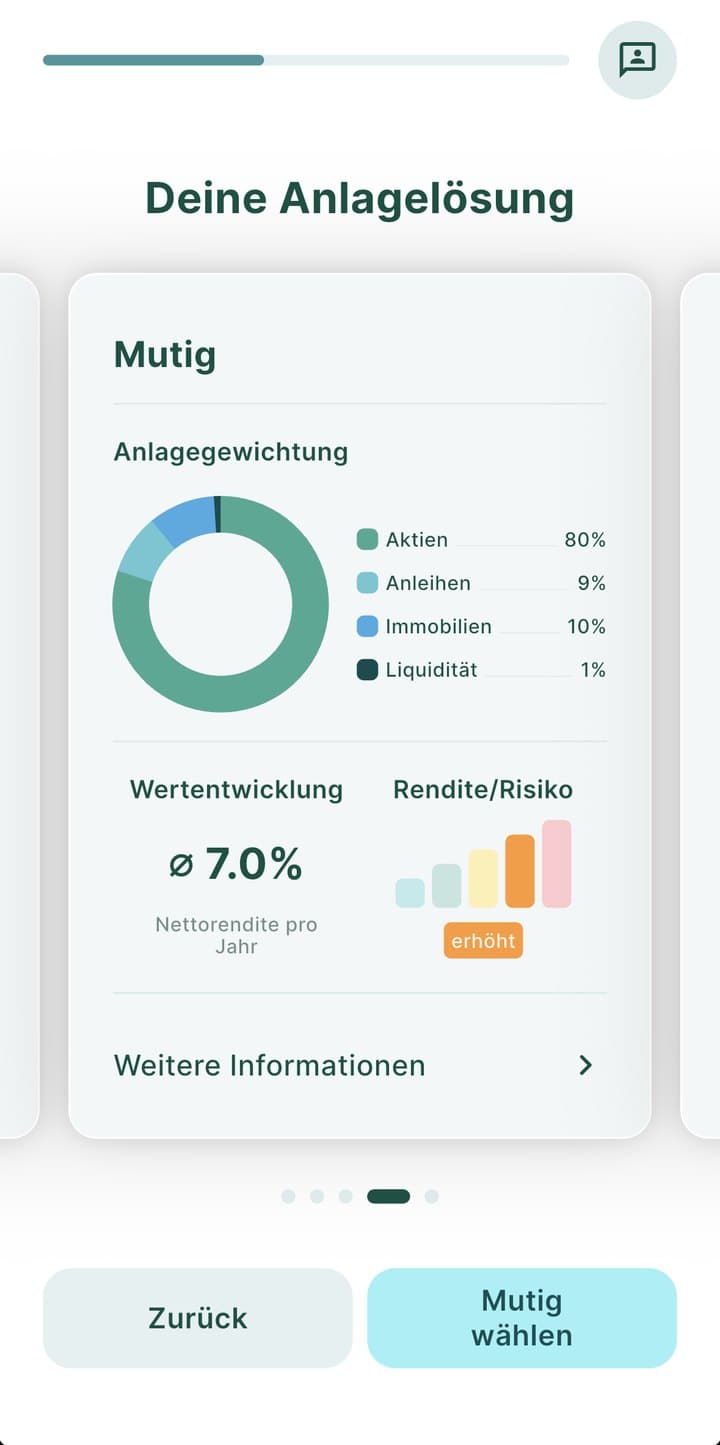
You choose one of five risk levels: Cautious (20 % shares), Prudent (40 %), Balanced (60 %), Bold (80 %) or Risk-taking (99 %). In addition, you choose one of three investment focuses. This determines what proportion of the equity allocation is invested in Switzerland.
| Risk level | Shares | Bonds | Property in Switzerland | Gold | Costs per year |
|---|---|---|---|---|---|
| Careful | 20 % | 59 % | 10 % | 10 % | around 0.36 % |
| Thoughtful | 40 % | 44 % | 10 % | 5 % | around 0.36 % |
| Balanced | 60 % | 29 % | 10 % | 0 % | around 0.36 % |
| Brave | 80 % | 9 % | 10 % | 0 % | around 0.36 % |
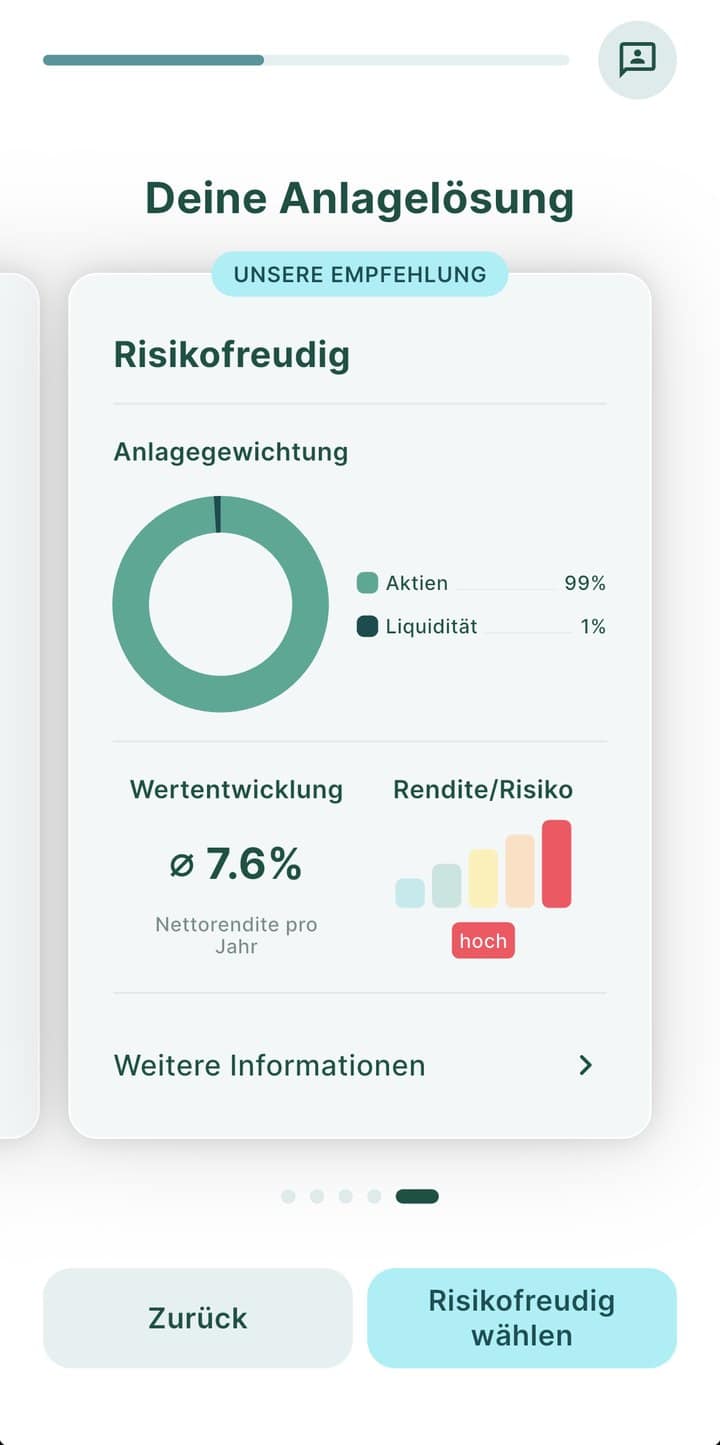
| Willing to take risks | 99 % | 0 % | 0 % | 0 % | 0.29 % |
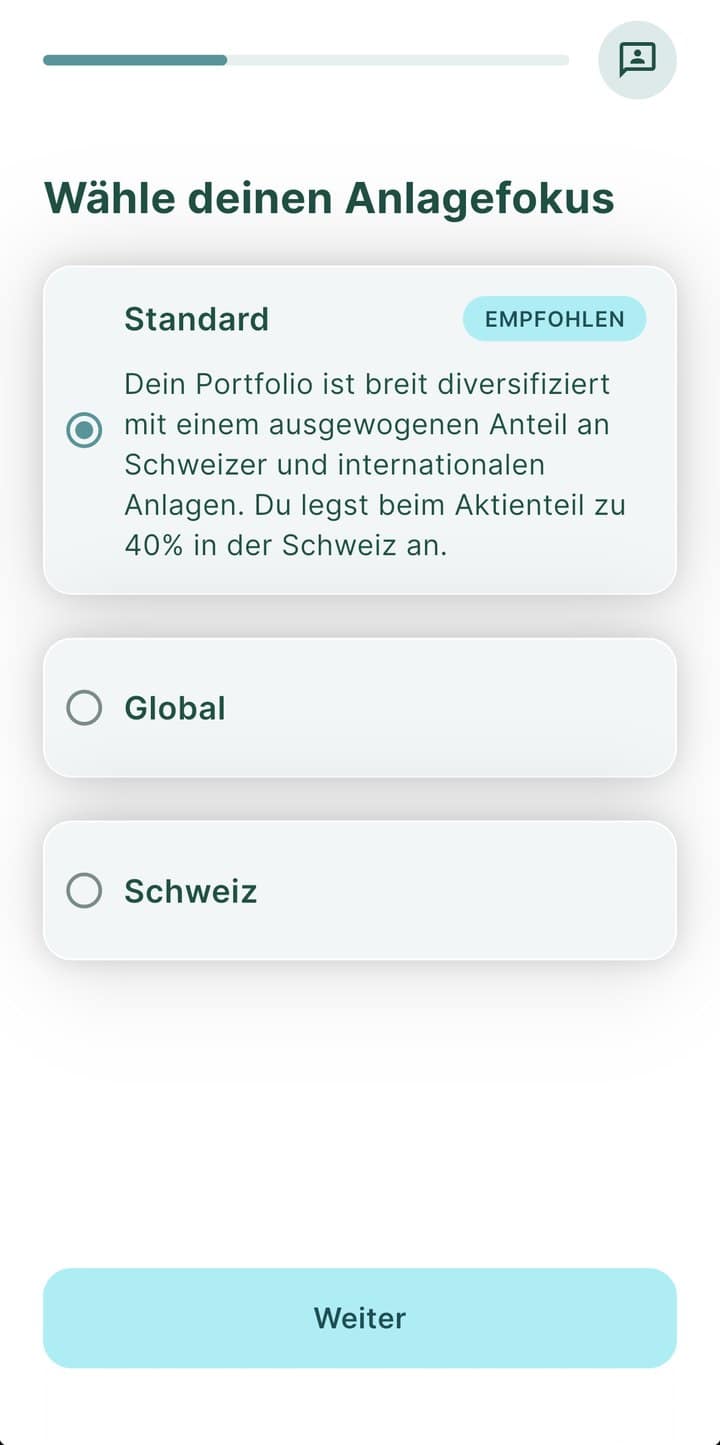
- Standard: 40 % of shares in Switzerland
- Switzerland: 80 % of shares in Switzerland; bonds in Swiss francs only
- Global: 10 % of shares in Switzerland
40 % Switzerland in Focus: «Standard» is deliberately a lot. This has its advantages when investing in Swiss francs: less currency risk and companies you’re familiar with. On the other hand, you’re more exposed to a small market with a few very large stocks. If you want to invest more broadly on an international scale, go for «Global» with 10 % Switzerland. How much Swiss exposure suits you is a question of strategy, not of right or wrong.
This is what the option comprising 99 % shares looks like across the three focus areas. The figures are taken from the fund list that Findependent sent us before the launch.
| Region (99 % shares) | Standard | Global | Switzerland |
|---|---|---|---|
| Switzerland, large companies | 29.7 % | 7.4 % | 59.4 % |
| Switzerland, small and medium-sized enterprises | 9.9 % | 2.5 % | 19.8 % |
| USA (IPF) | 39.7 % | 59.6 % | 13.2 % |
| Europe without Switzerland | 9.2 % | 13.7 % | 3.1 % |
| Japan (IPF) | 3.1 % | 4.7 % | 1.0 % |
| Emerging markets | 7.4 % | 11.1 % | 2.5 % |
| Cash | 1 % | 1 % | 1 % |
| Proportion of IPF funds | 42.8 % | 64.3 % | 14.2 % |
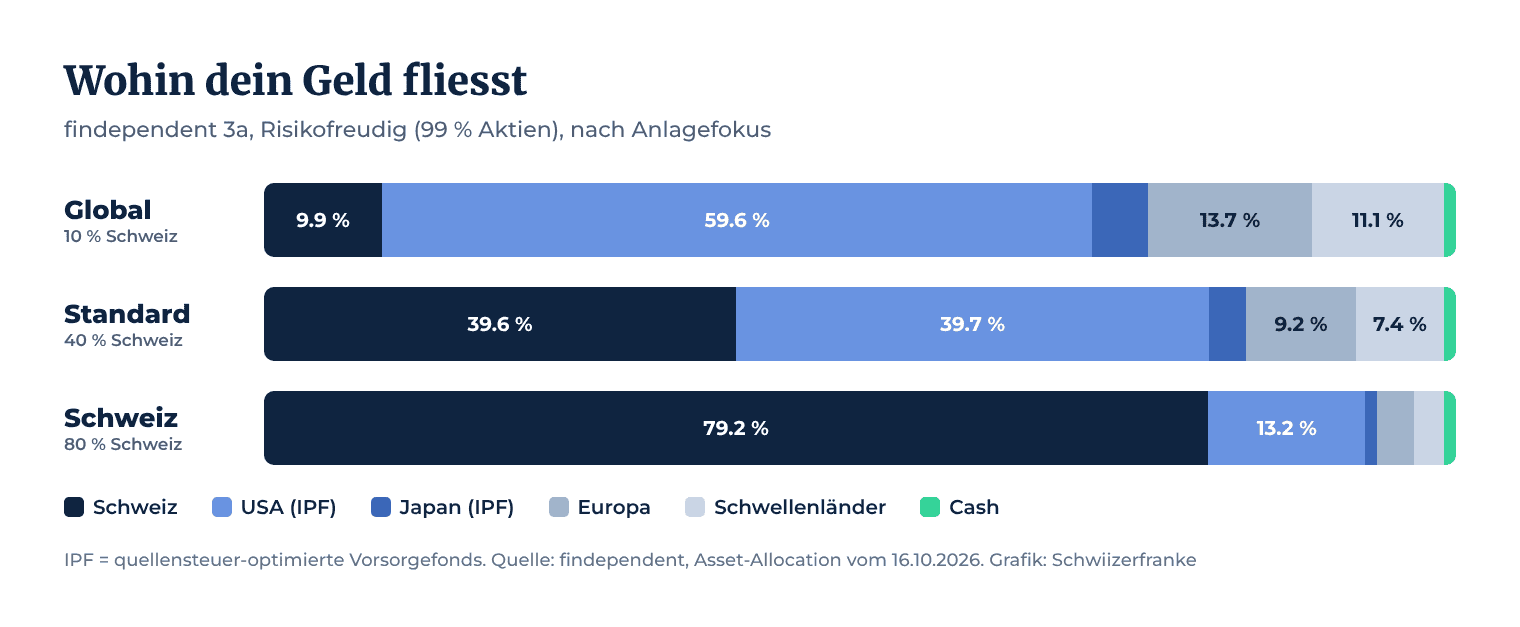
The Swiss component comprises large, small and medium-sized companies in a ratio of 3 to 1. It is therefore more broadly based than the SMI, which comprises its 20 largest companies.
The bonds are predominantly Swiss franc-denominated. In the Standard and Global portfolios, alongside 40 to 80 % equities, there are also 2 to 4 % emerging market bonds denominated in hard currencies such as the US dollar.
Most of the equity funds and several of the bond funds in the ready-made solutions form part of Swisscanto’s «Responsible» range. They take sustainability criteria into account and exclude certain companies. The TER remains at 0.00 %. Anyone who does not wish to do so can also find funds without this filter within their own investment solution.
Tip: If your 3a is a long-term investment, take a look at the «Risk-seeking» risk level. This is the only option where there are no properties with additional costs, and the 0.29 % applies in full. However, only invest money that you won’t need for a long time, and choose the equity allocation that suits your investment horizon.
IPF funds explained simply
When a US company pays a dividend, the US withholds a portion as withholding tax. With many standard Swiss equity funds, 15 % of each US dividend is thus retained. This money is no longer working for you. Special pension funds can help you avoid this deduction.
An exception applies to pension funds and 3a foundations. Under the double taxation agreement between Switzerland and the US, they have paid no withholding tax at all on US dividends since 2020. To enable them to take advantage of this, Swisscanto has launched special funds that may only be purchased by pension funds. These are the IPF funds; «IPF» stands for «Institutional Pension Fund». A similar rule applies to Japan.
What the IPF advantage offers
A simple calculation shows what this amounts to. US shares currently yield a dividend of around 1 to 1.5 % per year. 15 % of this amounts to roughly 0.15 to 0.2 %. An IPF fund can make up this much in annual returns on its US equity allocation, compared with a standard fund.
In our Pillar 3a comparison, we compared two Swisscanto funds tracking the same international index, one with IPF and one without. Over a period of one to ten years, the IPF version outperformed by around 0.3 to 0.4 % per year. These are historical figures for two funds; they are not a guarantee.
How much of this goes to findependent
The benefit applies only to the portion held in IPF funds. In the «Global» focus, this amounts to 64 % of the portfolio; in the «Standard» focus, 43 %; and in the «Switzerland» focus, just 14 %. In purely mathematical terms, this translates to a figure of 0.1 to 0.25 % per year for the «Global» focus, compared with a solution without IPF funds. This is an estimate, not a proven excess return.
Two points to bear in mind. In its ready-made solutions, findependent uses IPF funds for the USA and Japan. There are no dedicated IPF funds for Europe and emerging markets. They are therefore managed via standard fund classes, as is also the case with finpension, VIAC and frankly. And this advantage is not exclusive: finpension, VIAC and frankly also use institutional pension funds. findependent is thus catching up with the best providers, whilst charging lower fees.
A bespoke investment solution comprising 33 funds
Instead of a ready-made solution, you can put together your own portfolio from 33 index funds. There are also additional IPF funds for «World ex CH» and for small companies worldwide, each available with or without a sustainability filter. In addition, there are funds for Canada, the Pacific (excluding Japan), property in North America, Europe and Asia, as well as other bond funds.
There are two rules. Your equity allocation must not deviate by more than 10 percentage points from the result of the risk questionnaire. And each fund has a maximum weighting. If the questionnaire classifies you as «risk-tolerant», you are free to allocate your equities across the globe as you wish.
For most people, a ready-made solution is sufficient. Those who specifically want a global core portfolio comprising IPF funds and their own Swiss allocation will find that the 33 funds offer plenty of flexibility.
findependent vs. finpension, VIAC and frankly
| findpendent | finpension | VIAC | frankly | |
|---|---|---|---|---|
| Annual fee | 0.29 % | 0.39 to 0.42 % | up to around 0.44 % | 0.43 % |
| Max. Share quota | 99 % | 99 % | 99 % | 95 % |
| portfolios | 5 | 5 | 5 | 5 |
| Institutional pension funds | Yes, IPF for the USA and Japan | yes | predominantly | yes |
| Own performance history | New since 2026 | several years | several years | several years |
When it comes to fees, findependent is in the lead, most notably with 99 % shares. Where the equity allocation is lower, the lead is smaller because Findependent includes a higher proportion of Swiss property. The biggest difference is age: The other three providers have a track record spanning several years with actual figures; findependent is starting from scratch.
However, the fee alone isn’t the deciding factor. Providers also differ in terms of their strategy: how much of the portfolio is invested in Switzerland, whether sustainability filters are in place, whether a 3a account is available, and how much freedom you have to choose your own funds. Choose the provider whose strategy suits you best. If two are on a par, the lower fee is the deciding factor.
You can find full details of all providers in our Pillar 3a comparison and in the reviews of finpension 3a, VIAC and frankly.
How safe is your money?
Your 3a funds do not belong to Findependent, but to the «findependent 3a Pension Foundation». The foundation is legally separate from Findependent AG and is subject to BVG and foundation supervision by the Canton of Aargau. If Findependent AG goes into liquidation, your 3a balance will not form part of its estate. This does not protect against capital losses.
The securities are held in custody at Zürcher Kantonalbank and belong to the foundation, not the bank. They therefore remain unaffected in the event of a bank failure. The cash portion, amounting to around 1 %, is held at Hypothekarbank Lenzburg. In the event of a bank’s bankruptcy, pension savings are protected up to CHF 100,000 per person, in addition to the protection afforded to your private bank accounts. Findependent AG itself has held a licence from FINMA as a securities firm since February 2026.
It’s a different matter altogether. findependent is aiming for 20,000 3a customers by the end of 2027. Nobody can say at this stage whether the 0.29 % will remain unchanged in the long term. However, this applies to every provider, and switching to findependent is free of charge.
The weaknesses of findependent 3a
- No performance history of its own: Just estimates so far; no actual figures yet.
- Not a 3a account: Securities only. It is possible to open an account, but this is not planned.
- An early withdrawal from a WEF account costs CHF 500.
- Sustainability filter fixed in the ready-made solutions; without the filter, only with your own solution.
Code «schwiizer3a» and launch offer
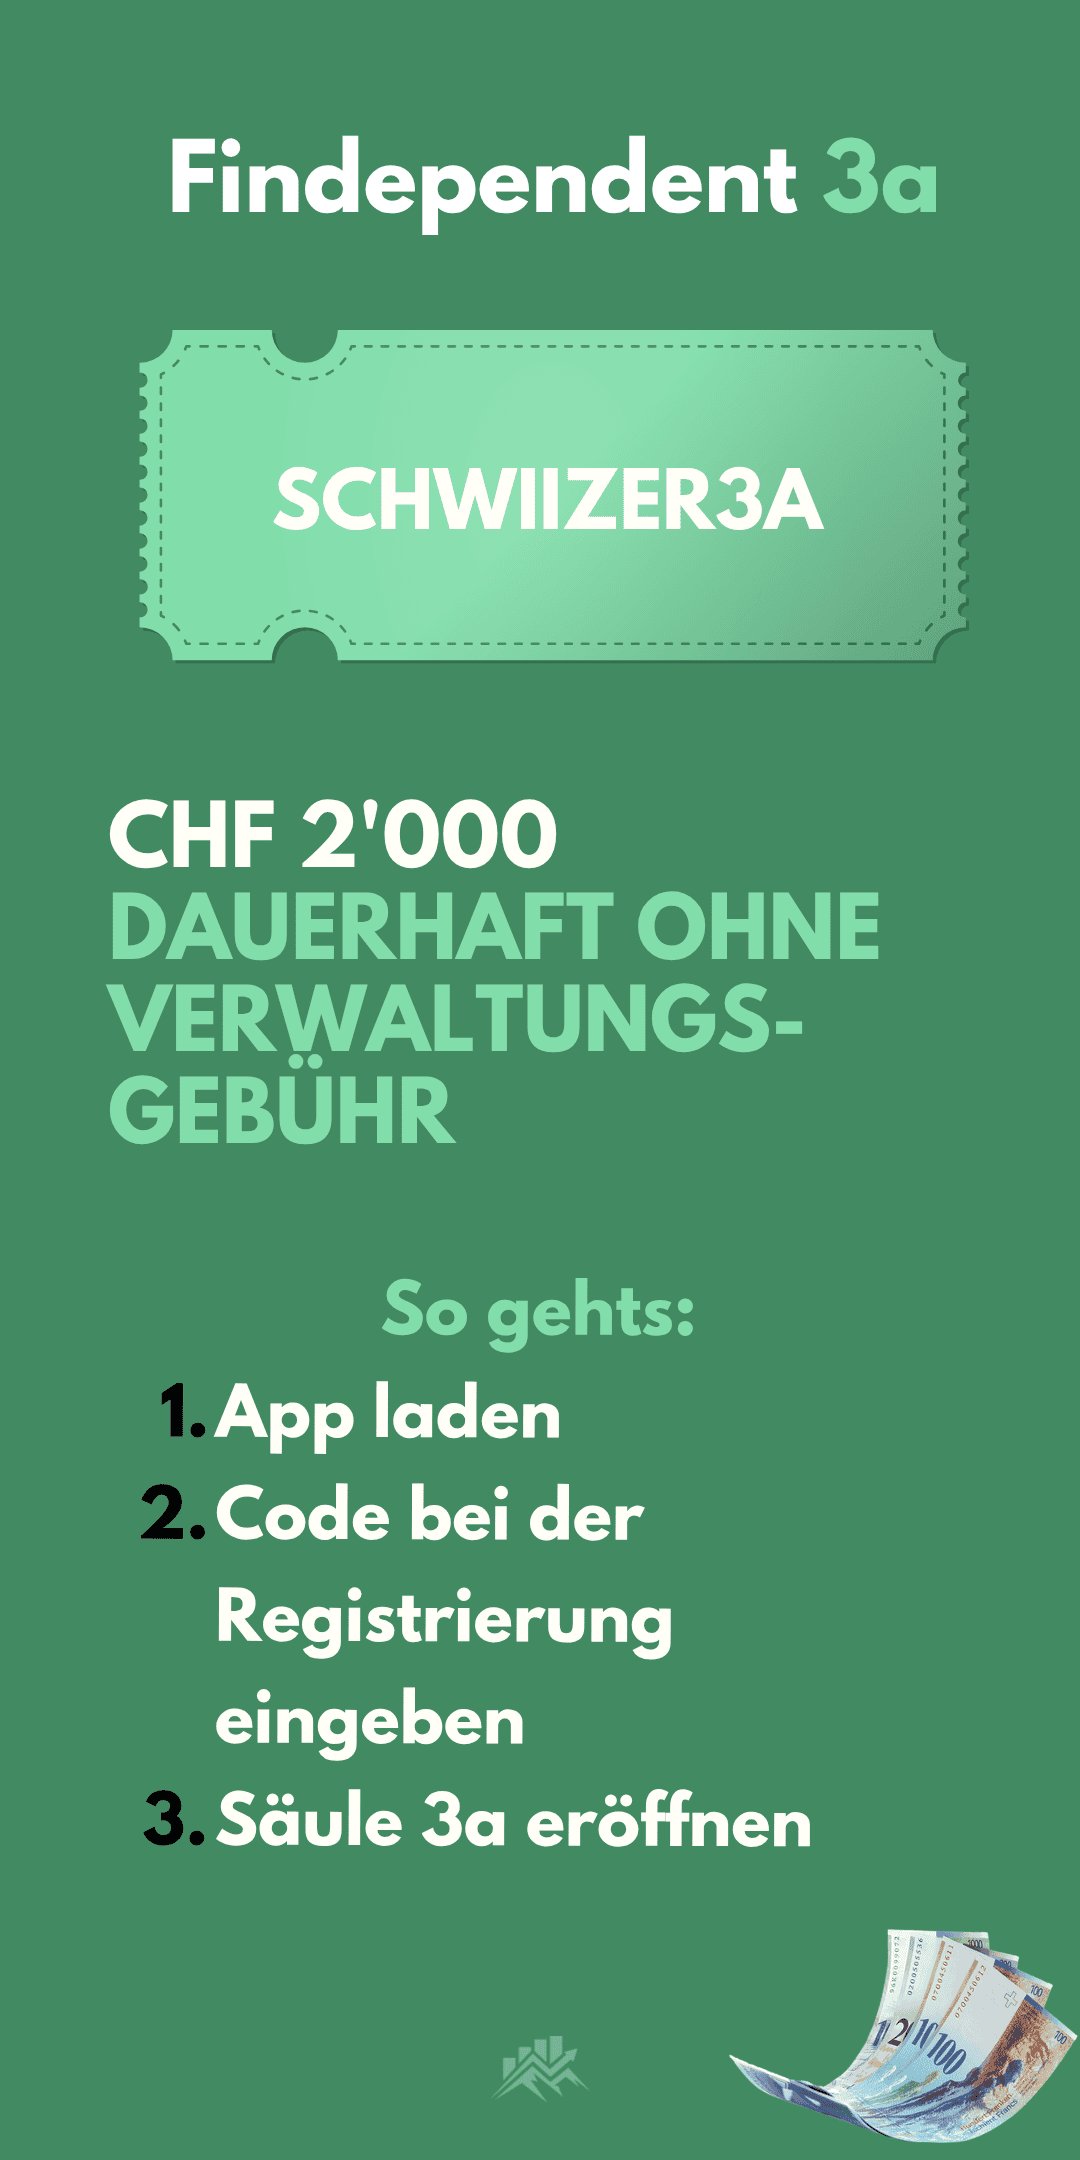
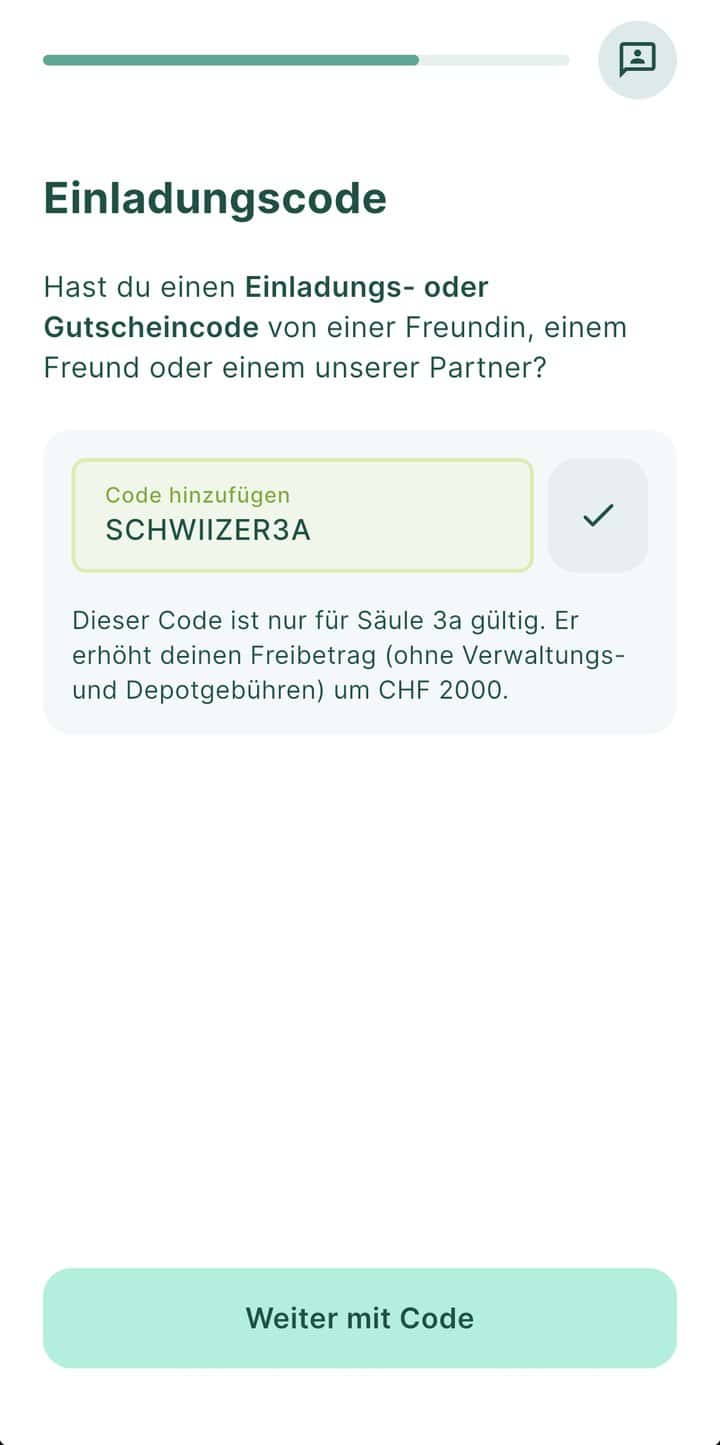
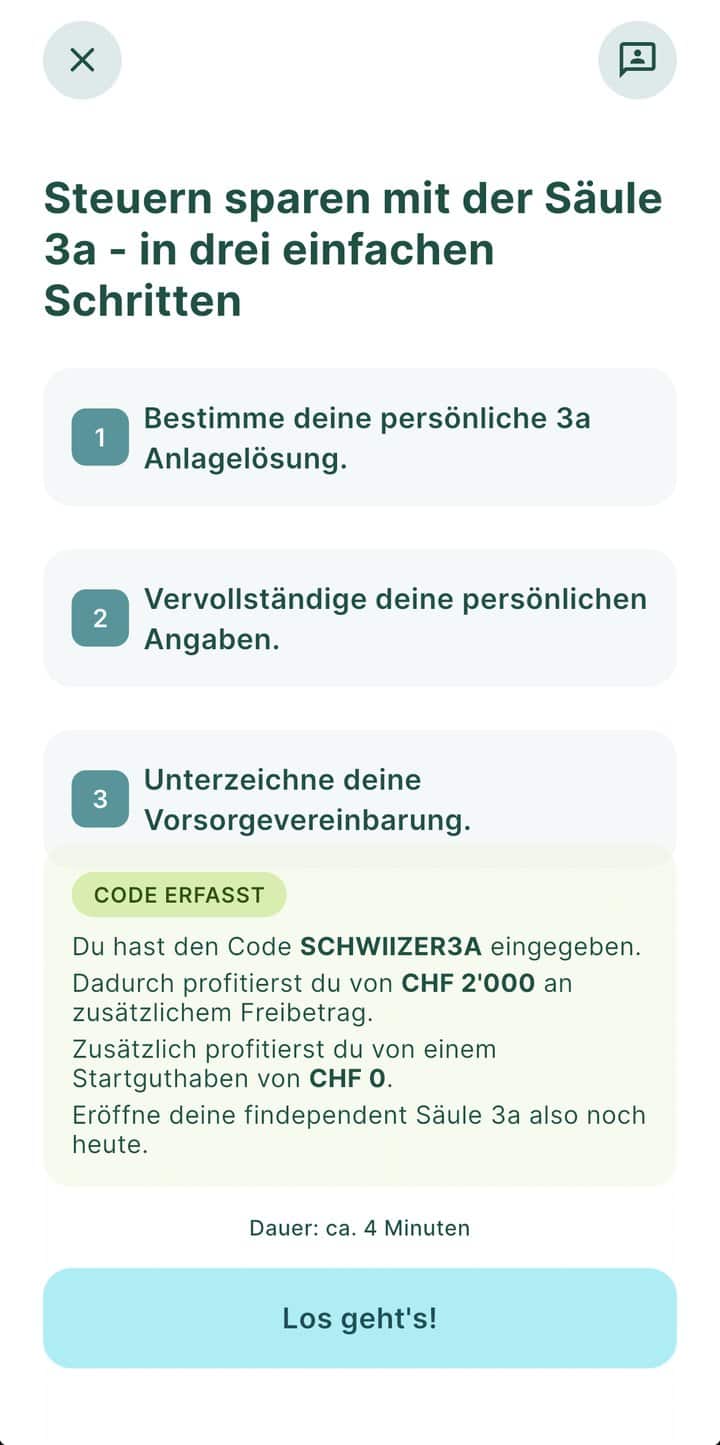
With the code «schwiizer3a», the first CHF 2,000 of your 3a balance is permanently exempt from management and custody fees. Without the code, there is no fee exemption for the 3a. You enter the code straight after downloading the app, immediately after setting your password. The app confirms it straight away and displays the fee-exempt amount again later in the 3a section.
- Only one code is valid per person, either for 3a or for Invest.
- If you are already a customer of findependent Invest, you can transfer your tax-free allowance to the 3a account, as per written confirmation from findependent.
- Transfer offer: Anyone who transfers their existing 3a assets to findependent by 28 February 2027 will not pay any management fees on their entire 3a portfolio until 30 June 2027. This also applies to existing customers.
You can find all the terms and conditions relating to the code, as well as a guide with screenshots, on our page for the findependent 3a voucher code.
Transparency: If you open an account via this link, Schwiizerfranke will receive a commission. You won’t pay anything extra for this; in fact, you’ll benefit from it. Our assessment in this article is independent of this.
Opening under trial
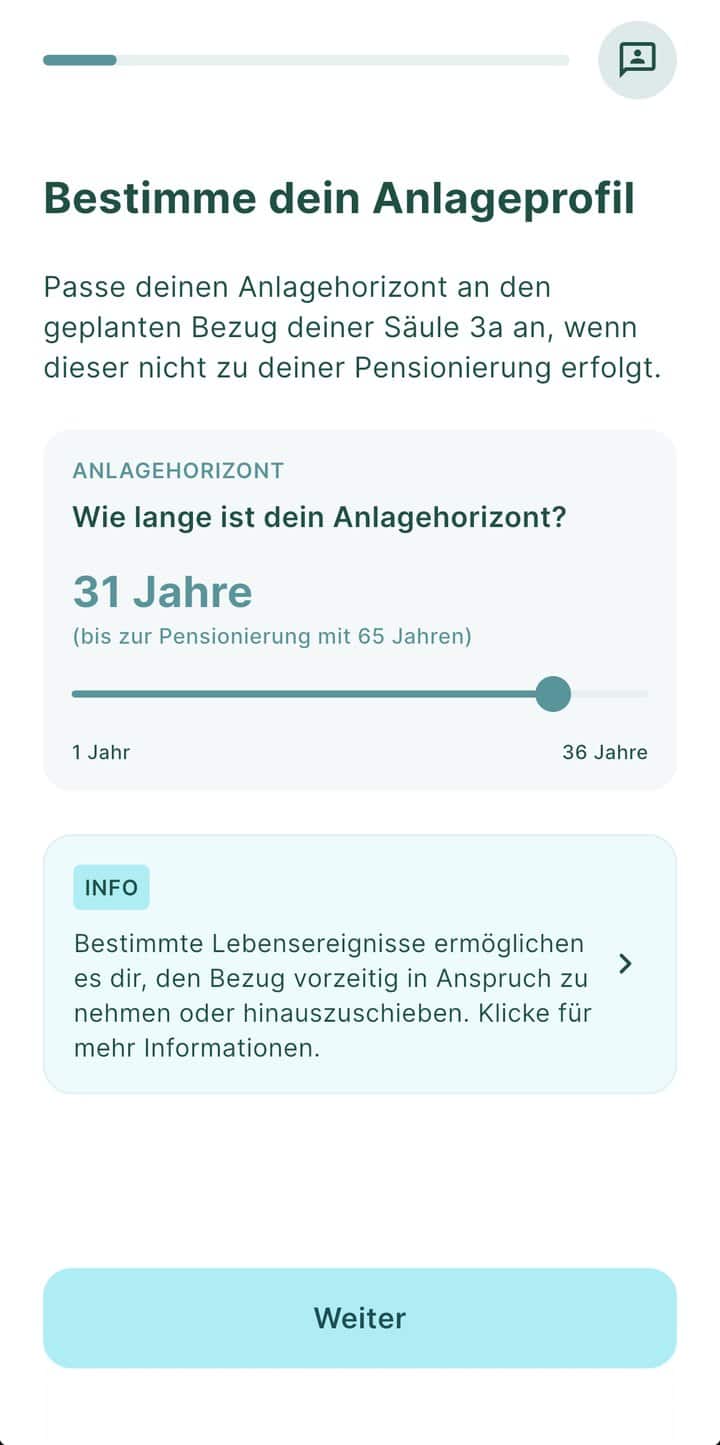
We opened the findependent 3a account ourselves via the app on 20 October 2026. The app estimates it takes around four minutes, and that’s about right. The onboarding process is very quick and intuitive; every step is self-explanatory.
- Download the app, set a password and enter the code «schwiizer3a» straight away.
- Set your investment horizon. The app suggests the number of years until retirement; you can adjust this.
- Select your investment focus and risk level.
- Fill in your personal details and sign the care plan digitally.
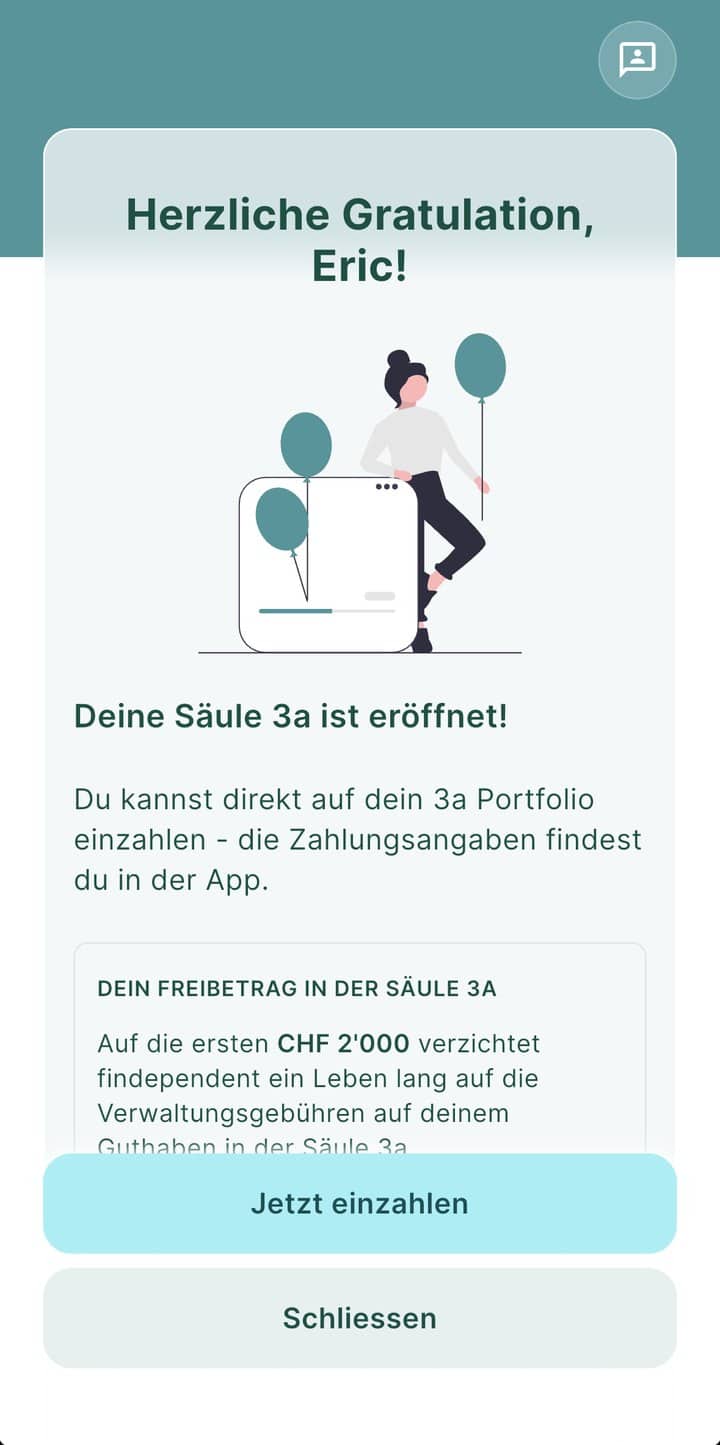
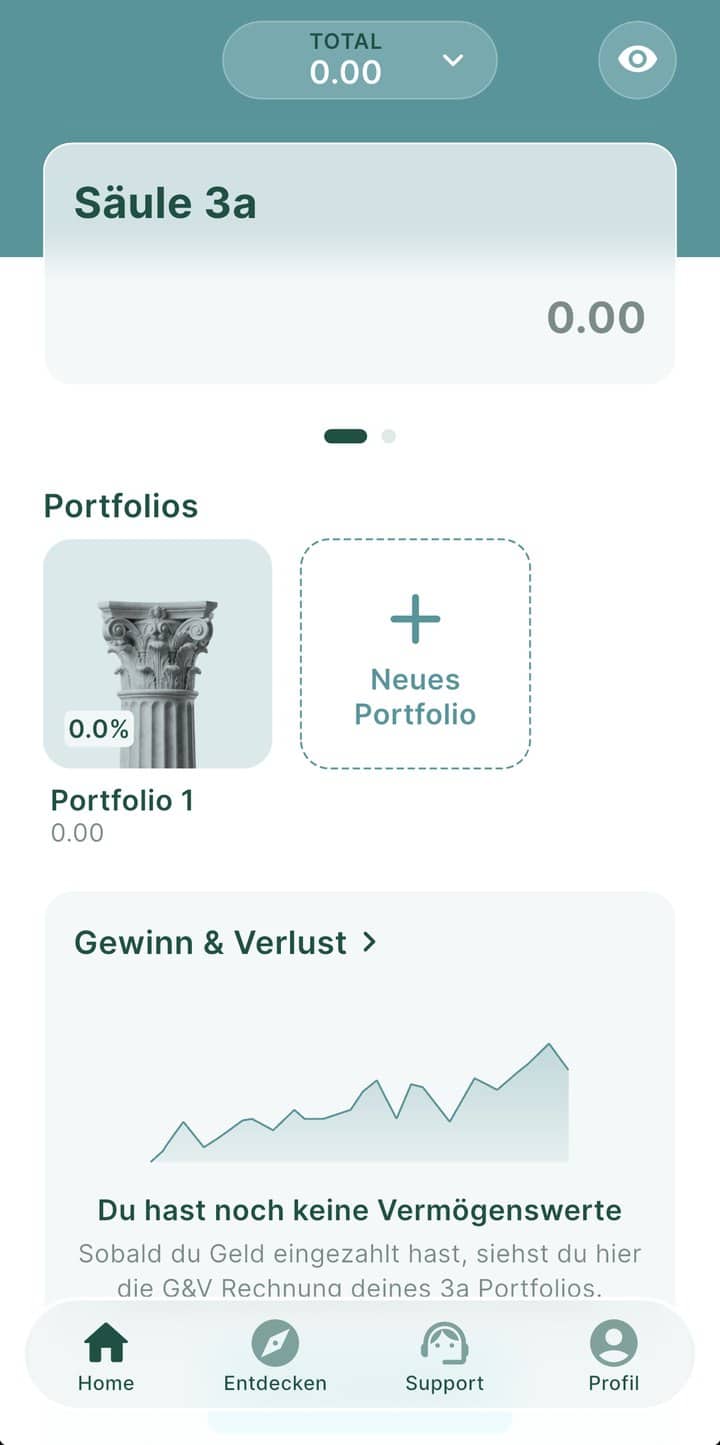
Video identification was not required. findependent deliberately keeps the onboarding process brief and only verifies identity when a withdrawal is requested, by asking for a copy of an ID or passport. Shortly after opening the account, I received confirmation by email, including the IBAN for making a deposit.
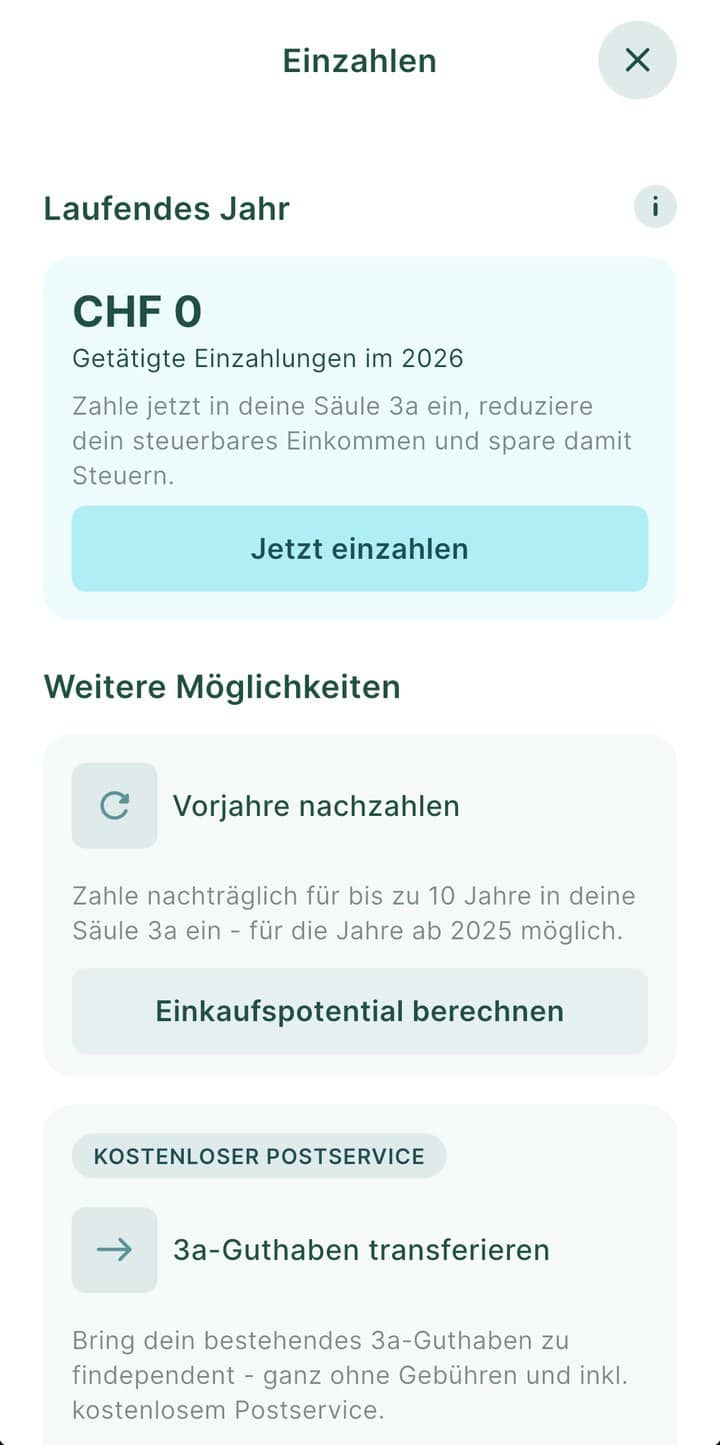
Under «Deposit», you’ll find three options:
- Current year: You pay via QR invoice.
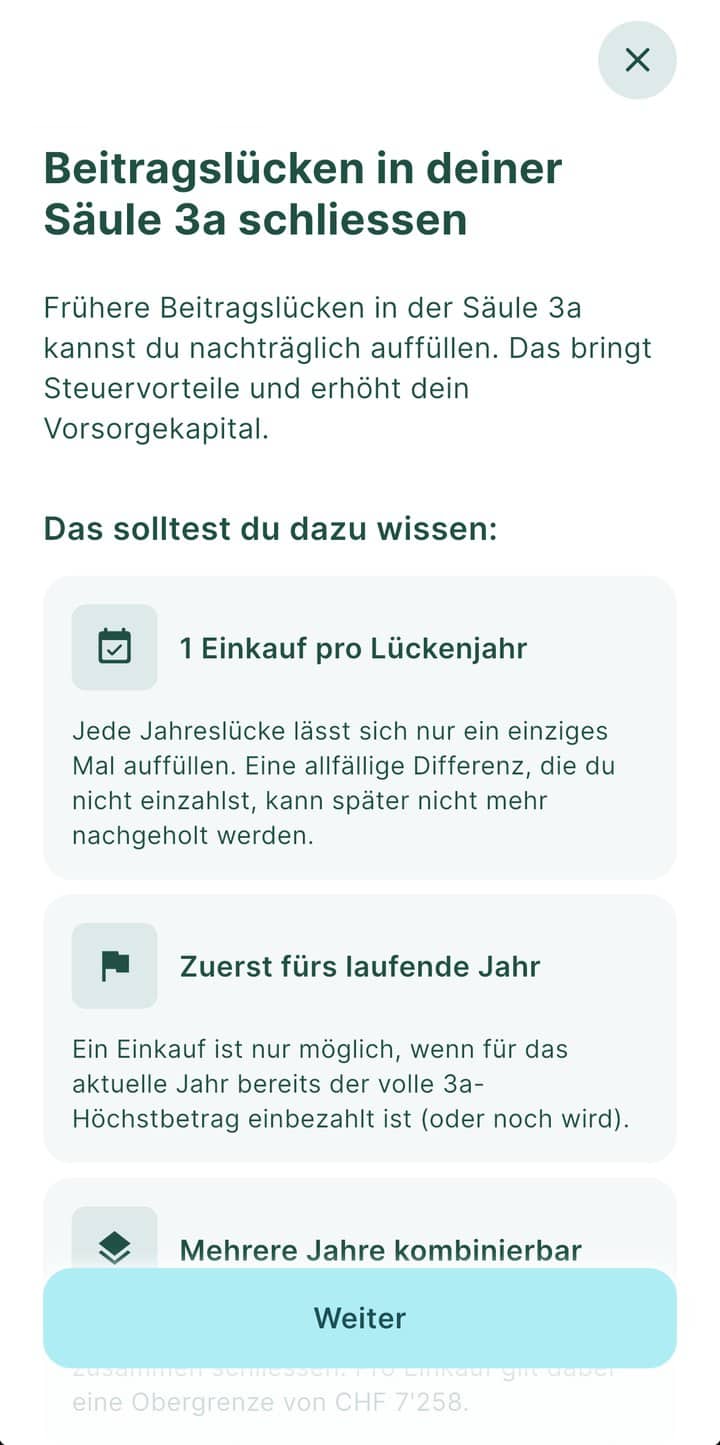
- Gaps from previous years: This is possible for gaps from 2025 onwards, and only if you have already paid in the full amount for the current year.
- Transfer: You are transferring your existing 3a savings.
The app calculates your potential for making additional contributions and explains the rules, such as the fact that each gap in your contribution history can only be filled once.
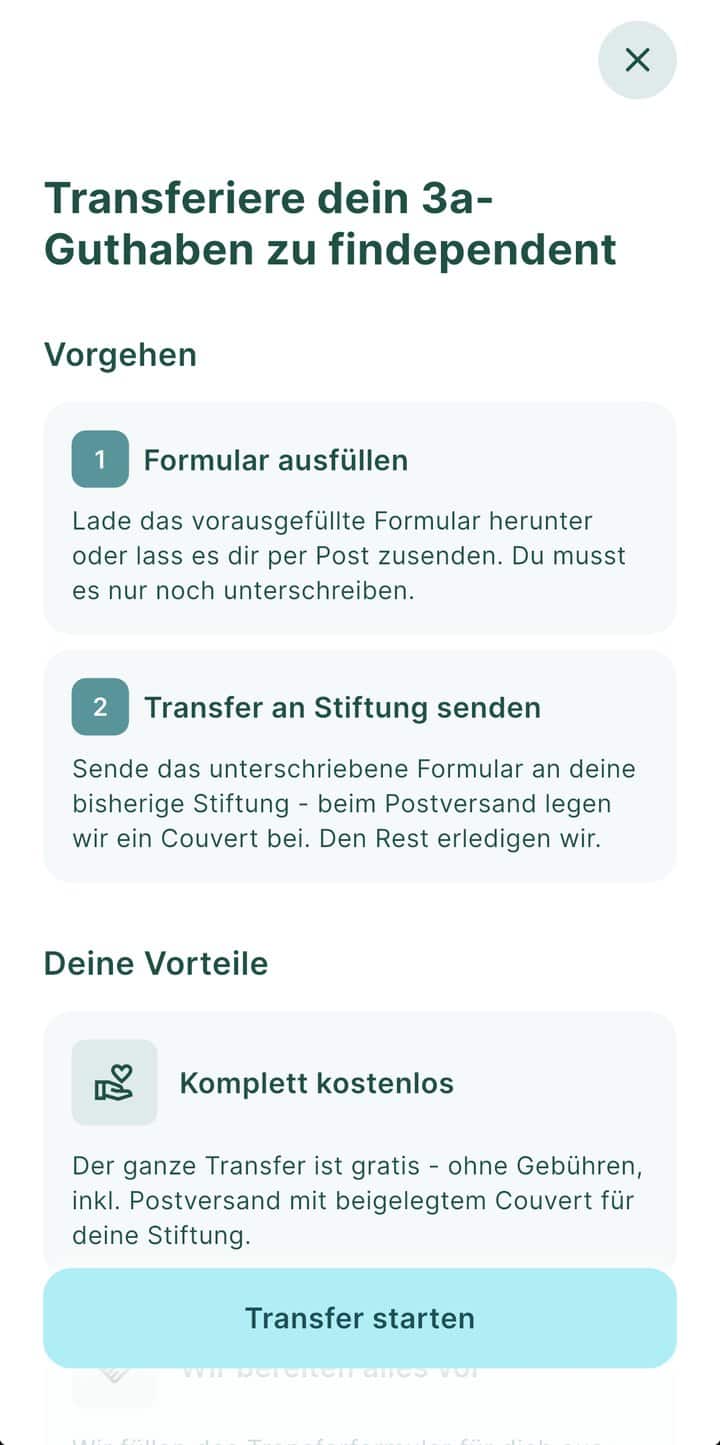
findependent will complete the transfer form for you. You can download it or have it sent to you by post, including an envelope addressed to your current foundation. All you need to do is sign it. findependent does not charge anything for the transfer. However, your current foundation may charge its own fees.
Deposits are invested on the next trading day, usually on a Tuesday. To ensure that a deposit counts towards the current tax year, findependent recommends making the deposit by 29 December at the latest. The key factor is that the money is credited before the end of the year. The maximum amount for employees with a pension fund is CHF 7,258.
At the time of testing, it was not possible to make a deposit using real money because we had already reached our 3a maximum limit for this year. We are therefore unable to comment on processing, trading and reporting from our own experience. These aspects are based on the documentation and responses provided by findependent.
Who would benefit from findependent 3a?
findependent 3a is cheaper than finpension, VIAC and, frankly, by far the most so with 99 % shares. It’s particularly worthwhile if your 3a is currently held at a bank in expensive funds or in an interest-bearing account. The main reason is the combination: Low-fee and withholding tax-optimised funds for the majority of foreign equities.
If you’re already with finpension or VIAC, the benefit is minimal. With 50,000 Swiss francs, holding 99 % shares amounts to around CHF 50 to 75 per year. With a lower equity allocation, the figure is lower because, depending on the fund, more Swiss property is included in the portfolio. A switch is not essential.
Instead of transferring your existing balance, you can direct future deposits into a new portfolio with findependent. This allows you to spread your 3a savings across several accounts and prepare for staggered withdrawals. If you want a 3a account or are planning a WEF early withdrawal, another provider would be a better fit.
Before you make up your mind: In the Pillar 3a comparison You can see all the providers, along with their fees and fund classes, side by side.
Tip: If you open a findependent 3a account, enter the code «schwiizer3a» when you register. This means that the first CHF 2,000 will be permanently exempt from management and custody fees. Re: Findependent 3a
Is Findependent 3a safe?
The assets belong to the Findependent 3a Pension Foundation, not to Findependent AG. The foundation is supervised by the Canton of Aargau. The securities are held in custody at Zürcher Kantonalbank and belong to the foundation. Only around 1 % is held as cash at Hypothekarbank Lenzburg, with pension assets up to CHF 100,000 enjoying privileged status.
Which bank is behind findependent 3a?
The securities are held in custody by Zürcher Kantonalbank; the funds are provided by Swisscanto, which is also part of ZKB. The cash, amounting to around 1 %, is held at Hypothekarbank Lenzburg. The contracting party is the findependent 3a Pension Foundation in Aarau.
How much does findependent 3a cost?
0.29 % per annum, including fund costs. In strategies holding between 20 and 80 % shares, the Swiss property fund adds approximately 0.07 %. Deposits, strategy changes, transfers and withdrawals on retirement are free of charge. An early WEF withdrawal costs CHF 500.
Is it worth switching from finpension or VIAC?
With 99 % shares, the fee saving is around 0.1 %; for 50,000 Swiss francs, this amounts to around CHF 50 per year. The saving is smaller if the portfolio includes property. Switching is free of charge, but not compulsory. An alternative: direct future deposits into a new portfolio with findependent and leave the existing balance as it is.
findependent or finpension: Which is better?
With 99 % shares, findependent, at 0.29 %, is around 0.1 % cheaper than finpension. With lower equity allocations, the difference is smaller due to the property fund. Both use institutional pension funds. finpension has a track record spanning several years, whilst findependent is new.
What does the code «schwiizer3a» do?
The first CHF 2,000 are permanently exempt from management and custody fees. Without a code, there is no fee exemption for the 3a account. Only one code applies per person, either for the 3a account or for Invest. You enter it when you first register in the app.
As a findependent customer, can I still use the code?
No, the code is only valid for first-time registrations. However, existing Invest customers can transfer their free allowance to the 3a account, according to findependent.
What are IPF funds?
IPF stands for «Institutional Pension Fund». Only pension schemes such as pension funds and 3a foundations are permitted to invest in these Swisscanto funds. In return, they do not pay withholding tax on US dividends. In contrast, many standard Swiss equity funds are subject to a 15 % withholding tax.
Which funds does findependent 3a use?
Swisscanto index funds denominated in Swiss francs, with dividends reinvested and physically replicated. For US and Japanese equities, these are IPF funds, which are available only to pension schemes and do not incur withholding tax on US dividends. Most equity funds belong to the «Responsible» range, which applies sustainability criteria.
Does findependent offer a 3a account?
No. findependent only offers investment solutions. According to findependent, a 3a account is possible, but not currently planned. A vested benefits solution is planned.
No investment advice.