Findependent experience review test coupon code referral code fees comparison legit security

Findependent review: The big review

When Schwiizerfranke was founded, investing for investors with small to medium assets in Switzerland was still complex or expensive. In the meantime, there are ever simpler approaches for private investors. Findependent is one such provider that does this specifically transparent and simple in Switzerland made possible. We have Findependent Sync and corrections by n17t01 and would like to share our findings with you in this Findependent review.

What makes Findependent's offer special on the market and what speaks for and against Findependent, we clarify in this Findependent Review!

📊 Findependent: The key points at a glance
Foundation2021, Aarau (Switzerland)
RegulationFINMA-licensed securities firm, Account & Investment Account directly with Findependent
Deposit protection (cash)Up to CHF 100,000 (esisuisse), cash component approx. 1% of the investment amount
ETF investmentsSpecial assets, legally belong to you, even in the event of insolvency
Minimum investmentCHF 500
FeesThe first CHF 2,000 is free of charge for everyone, thereafter 0.40% p.a. (more favourable from CHF 50,000)
Investment strategies5 strategies (20% to 98% shares) + my own ETF portfolio
ETF selection40+ pre-selected ETFs (incl. dividends, Bitcoin, gold)
SustainabilityExclusion procedure (no additional cost surcharge)
Tax statement✅ Free of charge, electronic
Child/multi-target investing✅ Several investment goals in parallel
Pillar 3aAvailable from 19 October 2026, 0.29 % p.a., including fund charges. Go to the findependent 3a test
Who is it suitable for?Beginners & all those who want to invest easily
💡 Schwiizerfranke assessment: Findependent convinces with low fees, a clean FINMA setup and maximum simplicity. If you want to compare, you can find Robo-Advisor comparison all options side by side.
Findependent coupon code voucher referral deal link
* A CHF 20 credit will be applied once you have paid in at least CHF 500. Only one code is valid per person, either for Invest or for Pillar 3a.
swissfranconian

Table of contents

Findependent explained

Since the spring 2021 stands the Findependent Investment platform available for investors. The founding team around Matthias Bryner has the mission of making investment in Switzerland as simple and understandable as possible for beginners.

Complexity is deliberately avoided, and everything is kept as simple and as transparent to reach newcomers at eye level. The strong digitalisation in the offer ensures low costswhich are intended to make investing more attractive to investors.

We find the concept exciting and have therefore agreed with Findependent on a Interview exchanged. The following information is the result of a conversation with the managing director. 

What's important with young fintechs like Findependent is the Seriousness and Security of financial investments.

Since the beginning of 2026, Findependent itself has been a Account-holding securities firm with FINMA authorisation. The account and custody account are now managed directly by Findependent, without going through a third-party bank. This speeds up the entire process considerably: IBAN, deposits and initial investments are sometimes possible on the same day.

Your cash portion (approx. 1% of the investment amount) is covered by the Swiss deposit insurance protected up to CHF 100,000. Your ETFs are considered special assets and legally belong to you, even in the event of insolvency.
Findependent strategy

Findependent experience review test voucher code referral code findependent performance rendite strategien vermögensverwalter schweiz

Passive investing with Findependent

The Findependent investment strategy is passively oriented and is suggested for you after a short assessment of your risk profile. You can manually adjust the investment strategy afterwards, as you might have done with providers like True Wealth or perhaps Finpension in the 3a area.

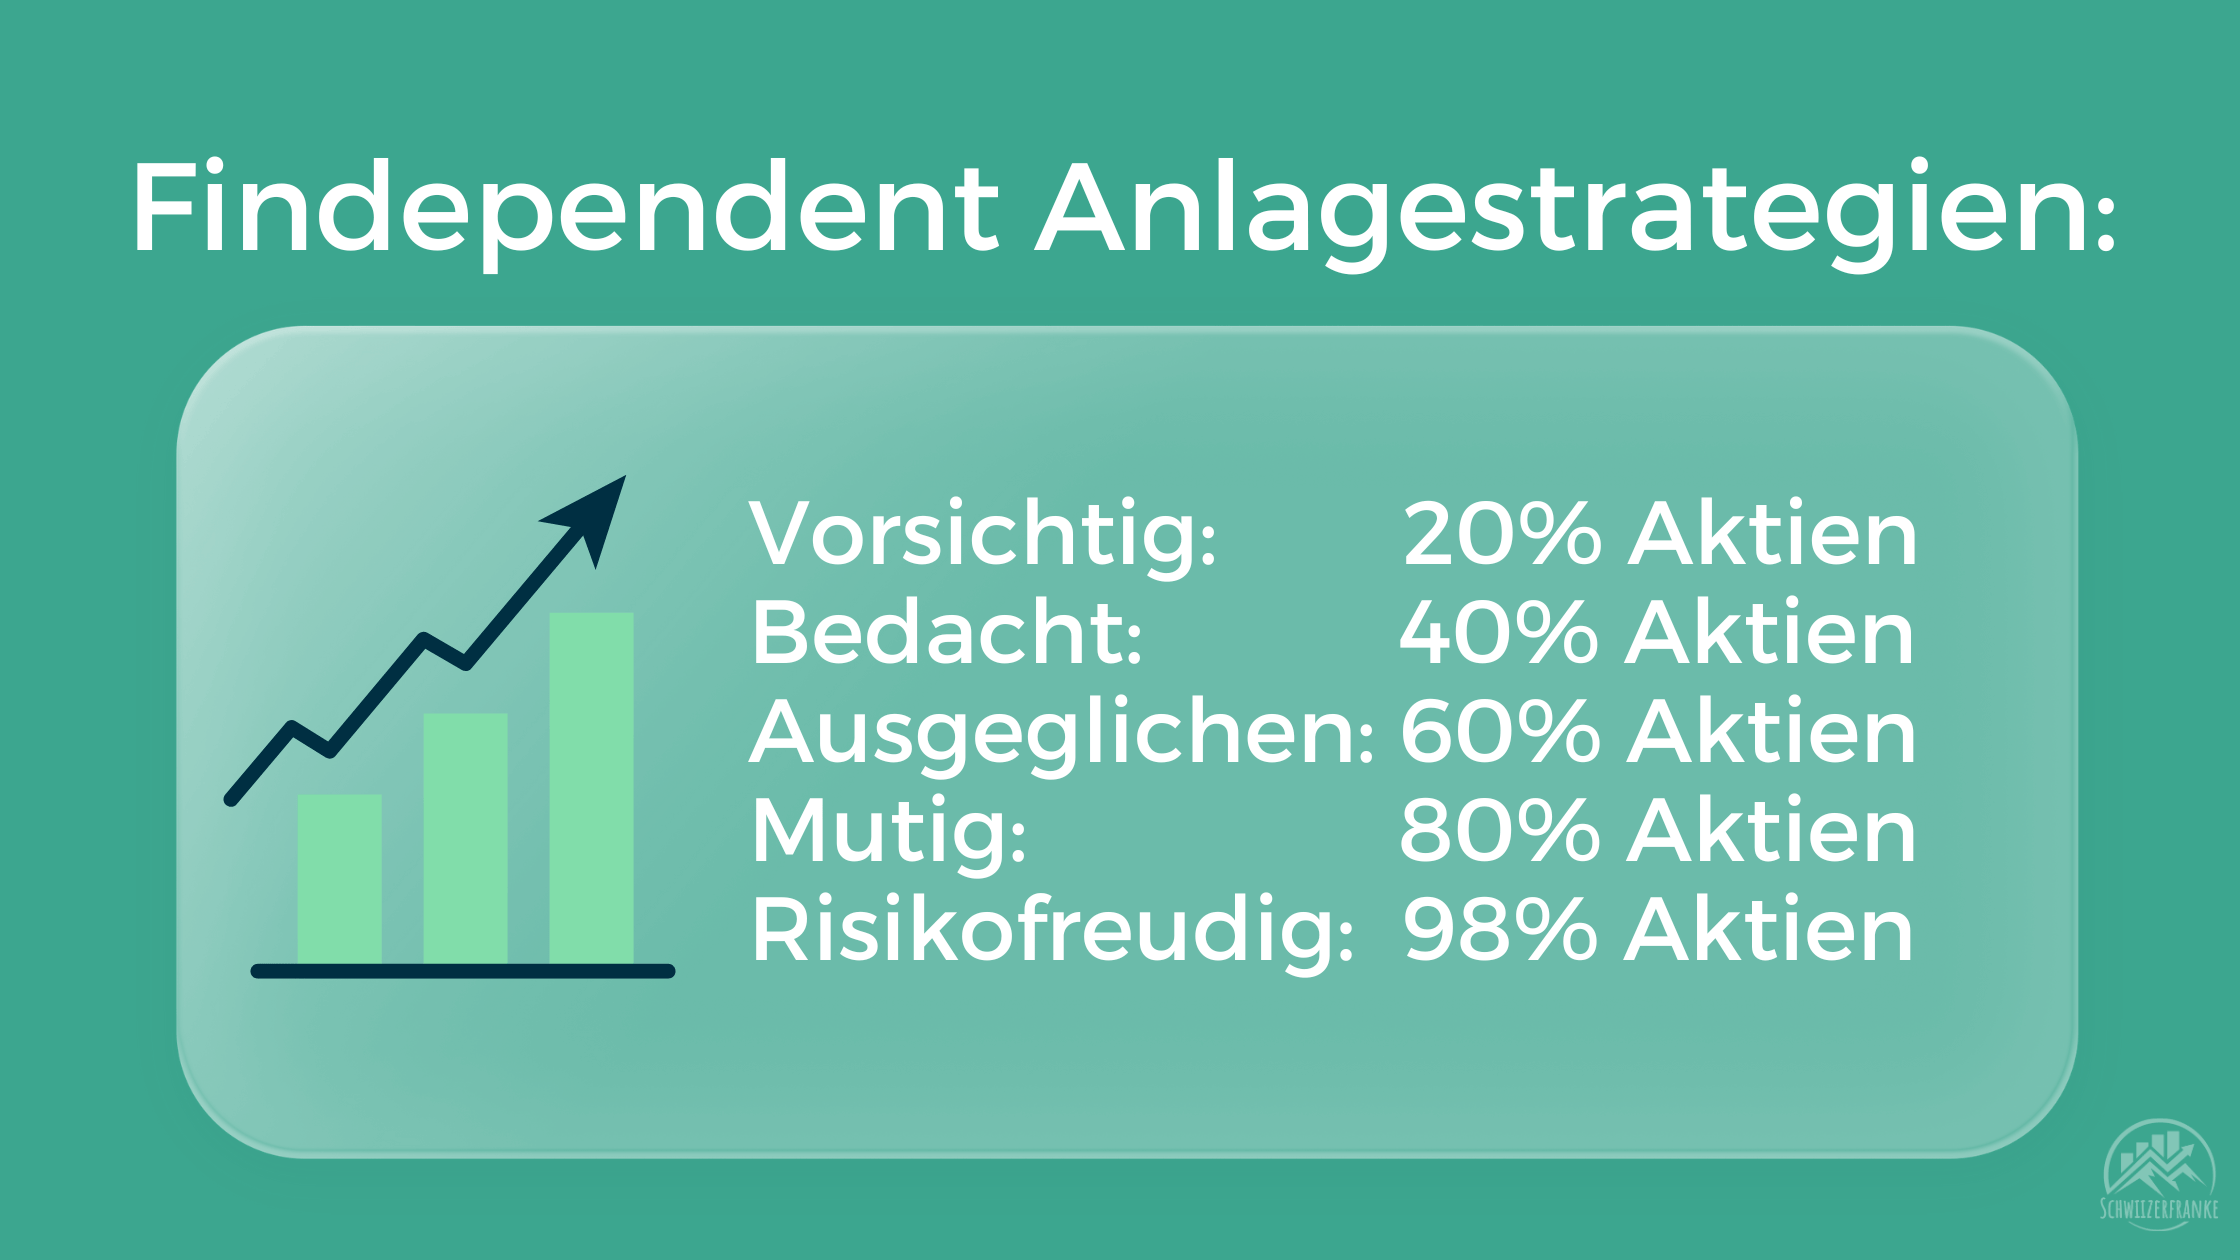
There are currently 5 Strategies ("Cautious", "Prudent", "Balanced", "Courageous" and "Risk-taking") are available. The "Risk-taking" strategy with 98% shares is particularly exciting for investors with a longer horizon (in our opinion at least 10 years). Incidentally, the well-known economist and professor Thorsten Hens from the University of Zurich is on the investment committee.

The Findependent strategies also contain shares in bonds, real estate and cash in accordance with the respective equity quota. They each consist of ETFs and thus implement a cost-efficient, passive and broadly diversified Investment Style.

For all "nerds": By the way, the currency risk is not hedged. The foreign securities are thus subject to a foreign currency risk. But hedging always costs ongoing fees, which is why this is usually not done.

Sustainable investing at Findependent

Sustainability is approached at Findependent via the exclusion procedure. The selected ETFs are screened and controversial companies that are involved in war weapons or oil production, for example, have been removed. The positive thing about this is that the sustainable approach has been implemented in such a way as to no increased costs and thus has a positive impact on our Findependent experience report.

Findependent coupon code voucher referral deal link
* A CHF 20 credit will be applied once you have paid in at least CHF 500. Only one code is valid per person, either for Invest or for Pillar 3a.

Your own investment solution: Doing your own ETF savings plan?

Own investment solution with Findependent:

When Schwiizerfranke went online in 2019, there was no option for an ETF savings plan in Switzerland. With the subsequent launch of Findependent's "own investment solution", we are now getting heart-stoppingly close. Because Findependent has been offering the option of its own ETF strategy since the end of 2021.

You want your ETF savings plan instead of via Roboadvisor prefer to do it yourself?

At Findependent, you can choose from over 40 pre-screened ETFs and create your own ETF strategy. These now also include special dividend, Bitcoin and gold ETFs.
The respective ETF costs (TER) are listed in a structured way in the overview and you can view the sustainability ratings (ESG) in the factsheets.

Findependent performance and return

The Findependent Performance You can view this clearly on the provider’s website. So, before you decide on a strategy, you can historical Findependent yield Take a look at this strategy. You can find it in the PDF factsheets of the respective strategy.

Findependent fees

Official Findependent Fees:

The minimum investment at Findependent starts at CHF 500. Up to CHF 2,000 is available to all customers no custody or management feeswhich is of course very customer-friendly.

The official Findependent fees start then from CHF 2'000 and lie with 0.40% per year, from CHF 50,000 onwards, they decrease gradually. On top of this, there are ETF costs, exchange rate surcharges and stamp duties, for example. Details on the Costs with an example can be found here.

Overall, the costs are thus very inexpensive and are roughly in the range as Selma or True Wealth. Especially for beginners the bonus is very exciting, which is even better for you as a Schwiizerfranke reader.

Findependent fees for Schwiizerfranke readers:

For readers in Swiss francs, there’s a special offer with Findependent. When you register, enter the Voucher code «schwiizerfranke» Once you have paid in at least CHF 500, you will receive a credit of CHF 20 into your Findependent account.

Only one code is valid per person, either for Invest or for Pillar 3a. There is a separate code for Pillar 3a offering CHF 2,000 free of charge; you can find all the details in our findependent 3a Test.

Findependent return and historical Findependent performance in comparison vs True Wealth vs Selma vs Finpension Invest
Independent performance: Performance of a CHF 1,000 one-off investment after all costs, based on index data.
Findependent coupon code voucher referral deal link
* A CHF 20 credit will be applied once you have paid in at least CHF 500. Only one code is valid per person, either for Invest or for Pillar 3a.
swissfranconian

Investing for children with Findependent

The Findependent Kinderdepot has been in place since 2023. Investing money for children was made possible. So now you no longer have to hope for interest for your child or your godchild, but can also invest in shares for minors.

Important: Legally, the children's account is in your name. This way you can pay tax on it properly and transfer the assets to the child when you think the time is right.

As Findependent now generally offers several investment goals or pots, you can now save for several goals at the same time. You can see why this is so advantageous in the following example:

  • Investment objective 1Your long-term investment goal until retirement with maximum equity exposure
  • Investment objective 2: Your medium-term goal for a trip around the world with a balanced investment strategy
  • Investment Objective 3: The pot for your godchild, which follows a long-term strategy.
  • …

You can find all children's depots here in the Child custody account comparison.

Findependent Lion's Den

Those who already have a Findependent account or have been considering it were certainly pleased about the Findependent The Lion's Den Appearance. The young fintech was able to raise CHF 150,000 for further developments there a few years ago.

Also the cooperation with Neon This gave the company a boost, as Roland Brack went on to invest in both Swiss fintechs. Naturally, the Findependent appearance on the TV programme *Höhle der Löwen* helped to attract attention and, as a result, win new customers.

The brand of the 30,000 customers and more than 500 million Swiss francs under management has now been exceeded.

We are keen to see what Findependent will launch next for its clients thanks to this investment. Its own ETF investment solution was already an innovative offering that many were likely waiting for. Since October 2026, there has also been a dedicated Pillar 3a scheme with a fee of 0.29 %. You can read all about it in our findependent 3a Test.

Negative Findependent experience?

Our Findependent experience are consistently positive so far. The reviews for Findependent are also positive on other platforms. very positive and the Findependent tests are solid and good.
Findependent is still relatively new. Should our experiences change, we will be happy to update and share them with you here.

In the meantime, we have even had the opportunity to meet the founder and CEO Matthias Bryner in person and exchange ideas with him. This further strengthened our positive assessment, as we were able to gain a good insight into the company's further development steps.

Because it is sometimes asked whether Findependent serious and one thing is certain: Yes, the provider is secure and trustworthy. This is shown by numerous real tests and this Findependent evaluation from us.

Conclusion of the Findependent Review

Findependent is uncomplicated, transparent and simple. Other Findependent reviews on the Internet are very positive. Conversely, simplifications are of course always limiting. After all, Findependent is not the right place for anyone who likes to actively intervene in their investments, wants to see more information about the exact ETFs or similar.

But who likes Invest uncomplicatedly can test this with Findependent and deliberately keep the costs low.  

Our Findependent experience report can be very positive summarise. By the way, you can find a Findependent comparison with other digital asset managers.

We are excited to see how Findependent will establish itself on the Swiss market in the long term and what the first investment experiences with real customer experiences will look like. 

You have more Questions to Findependent or suggestions on the subject of investments?

Leave us a comment there!

Findependent coupon code voucher referral deal link
* A CHF 20 credit will be applied once you have paid in at least CHF 500. Only one code is valid per person, either for Invest or for Pillar 3a.
swissfranconian

Transparency notice: This post was produced in collaboration with Findependent. We have not received any remuneration for this. The content and description have been produced independently and at our own discretion. Links marked with an asterisk (*) are affiliate links: if you open an account via these links, Schwiizerfranke will receive a commission. This does not affect you in any way.

Top recommendations for 2026

Your key to success! Discover our top recommendations from real testimonials.

30 responses
  1. I have been a Findependent member for a long time. Save CHF 3000.00 in administration and custody fees for life with the friendship code.

  2. With the code you can invest the first CHF 4'000 without administration and custody fees when you open an account with findependent - that's a really great deal! My experience with findependent was great. The app is easy to use and feels very authentic. If I had any questions, I could just call and Vincent or someone from the team would get straight back to me. It's really fun to invest in such an uncomplicated way. Thank you, Matthias, for developing something so great!

    Greetings from Schaffhausen! 🤍

  3. You have a code to register with Findependent, so your first 3000 are free of administration and custody fees (for life)!

  4. I think independent is a great way to start investing and since the end of 2023, the returns have also been really fun again 😉
    If you enter the Findependent code, you can also benefit when you open an account!
    LG

  5. Thanks to the registration code you will receive a lifetime discount on your first 1000 - no fees!

  6. I've had a good experience so far. Findependent works together with Hypothekerbank Lenzburg. Feels like a solid company so far. When you open an account, enter the referral code and invest the first CHF 3,000 for life without administration and custody fees. I also got a code from colleagues. It worked 😉! I can only recommend it.

  7. Hello Eric
    First of all, a big thank you for your great work. I myself have been investing for over 20 years (for a long time it was with expensive active funds) and have gradually been able to adapt my strategies accordingly. I have also got to know most of the roboadvisors with all their advantages and disadvantages.
    Passive investing is fun and should be for everyone. But what I'm missing (or I just haven't found what I'm looking for in all my products) is passive withdrawal. At some point the time will come and the money will be needed; having several million at the age of 90 is nice, but not necessarily practical.
    With the active funds from PostFinance, you could set up a withdrawal plan and a fixed amount was paid out each month. In this way, an average price can be achieved when selling and you don't have to be actively behind it, which also keeps emotions out of the equation, which in my view is the most important thing when investing.
    Do you have any plans for this topic, or does something already exist?
    Greetings Marcel

    1. Hello Marcel
      Thank you very much for your kind feedback 🙂

      The point you raise is very important. Withdrawal will come to us all at some point. Not all providers actually offer such automated payouts yet. But since most providers are still young, this topic will probably be at the back of the agenda, but hopefully it will come soon ...
      I have already made a contribution here to the withdrawals written.
      Kind regards,
      Eric

  8. Hey! I use the investment app findependent.

    If you would also like to try it out, you can enter the code when you open your account and invest your first CHF 4,000 for life without any administration or custody fees. But you can start from as little as CHF 500!

  9. I am very satisfied with Findependent's service. The platform is easy to use and offers a good overview. I particularly like the possibility of receiving allowances through referrals. With the code, you can receive an allowance of 1000.- when registering 🙂

  10. I also started with findependent last week.
    The code is there to save administrative fees up to 3000 Chf!

  11. Hey! I use the investment app findependent.

    If you also want to try it out, you can enter the code when opening the account and invest the first CHF 3,000 for life without administration and custody fees. But you can start with as little as CHF 500!

    Learn more at findependent.ch

  12. Hey! I use the investment app findependent.

    If you would like to try it out, you can enter the code when you open your account and invest your first CHF 3,000 for life without any administration or custody fees. But you can start from as little as CHF 500!

    Learn more at findependent.ch

  13. I opened an account with findependent and so far so good for now, very easy to use. They'll also send a report to help file taxes starting this year, which should be quite helpful. You can use this code to get 2000 CHF managed free of fees for life when you open an account.

    1. Hello Together

      With the code you increase your allowance by CHF 1,000 for life. I've been investing for a good six months and I'm delighted.

      Have fun investing 🤙
      Michael

  14. I am now writing my frustration about the whole neo-broker hype off my chest:

    All these apps seem to be aimed at inexperienced, young and possibly naive newcomers to the stock market. They are lured with trendy themes, clicky apps, convenience and goodies for signing a contract.

    The money-making begins for the operators when the assets of the new customers gained in this way increase. Well, you can of course change brokers, but that involves a lot of effort and the "super convenient" customers are unlikely to do so. After all, it is statistically more likely that someone will get divorced in 202x than that they will change banks 🙁

    Let's make a few calculation examples and use Findependent because it is just so appropriate.

    Kevin Klein(stinvestor) invests 1000.- for the next 40 years and we assume that his investment fund (according to TER) returns 7%. With fees of 0.44%, the 1000.- becomes 12700.- in 40 years. Sounds great! But without fees it would be 14970. 1170% or 1397% profit, that's quite a difference!

    Stefan Sparsam invests 100,000 with Findependent. This results in fees of (100.000.- - 2000.-) * 0.44% = 431.20 p.a.
    Ouch. He would have been much better off with Postfinance (90.00 fixed which are then also credited as trading credit).

    I may sound like the Advocatus Diaboli but don't get me wrong. I have nothing at all against young people investing with a small budget and thus gaining experience. Let them burn their fingers and learn from it with relatively little loss.
    What I miss in your praise is a hint that with _the_ cost structure such a solution is only worthwhile up to the amount of CHF xy and for higher amounts the broker x or y would be better.

    Why don't you write an article: "Up to what amount are neobrokers cheaper than [Postfinance / Swissquote / DeGiro]". In Stefan Sparsam's example above, the limit is 22450.

    Just so my two deleted apps

    1. Dear Alain
      Thank you for your comment. You have expressed some important points and opinions. Here are a few thoughts from me:

      - Findependent is also aimed specifically at beginners, as investments are possible from as little as CHF 500. Perfect for gaining initial experience and getting a feel for investments. As the securities account grows, so does the knowledge and then a customer may also accept the services of a broker. In my opinion, comparing Postfinance Trading and Findependent 1:1 is somewhat misleading. Rather, you should use the Postfinance Robo Advisor, which is probably one of the most expensive in comparison and is about twice as expensive as Findependent. The article will follow in 2 weeks.

      - Anyone with a larger portfolio/assets will get better conditions with pretty much any provider. If a provider does not reward this and customers then switch, it is the provider's own fault. If customers are lazy about switching, as you say, and then neglect a change and thus potential savings, this is a shame. But Schwiizerfranke is of course trying to encourage this with information and transparency. Your hint as to why this is not said in every post on Schwiizerfranke: Nobody wants to read a 5-page article comparing everything and every provider and every option when all they really want to know is whether a young fintech is reputable and what advantages and disadvantages it offers. Or not?

      - In my opinion, providers that target non-wealthy customers are very relevant. The majority of our population was not born wealthy and did not learn how to handle money at school - if they can at all. In my opinion, you have to learn it yourself with "skin in the game" as they say.

      This is just my opinion. Thanks for sharing your thoughts 🙂

  15. Thank you for the testimonials about the different providers and roboadvisors for sustainable investing. I've been investing through Degiro for a few months now and I'm very satisfied because I don't only want to invest passively in ETF but also in individual stocks. For my girlfriend, who is not interested in investing, such a provider like Findependent or Selma is ideal. I introduced her to the different providers today and she finally chose Findependent. We wonder what the tax situation is like in Switzerland. Does Findependent issue a tax certificate, so that one can fill out the tax as easily as possible?
    Thank you very much for the helpful articles and I look forward to the next Wealthletter.
    Kind regards
    Tino

    1. Hello Tino,
      thank you so much for your positive feedback and recommending the blog to others 🙂
      The CH providers usually all issue a tax certificate, which automatically arrives in the spring at tax time. This is the case for Selma, True Wealth, Findependent and Inyova. (Unfortunately, this is not the case with Swissquote, where the statement costs CHF 100).
      Your girlfriend has no trouble with a CH Robo Advisor like Findependent, but can write off the amount from the statement and give a copy of it ideally as a receipt for taxes.
      Best regards and see you in the next Wealth Letter 🙂
      Eric

  16. Simply enter my code when you open your account and invest your first CHF 3,000 free of administration and custody fees - for life!

Write a comment

Your e-mail address will not be published. Required fields are marked with * marked.

Saxo Bank Switzerland Review 2026: Test & Fees
Findependent experience report 2

Saxo Bank Switzerland: from CHF 3 per trade, no custody fees and commission-free ETF savings plans. Security, drawbacks & a CHF 200 bonus.

Price Currency: CHF

Operating System: Web

Application Category: Investment

Editor's Rating:
4.7
Cover: Investment Guidebook

Free guidebook

Your Investment Guidebook

How to get started with investing in Switzerland on a budget and in a structured way

  • The 3-account model: keeping your finances in order, automatically
  • ETF savings plan, Pillar 3a with shares, broker: where to get started affordably
  • 3 tips for getting started and how to save on fees

The guidebook will be sent to you as a PDF via email. After that, you’ll receive the Wealth Letter every Wednesday. You can unsubscribe at any time.