



What is True Wealth and what are ETFs?
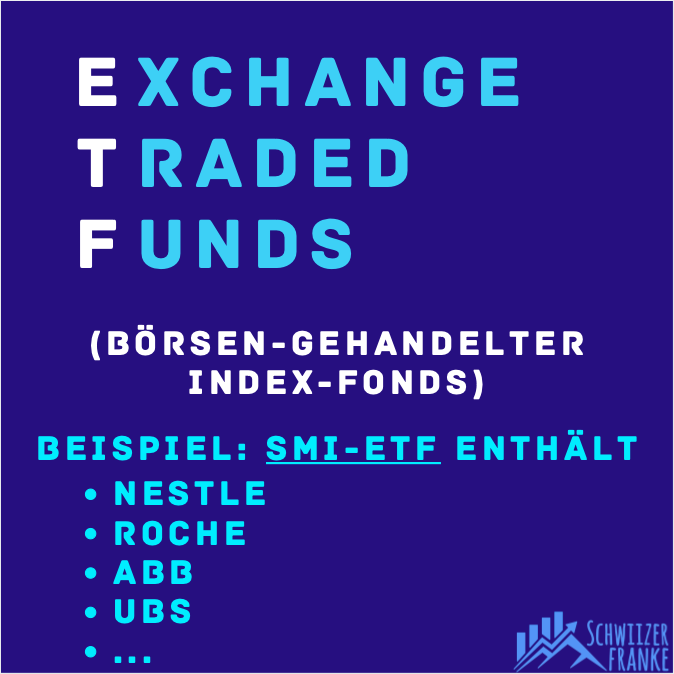
True Wealth (TW for short) is one of the established Swiss robo-advisors that specialises in investing in ETFs - i.e. so-called passive investing.
Investments are not made in individual shares or even trading. Instead, the focus is on the market as a whole, thus minimising the risk of individual companies. Depending on the index (e.g. SMI = Swiss Market Index), the return historically varies between 4% - 9% per year.
How True Wealth works in three simple steps:
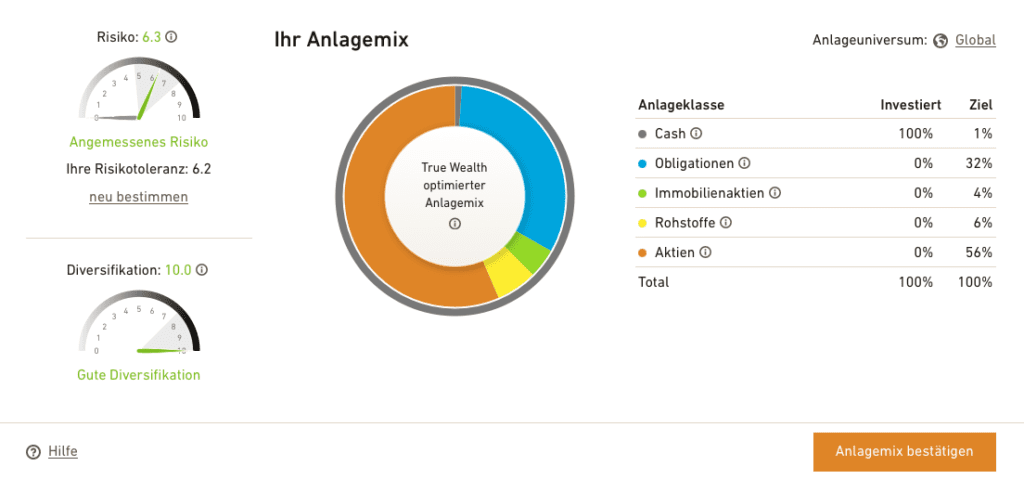
- You create an investment profile based on your goals and risk appetite
- TW creates a diversified ETF portfolio for you
- The robo-advisor manages your portfolio automatically and adjusts it regularly
True Wealth Performance is very similar to the market, but more on that later. The Robo Advisor offers you as an investor a very inexpensive and easy access to ETFs or passive investments.
The True Wealth fees look very attractive. Read on to find out exactly how the platform works, what the advantages and disadvantages are and what the True Wealth alternatives are.
Hello
I live in Switzerland and have two investment accounts abroad, denominated in EUR and USD, containing individual shares, funds and ETFs. At the moment, my father manages these accounts, but not for much longer. I don’t want to pay for expensive asset management, and I’m not in a position to manage the accounts myself (too little experience, no time). I’m hesitant about TW because the investments are made in CHF, which means currency conversions take place. Would I be better off investing my existing funds directly in ETFs denominated in USD or EUR myself, or does it ultimately make no difference whether I invest in CHF (without currency hedging) or in a foreign currency?
Kind regards
Oli T.
Hello Oli
The account or trading currency is not, in principle, the same as the currency risk associated with the investments. In the case of a globally invested ETF without currency hedging, it makes no significant difference to the currency risk whether the ETF is traded in CHF, EUR or USD.
However, there is no one-size-fits-all answer as to whether switching to True Wealth makes sense. This depends, amongst other things, on the structure of your existing investment accounts and the consequences of any transfer or sale.
If you’d like to compare different providers, you’ll find our robo-advisor comparison here, highlighting the key differences: https://www.schwiizerfranke.com/robo-advisor-schweiz-vergleich
Kind regards
Eric
I’ve been with Truewealth for half a year now. My conclusion so far, in a volatile market environment: for a conservative global portfolio with a high proportion of bonds and around 20% in equities, with or without currency hedging, costing under 500, Truewealth is too expensive and offers too low a return compared to the competition. The fees/operating costs and the chosen ETFs (particularly those for currency hedging) eat into the returns. The question is: is currency hedging worth it for foreign-currency bonds? The competition steers well clear of it.
Thanks for the detailed report, Harry; that’s exactly the sort of feedback that helps other readers.
However, one point is not quite right: the competition is by no means shying away from foreign-currency bonds. Hedging is the norm for bonds, not the exception. The reason is simple. A bond might yield 1 to 3 per cent, whilst the fluctuation of the US dollar or euro against the Swiss franc is around 7 to 10 per cent per year. Without hedging, you’re effectively holding a currency bet with a small coupon attached. In doing so, you’re undermining the very thing you’re holding bonds in your portfolio for: stability. With shares, it’s the other way round; hedging is often not worthwhile there.
What you’re feeling isn’t primarily the cost of hedging either. That’s minimal. Hedging neutralises the interest rate differential between the Swiss franc and the foreign currency. It feels like a charge, but it isn’t one. If this effect didn’t exist, anyone could pocket higher foreign interest rates risk-free.
The legitimate question is therefore a different one: why invest in foreign-currency bonds at all, when CHF bonds fulfil the same purpose without this detour? In a defensive portfolio, that is a legitimate point of view.
Just to check I’ve understood you correctly: what do you mean by «under 500»? Is that the monthly contribution or the return in Swiss francs? It makes a big difference to the assessment. Regardless of that: with a 20 per cent equity allocation, half a year isn’t a meaningful assessment period – it’s just noise.
Refers to the fee structure = for capital of less than CHF 500,000. This is on a sliding scale.
The total investment costs amount to 0.63% (management fees 0.50% + product costs 0.13%). This does not include the foreign currency surcharge. As I understand it, currency hedging with Truewealth applies to both bonds and shares. It is therefore not freely selectable. As regards CHF bonds, I understand that these cannot be selected as such, as only the ‘Global’ or ‘Sustainable’ investment universes are available.
I also don’t think the allocation/selection of equity ETFs is ideal, both in terms of market allocation and the specific ETFs themselves (TER, fund size, no ‘best-in-class’ selection). Of course, you can adjust them manually, but that just generates further costs… for me.
For me, this turbulent six months under Trump is quite representative of how the portfolio might perform over a longer period. I have a virtually identical portfolio with a 20% equity allocation with a competitor, which has delivered double the return with lower investment costs, excluding foreign exchange surcharges and including stamp duty, over the same period.
Thanks for clarifying that, Harry.
As far as I am aware, two things are different: Currency hedging can be
disable it; there’s even a dedicated FAQ entry for this on TW.
And you can weight asset classes or exclude them entirely. What you
you cannot choose the specific ETF within a class. Since
You’re right. It’s best to ask about your specific portfolio
check directly with TW Support.
As for the rest, I stand by my view: half a year is not a sufficient period for assessment—
period, no matter how turbulent. The costs, on the other hand, are certain.
What I do understand, however, is that with a 20 per cent shareholding, the expected
The return is low, and the 0.63 per cent fee eats into it significantly on a pro rata basis
more than with an aggressive portfolio. If your other portfolio
If that suits you better, it’s a perfectly valid decision.
No investment advice.
Thanks, Eric
Regarding the last section: It cannot be the aim simply to cover the TW fees – which, in my view, are too high – and inflation of «0.5» per cent (more like 2%). You’re quickly getting into the realm of savings account interest rates with special terms. In my view, it’s not worth the effort. An aggressive portfolio also entails higher risk for the investor and is no longer consistent with the risk profile. Rebalancing then incurs additional costs. After all, it’s not possible to hold multiple portfolios with TW. So we’ll have to move on where possible, or simply work with different providers.
Is it still possible to enter the voucher code somewhere (May 2026)? I can't find a field for it.
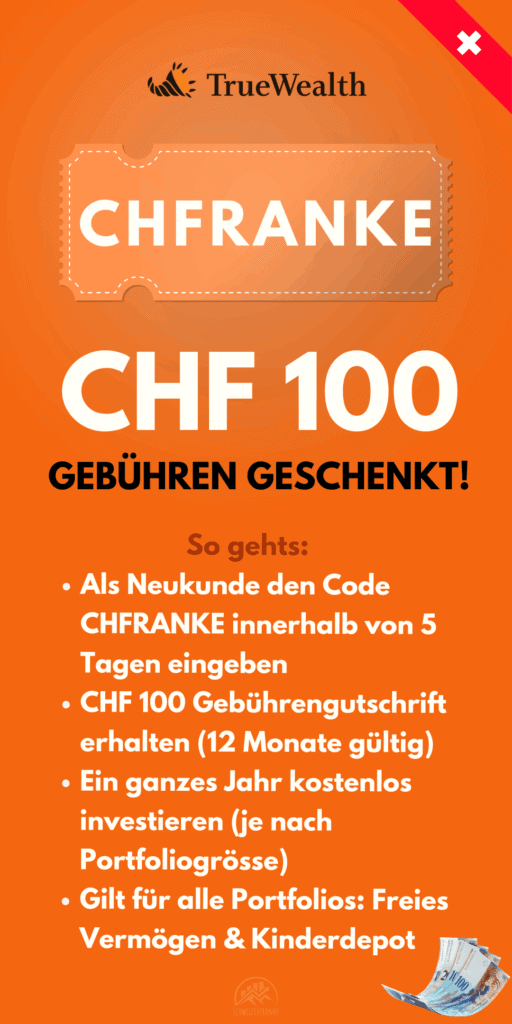
Yes, you can still enter the code. You can enter the code in the menu under «Fees» up to 5 days after opening an account. Does that work?
Otherwise, please get in touch here or with TW support
Assuming someone has assets of 300,000 francs and is dependent on a withdrawal of 15,000 francs per year, does it make sense to invest with True Wealth, and if so, which part would be advisable? Thanks&Greetings
Good question! The 5% withdrawal (CHF 15,000 to CHF 300,000) is ambitious, but not impossible. As a rule of thumb: below 4% is solid in the long term, above that you need a buffer.
True Wealth can make sense, but it is also important to plan your budget correctly
Thanks a lot!
I have been a satisfied customer of TrueWealth for several years now and can clearly recommend the company!
The referral code does not work for me - why?
it says it is expired and no longer valid
should work - can you test again please?
At Truewealth, you can also deposit in euros. Does it actually make sense to do so (if you have surplus euros from a previous life), or would it be better to convert the euros into Swiss francs and then deposit them? Or does it ultimately not matter at all?
This can be very useful! Your strategy will probably also include investments in foreign currencies (EUR, USD, GDP, etc.), and this will allow you to reduce currency fees.
Of course, this only makes sense if you already have the currencies available...
Assuming the TW strategy does not suit me, can I cancel after one year? If so, would you transfer the amount to the specified account, for example?.
I remember the Behring case. Could that be it?
Regards, M Keller
Hello Mr Keller
Good questions! Regarding your points:
Termination: Yes, you can terminate at any time – there is no minimum term. True Wealth will then sell your investments and transfer the amount to your designated reference account.
Behring case: Understandable concern, but the situation here is fundamentally different. With True Wealth, your assets are held by a regulated custodian bank (Saxo Bank Switzerland or BLKB) – not by True Wealth itself. Your securities are special assets and remain protected in the event of bankruptcy. True Wealth has no direct access to your funds, unlike in the Behring case.
Kind regards
Eric
PS: For anyone wondering what this refers to... The «Behring case» refers to one of the biggest investment fraud cases in Switzerland – asset manager Jürg Behring embezzled hundreds of millions of pounds of client funds in the 2000s. The funds were gone because they were not kept separate from the asset manager. With regulated providers such as True Wealth, this is now impossible thanks to the custodian bank structure.
Thanks for the great summary. Would you set up another custody account somewhere else in addition to the TrueWealth custody account for security reasons once you have reached around CHF 100,000? Or would you simply continue to invest with TrueWealth? LG and thanks in advance!
The 100,000 limit only applies to cash deposits. Securities such as equity ETFs belong in the special assets and have no upper limit. So you can "just keep investing" 🙂
I have been using TrueWealth for several years. I am very satisfied. Enter the referral code when registering!