calculate net worth with our net worth calculator and understand elon musk net worth thanks to net worth formula

Calculating your net worth: Your net worth in 2 minutes, and what really counts in Switzerland

Your net assets on your tax return are lower than your actual assets. For most people, this is significantly the case. The pension fund is missing, the Pillar 3a is missing, and a house is only listed at its tax value.

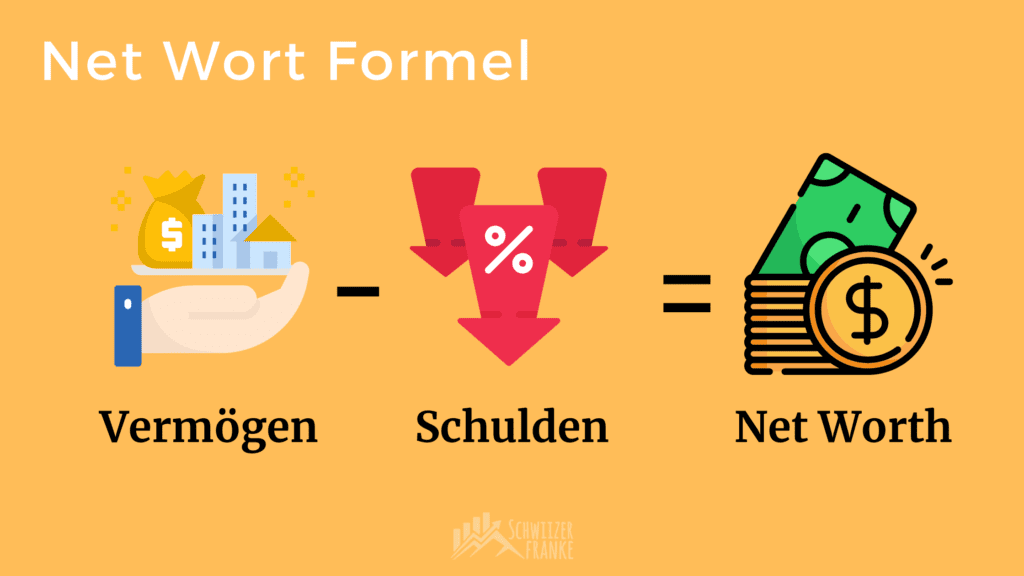
Calculating net worth means: everything you own, minus everything you owe. In English, net worth. The formula is simple, but the Swiss details are not. That’s why this article is in two parts: first, you work out your net worth using the calculator. Then you’ll see what the tax authorities take into account, what they don’t, and how you compare with the rest of Switzerland.

Table of contents

Calculating net worth – Key points at a glance
FormulaNet assets = assets − liabilities (English: Net Worth)
Tax returnexcluding pension fund and Pillar 3a, property at its assessed value
Your net worth✅ including pension fund, 3a savings and property at market value
Net assets of zero or less22 % for taxpayers (FTA, tax year 2022)
Median assets Switzerlandaround CHF 115,000 per adult (UBS Global Wealth Report 2026)
💡 Schwiizerfranke assessment: Direction is more important than the figure itself. Work out your net worth once a year on the same day. After three years, you’ll be able to see whether your decisions are having an effect. Where you are in Switzerland →

Calculate net worth

The calculator above takes everything you own and subtracts everything you owe. On the one hand, bank accounts, pension fund, Pillar 3a, investment portfolio, property. On the other hand, mortgage, leasing, consumer credit, money lent by your parents. The difference is your net worth.

Net worth = assets − liabilities

An example: CHF 5,000 in the bank account, CHF 70,000 in the pension fund, CHF 12,000 in Pillar 3a, CHF 2,000 in other assets. On the other hand, a car lease with a remaining balance of CHF 25,000. Assets: CHF 89,000; liabilities: CHF 25,000; net worth: CHF 64,000.

Whether a debt is «good» or «bad» makes no difference to the figure. A mortgage counts the same as a consumer loan. What matters is the difference – and whether it grows every year.
net worth calculate with our net worth calculator how high shaqiri net worth median net worth switzerland per capita average net worth swiss

What counts as net assets? Two definitions

The term «net assets» has two meanings in Switzerland, and they result in two different figures. The first appears on your tax return. The second is your net worth, as calculated by the calculator above.

 Net assets for tax purposesPersonal net worth
Accounts, cash, investment accountsyesyes
Pillar 3anoyes
Pension Fundnoyes
Real estateto the assessed valueat market value
Life insurance policy with a surrender optionyesyes
Household contents, car (second-hand)nousually no
DebtsYes, all those for which evidence has been foundYes, all of them

For most employees, the pension fund is their largest asset. It is completely omitted from their tax return because pension savings are not taxed until they are withdrawn. The same applies to Pillar 3a. That’s why, at 35, your net taxable assets often look like «almost nothing», even though you have CHF 100,000 or more in your pension savings.

Which figure is the right one? For tax purposes, it’s the first one. For your financial planning, it’s the second. If you want to know how far you are from a goal, everything you own counts – even the money you won’t be able to access until you’re 65.

Net assets on the tax return

In your tax return, the calculation is carried out in two steps. First, you deduct all verified debts from your gross assets. This gives you your net assets. Depending on the canton, social security deductions or a tax-free allowance are then deducted from this figure. What remains is the taxable assets, on which wealth tax is levied.

Gross assets − liabilities = net assets
Net assets − social security deductions = taxable assets

Only cantons and municipalities levy wealth tax; the federal government does not. The level of the tax-free allowance varies considerably. Zurich calculates it differently from Schwyz, and Bern differently from Geneva. Anyone wishing to find out the thresholds for their canton can find them in the tax return guidelines.

Property is not included at its purchase price, but at the official tax value. This is usually significantly below the market value. This, too, pushes down your net taxable assets.

A figure that will become important later on: since 2021, a asset threshold of CHF 100,000 has applied to supplementary benefits to the AHV and IV for single people and CHF 200,000 for married couples. The relevant figure is the net assets as stated in your tax return, excluding your own home. Anyone whose assets exceed this threshold is not entitled to benefits. This doesn’t affect you at 30, but it might affect your parents.

Negative net worth: one in five has none

The Federal Tax Administration records the net assets of all taxpayers. For the 2022 tax year, this amounts to 5.19 million tax units, with married couples counting as one. The result is unsettling: 22.2 % have a net worth of zero or less. That is more than one in five. A further 30.8 % have a net worth of between zero and CHF 50,000.

Part of this is down to how the figures are calculated: anyone who buys a flat with an 80 % mortgage often has a negative net worth on paper, because the property is counted at its assessed value and the mortgage at its full amount. Another part consists of leases and consumer loans with no equivalent asset. And pension provision is completely missing from these statistics.

For you, this means that a net worth above zero already places you above one in five households in the tax statistics. You can find out exactly where you stand using the wealth calculator, which is based on the same FTA data.

Median wealth Switzerland per capita

In terms of average wealth per adult, Switzerland ranks first worldwide. The UBS Global Wealth Report 2026 puts the figure at around USD 910,000, equivalent to approximately CHF 721,000. However, the average is not particularly meaningful, as a small number of very large fortunes skew the figure upwards.

The median is a more meaningful indicator: the person exactly in the middle. Here, UBS puts the figure at around USD 145,500, or approximately CHF 115,000 per adult. This places Switzerland in 8th place, no longer in the top 5.

Important to bear in mind when comparing with your calculator’s result: UBS includes pension fund assets and 3a savings, and values property at market value. It therefore calculates in the same way as the net worth calculator above, not as you would on your tax return. Comparing your tax value with the UBS figure would be like comparing apples and pears.

You can read about the difference between the median and the mean, and where you stand in the Swiss distribution, in the Contribution to average wealth in Switzerland.

Top recommendations for 2026

Your key to success! Discover our top recommendations from real testimonials.

Increase Net Worth with these 3 tips

There are two sides to the formula. So there are exactly two levers, and a third one that makes both of them visible.

  1. Pay off the most expensive debts first. Consumer credit and leasing cost between 5 and 12 % a year, but do not provide an asset that grows in value. Every franc you pay off increases your net worth by exactly one franc. No investment is guaranteed to do that. A mortgage is the exception: it costs less and is secured against a property. You don’t have to sell that first.
  2. Build wealth where it grows. A savings account keeps your money stable in nominal terms – nothing more. In the long term, wealth grows through broadly diversified investments, in Switzerland usually via ETFs and Pillar 3a. You can find out how to get started in the Article on investing money in Switzerland.
  3. Check the figures once a year. Net worth isn’t a figure you work out once and for all. It’s a graph. Record the figure on the same day each year – for example, when you’re filling in your tax return anyway. After three years, you’ll be able to see whether your decisions are having an effect.

Elon Musk assets

Time and again, people have asked about Elon Musk’s wealth as a point of comparison. The figure is linked to the valuations of Tesla and SpaceX and changes daily. When we wrote this article in 2022, it stood at CHF 222 billion. The 2026 Forbes list puts it at USD 839 billion, roughly CHF 660 billion. With that, he could give every person on Earth about CHF 80. What does that have to do with your net worth? Nothing. Except that both use the same formula.

Our financial tips for 2026

"Intelligent people learn from the mistakes of others".

We have compiled our top selection for you from all our tests and experience reports:

Conclusion

Your net worth is the one figure that sums up your entire financial situation. Assets minus liabilities – that’s all there is to it. For tax purposes, the narrow definition – excluding pension provisions – applies. For you, the broader definition applies, including pension funds and 3a accounts, because the money belongs to you.

The direction is more important than the amount. A net worth of CHF 30,000 that grows by CHF 10,000 every year is worth more than CHF 200,000 that remains static. Exception: anyone who still has expensive consumer debt should pay this off first. That way, the return is guaranteed.

Next step: Make a note of the number from the calculator, along with the date. Then in the Wealth calculator find out where you stand in Switzerland.

FAQ

Neither. Both terms refer to assets minus liabilities. «Reinvermögen» is the term used by the Swiss tax authorities, whilst «Nettovermögen» is the term used in Germany and in studies such as the UBS Global Wealth Report. «Net worth» is the English term.

For companies, yes. On the balance sheet, net assets are the difference between assets and liabilities – in other words, equity. For private individuals, the term used is net worth; the principle is the same.

Not on your tax return – the balance is tax-free until you withdraw it and does not need to be declared. As regards your personal net worth, yes – the money belongs to you. The same applies to Pillar 3a.

Add up all assets as at 31 December: bank accounts, securities, property at its tax value, redeemable insurance policies, and a car at its current market value. Subtract all debts as at that date from this total. Household contents and personal belongings are not included.

Debts exceed assets. In Switzerland, this affects over 20 % of taxpayers, often due to mortgages on property valued at a low tax value or because of consumer loans and leasing.

2 responses
  1. I find comparisons between different countries very difficult. In Switzerland, in particular, the attribution of pension fund assets to private assets totally distorts the picture.
    It is true that the PF assets belong to you and in certain cases you can dispose of them. However, if the money is (pre-)withdrawn, this reduces the pension in old age. In this respect, it would be the same as if someone (e.g. in Germany) could mortgage/pledge his future pension (regardless of whether this is possible in practice or not). So, for a fair comparison, wouldn't the present value of future pensions have to be counted as assets, regardless of the pension system?
    This way, the comparison would at least be balanced. For many people in Switzerland who convert their retirement assets to 100% as a pension, the pension fund assets are ultimately also only of a theoretical nature all the time and are not in private assets at any time.

    1. I am completely with you, Hugo. Unfortunately, a key problem here is the data situation. Since official data is collected this way as far as I know, it's hard to make any other comparison. If you find reliable data, feel free to forward it to me at any time.
      As for other pension systems with less flexibility, I don't think they should be included in a net worth determination.

      If net assets are compared internationally, the purchasing power should actually also be taken into account. Or what do you think?

      Incidentally, in the German example, no "equity pension" is implemented and it is purely a matter of savings assets. Swiss pension funds have a good 20% - 40% equity ratio and, in combination with the long investment horizon, can generate considerable compound interest growth. This is one of the reasons why pensions in Germany are lagging far behind.

Write a comment

Your e-mail address will not be published. Required fields are marked with * marked.

Get your free
Investment Guidebook
receive!