

Bank WIR’s ‘top’ banking package is one of the most affordable personal accounts in Switzerland. The account and the Mastercard debit card are free of charge, and when you use the card abroad, you pay the interbank exchange rate with no surcharge. The catch isn’t in the fees, but in the terms and conditions, the online banking service and the customer service. That’s exactly where you’ll find out whether WIR Bank is right for you.
Our experience with Bank WIR is based on several years as a customer and on opening the ‘top’ banking package ourselves in autumn 2026. Read on to find out what the share certificate actually costs and who would benefit from Bank WIR.
Key points at a glance
- Top banking package: a personal current account and a Mastercard debit card with no fees, provided you meet one of four conditions – for example, receiving a monthly salary of CHF 1,500 or more.
- Advantage: Card payments at home and abroad at the interbank exchange rate with no surcharge, plus 24 free cash withdrawals per year worldwide.
- The share certificate costs CHF 200. Upon withdrawal, the bank will repay a maximum of the nominal value of CHF 20. It is an investment, not a free pass.
- Our verdict: Top marks for the terms and conditions. When it comes to online banking and customer service, however, I feel that WIR Bank lags behind the neobanks.
My experiences with WIR Bank
I first came across Bank WIR years ago through a promotional interest rate offer. At the time, it was offering a preferential interest rate on new deposits into savings accounts, which won me over. As a finance blogger, I have well over 20 accounts with various banks, all for the purposes of my reviews. Bank WIR is one of the few where I’ve never been caught out by a fee.
So that you know what this report is based on: For years, I only had a savings account with WIR Bank; I didn’t have the ‘top’ banking package. Once the promotional interest rate period ended, the account automatically converted into a loyalty savings account. I opened the ‘top’ banking package myself for this report in autumn 2026, as an existing customer. You can read below what went well and what didn’t.
My experiences with the ‘Bankpaket top’ are still fresh in my mind, but my experiences with the bank as a customer are not. My impression after all these years: The terms are fair – and they’re fair for the long term. E-banking is a bit more fiddly in day-to-day use than with neobanks such as neon or Yuh. And on two occasions, the customer service wasn’t as smooth as I would have liked.
Top banking package: Services and fees
The ‘top’ banking package consists of two parts: the ‘top’ personal account and a Mastercard debit card. It includes e-banking, mobile banking and TWINT. There are no parcel charges, provided you meet one of these four conditions:
- a regular monthly income of at least CHF 1,500, for example your salary
- Pension savings of at least CHF 20,000 held with Bank WIR
- a mortgage of at least CHF 300,000 with WIR Bank
- A share certificate from Bank WIR for CHF 200 – this makes you a member of the co-operative
For most people, pay is the simplest factor. The ‘top’ banking package is therefore primarily intended as a main account. If you want to use it purely as a second account for holidays and online shopping, your only option is usually a share certificate. You can find out exactly how much it costs below.
This is how much the package will cost you if one condition is met:
| Performance | Banking package top |
|---|---|
| Personal Account Management – Top | free of charge |
| debit mastercard | free of charge; replacement card and replacement PIN are also free |
| Card payments in Switzerland and abroad | 0% commission, no exchange rate surcharge |
| Cash withdrawals worldwide | 24 per year free of charge, then CHF 2 per withdrawal |
| Payments in Switzerland in CHF | free of charge |
| Payments in EUR within the SEPA area | free of charge |
| Other foreign currencies, CHF sent abroad, EUR outside the SEPA area | CHF 5 per order |
| E-tax statement | free of charge |
| Top interest rates on personal accounts | 0 % |
| Termination of the customer relationship | CHF 15 |
All in all, you won’t pay anything in day-to-day life as long as you make fewer than 24 cash withdrawals a year. Fees are incurred mainly on international bank transfers. Anyone who regularly sends money abroad is better off using a specialist provider.
Debit Mastercard abroad
The card is the main reason why the ‘top’ banking package is so good. For card payments in foreign currencies, WIR Bank settles the transaction at the interbank exchange rate, with no surcharge and no commission. This applies in shops, at cash machines and online. With many high-street banks, however, card payments in euros or dollars incur a surcharge on top of the exchange rate, which does not appear as a fee on any statement.
Here’s an example: You spend CHF 3,000 using your card whilst on holiday. With a surcharge of 1.5 per cent, you’ll pay CHF 45 just for the currency conversion. At WIR Bank, this surcharge does not apply. On top of that, you get 24 cash withdrawals per year, which are free of charge at any cash machine worldwide. Exception: some cash machine operators abroad charge their own fee. The machine will display this before you make the withdrawal.
Important: When abroad, always select the local currency, never CHF. Otherwise, the terminal will convert the amount, and the favourable exchange rate offered by WIR Bank will be of no use to you.
For online payments, you’ll also need the free debiX+ app. It’s provided by SIX, the operator of the Swiss financial infrastructure, and many Swiss banks use it for their debit cards. In the app, you can authorise payments via 3-D Secure, view card transactions from the last 30 days, block the card and set spending limits. You can set lower limits yourself; for higher limits, you’ll need to call the advice centre. You can add the card directly from debiX+ to Apple Pay, Google Pay or Samsung Pay.
A credit card is not included in the package. Some providers of hotels and car hire require a deposit to be held, which does not always work with a debit card. It is therefore worth having a credit card as a backup when travelling.
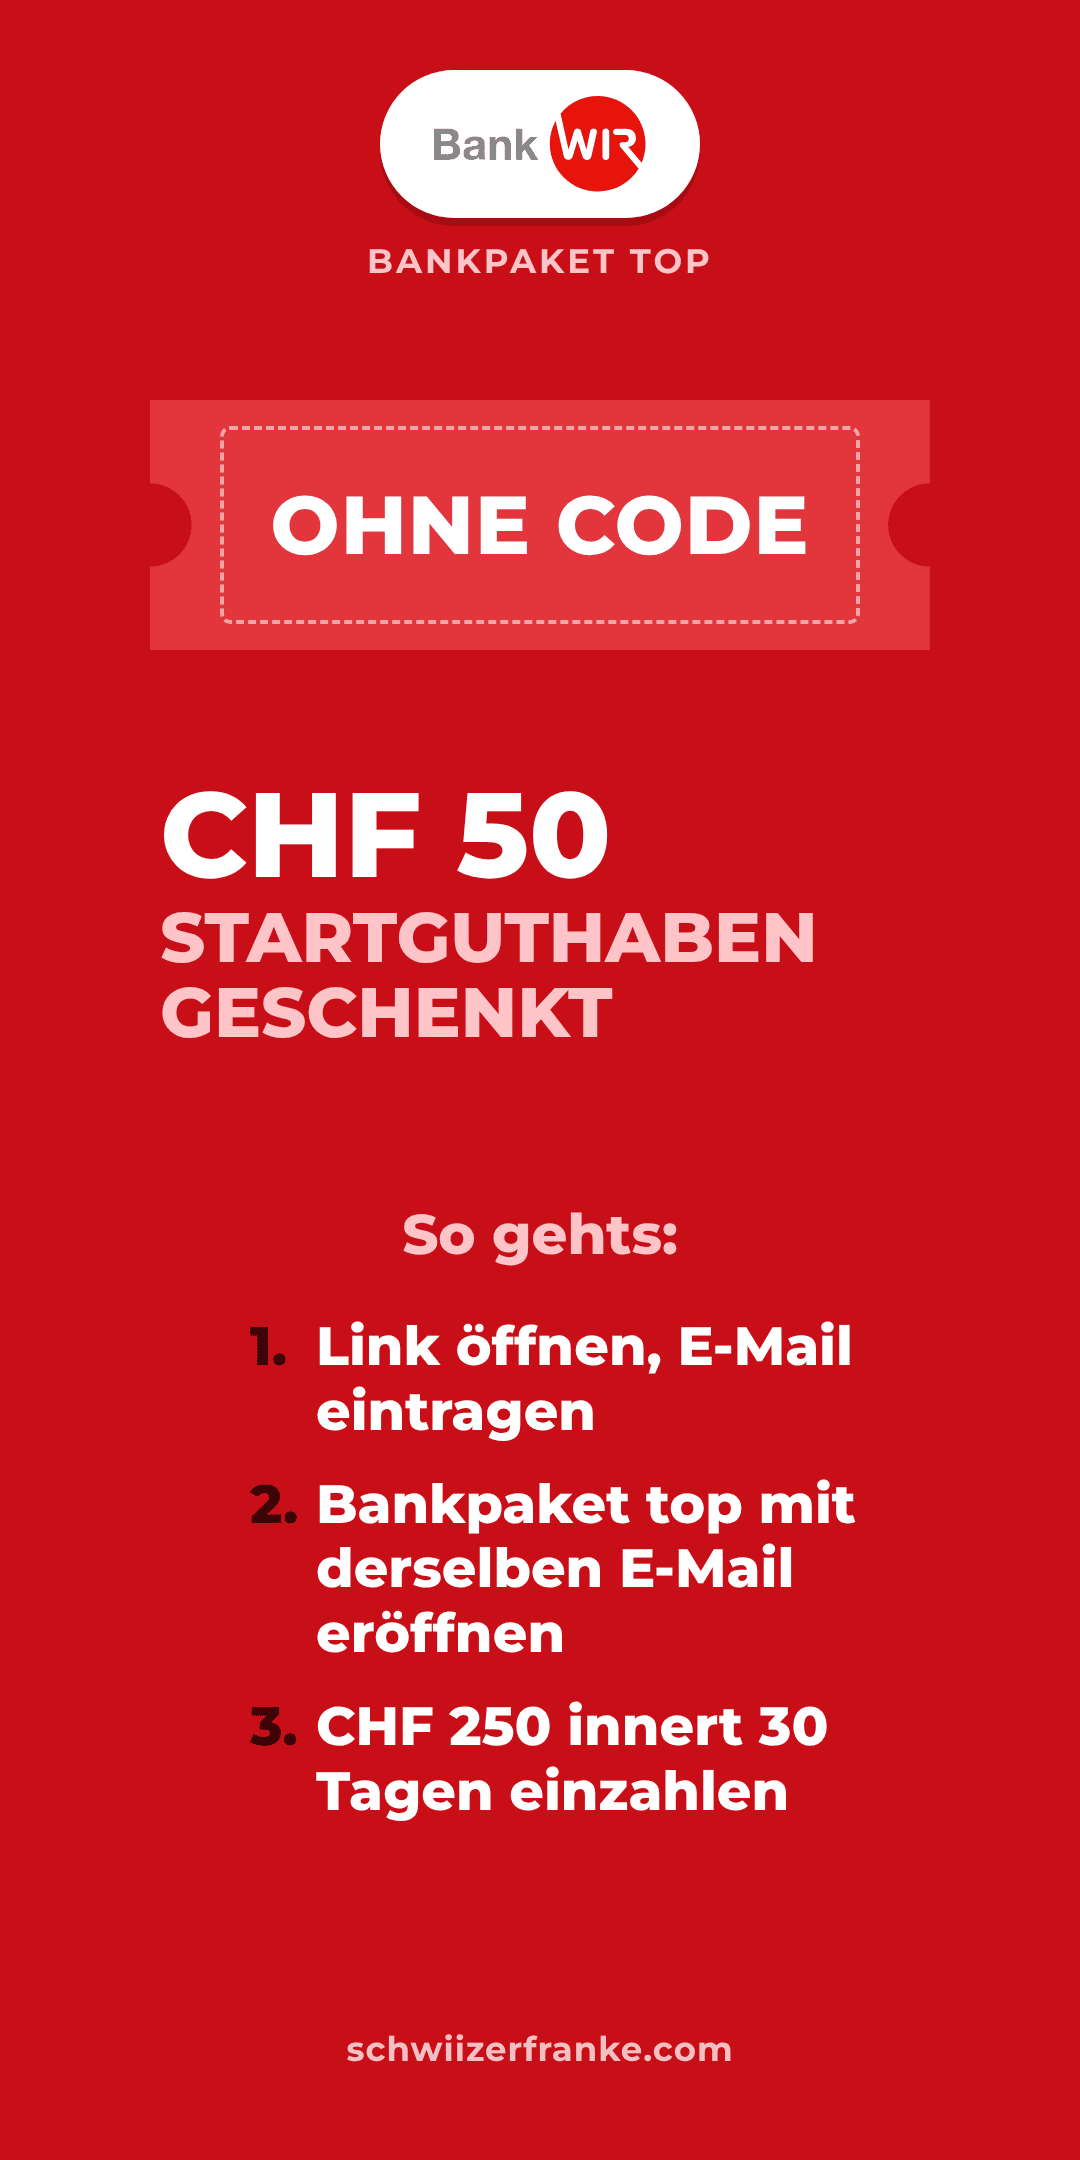
* Affiliate link. CHF 50 starting credit if you deposit at least CHF 250 within 30 days. Schwiizerfranke receives a commission; your terms and conditions remain unchanged.
Joint account and TWINT
You can open the ‘top’ banking package on your own or as a couple. The joint account doesn’t cost anything extra: You’ll receive two Mastercard debit cards and two online banking accounts. The 24 free cash withdrawals apply to both cards combined, not per person.
This makes the Bankpaket top one of the most affordable joint accounts in Switzerland, particularly for couples who travel frequently. The comparison of the top partner accounts. You can read about how to manage your finances as a couple in the Account model for couples.
You can activate TWINT via the WIR Bank TWINT app if you wish. A mobile wallet such as Apple Pay, Google Pay or Samsung Pay also works.
Savings Account Plus: Interest rates and the catch
The Sparkonto plus is a standalone product and is not part of the top banking package. You can open it as an additional account. Until 14 January 2027, there is a 0.50 per cent interest rate on new deposits, guaranteed until 30 September 2027. The interest rate applies to amounts up to CHF 250,000; above that, the rate is 0.025 per cent. There is no minimum deposit.
Here’s how Bank WIR’s savings accounts differ:
| Savings account | Interest | Remuneration | Special feature |
|---|---|---|---|
| Savings account plus | 0.50% up to CHF 250,000, 0.025% above that, guaranteed until 30 September 2027 | up to CHF 20,000 per year without notice; above that, a 2 per cent fee; CHF 2 per transfer to other banks | New funds only; accounts can be opened until 14 January 2027; thereafter, as per the ‘Investment Savings Account’ product page |
| Loyalty savings account | 0.30% in my account | up to CHF 20,000 per year; otherwise, just 0.05 per cent for the whole year | for customers from previous promotions, like me |
| Participation Savings Account | 0.05% base rate, plus a 0.35% bonus on holdings of 25 or more participation certificates | in accordance with the terms and conditions | Bonus available only if you hold participation certificates in your investment account |
Important points to note about the Sparkonto plus: New money is defined as money that has never been held at WIR Bank before. If you transfer funds from another WIR account, the bank may adjust the interest rate.
The most important point isn’t in the advert. According to the product page, the ‘Sparkonto plus’ will automatically become the ‘Beteiligungs-Sparkonto’ after 30 September 2027. According to the terms and conditions, its base rate is 0.05 per cent. A bonus of 0.35 per cent is only available if you hold at least 25 Bank WIR participation certificates in your investment account. These are not the participation certificates included in the ’top’ banking package, but significantly more expensive securities. At the most recent trading price of CHF 483 in November 2026, 25 shares cost around CHF 12,000, plus purchase fees. For a maximum bonus of CHF 350 a year, this is an investment with price risk, not a savings interest rate. So don’t count on the 0.50 per cent remaining.
That’s how it was for me too. My savings account from the previous promotion is now a loyalty savings account. According to my online banking, the current interest rate is 0.30 per cent, provided I do not withdraw more than CHF 20,000 per calendar year. If I withdraw more than that or close the account during the year, I will only receive the standard savings account interest rate for the whole year, which is currently 0.05 per cent. In 2024, my interest rate was still a good 1.2 per cent, and in 2025 it was around 0.7 per cent. So, as an existing customer, I now earn less than new customers with fresh money in the ’Savings Plus’ account. Under current terms, this will change after 30 September 2027: from then on, the Participation Savings Account, with a base rate of 0.05 per cent, will offer a lower rate than the Loyalty Savings Account. Our guide shows you where you can currently get the best interest rates: Savings Account Interest Rate Table.
Share certificate: costs and risks
WIR Bank promotes the share certificate as a simple requirement for the ‘top’ banking package. It really is simple. But it is a stake in the bank, not a gift. Before you pay CHF 200, you should know what you’re getting for it and what you’ll get back.
What you pay: The share certificate costs CHF 200. This comprises a nominal value of CHF 20 and a current premium of CHF 180. The premium is based on the price of the participation certificate; the Board of Directors may adjust it. You submit a written application to join, which the Board of Directors then approves. The share certificate is subsequently held free of charge in your custody account at Bank WIR.
What you get: As a member of the co-operative, you have one vote at the Annual General Meeting, regardless of how many share certificates you hold. In addition, you receive a dividend, the amount of which is decided by the Annual General Meeting each year. For 2025, the General Meeting in June 2026 approved a dividend of CHF 11 per share certificate, which represents 5.5 per cent of the purchase price of CHF 200. The dividend is not guaranteed for future years. As an added bonus, you’ll receive an annual subscription to SuperBenefits worth CHF 39.
What you’ll get back: Here’s the catch. If the bank redeems your share certificate when you leave, it will, in accordance with the articles of association, pay no more than the nominal value, i.e. CHF 20. You will not be refunded the premium of CHF 180 by the bank. You can only resign in writing, giving at least six months’ notice to the end of a calendar year. The Board of Directors may refuse to redeem the share certificate and may defer repayment for up to three years. You may only sell the share certificate to a person whom the Board of Directors accepts as a member of the co-operative. Whether a buyer can be found, and at what price, remains to be seen.
Calculate the share certificate as if the CHF 180 had been paid in. If the ‘Bankpaket Top’ is still worth it for you, then it’s a good deal. Unlike your savings, it isn’t protected by the deposit guarantee scheme, as it constitutes the bank’s equity capital.
Share certificates and participation certificates are often confused. For the ‘Bankpaket top’ package, only the share certificate counts.
| Share certificate | Equity certificate | |
|---|---|---|
| Price | CHF 200: CHF 20 face value plus CHF 180 premium | Market price, last traded at CHF 483 (November 2026) |
| Who buys | only upon submission of an application for membership; the Board of Directors approves | every person; he is being traded |
| Voting rights | one vote at the Annual General Meeting | none |
| Dividend 2025 | CHF 11 in cash, approved in June 2026 | CHF 11, payable either in cash or in participation certificates |
| Back to Money | Redemption by the bank up to a maximum of the nominal value of CHF 20; sale only to a person admitted by the Board of Directors | Sale at the current price, subject to price risk |
| What it counts towards | Condition for the banking package: top | Bonus on the share-based savings account for 25 or more shares |
| Deposit protection | No, the bank’s equity capital | No, the bank’s equity capital |
Online banking, app and customer service
When it comes to fees, WIR Bank beats many neobanks. Not when it comes to ease of use. Since January 2026, the new Digital Banking service has combined the former e-banking and mobile banking into a single solution. For me, it’s a step forward: I used to find e-banking even more cumbersome, but now the overview is better. It’s not perfect, though – as I discovered when I opened my account. In day-to-day use, it’s less intuitive than apps such as neon or Yuh. You need debiX+ for the card, and the TWINT app for TWINT. If you want everything in one app, you’ll have to get used to it. Some details are also hidden: it took me a while to find the current interest rate on my savings account. To save you having to search for ages: open your account, click on the three dots in the top right-hand corner, then select «Account information».
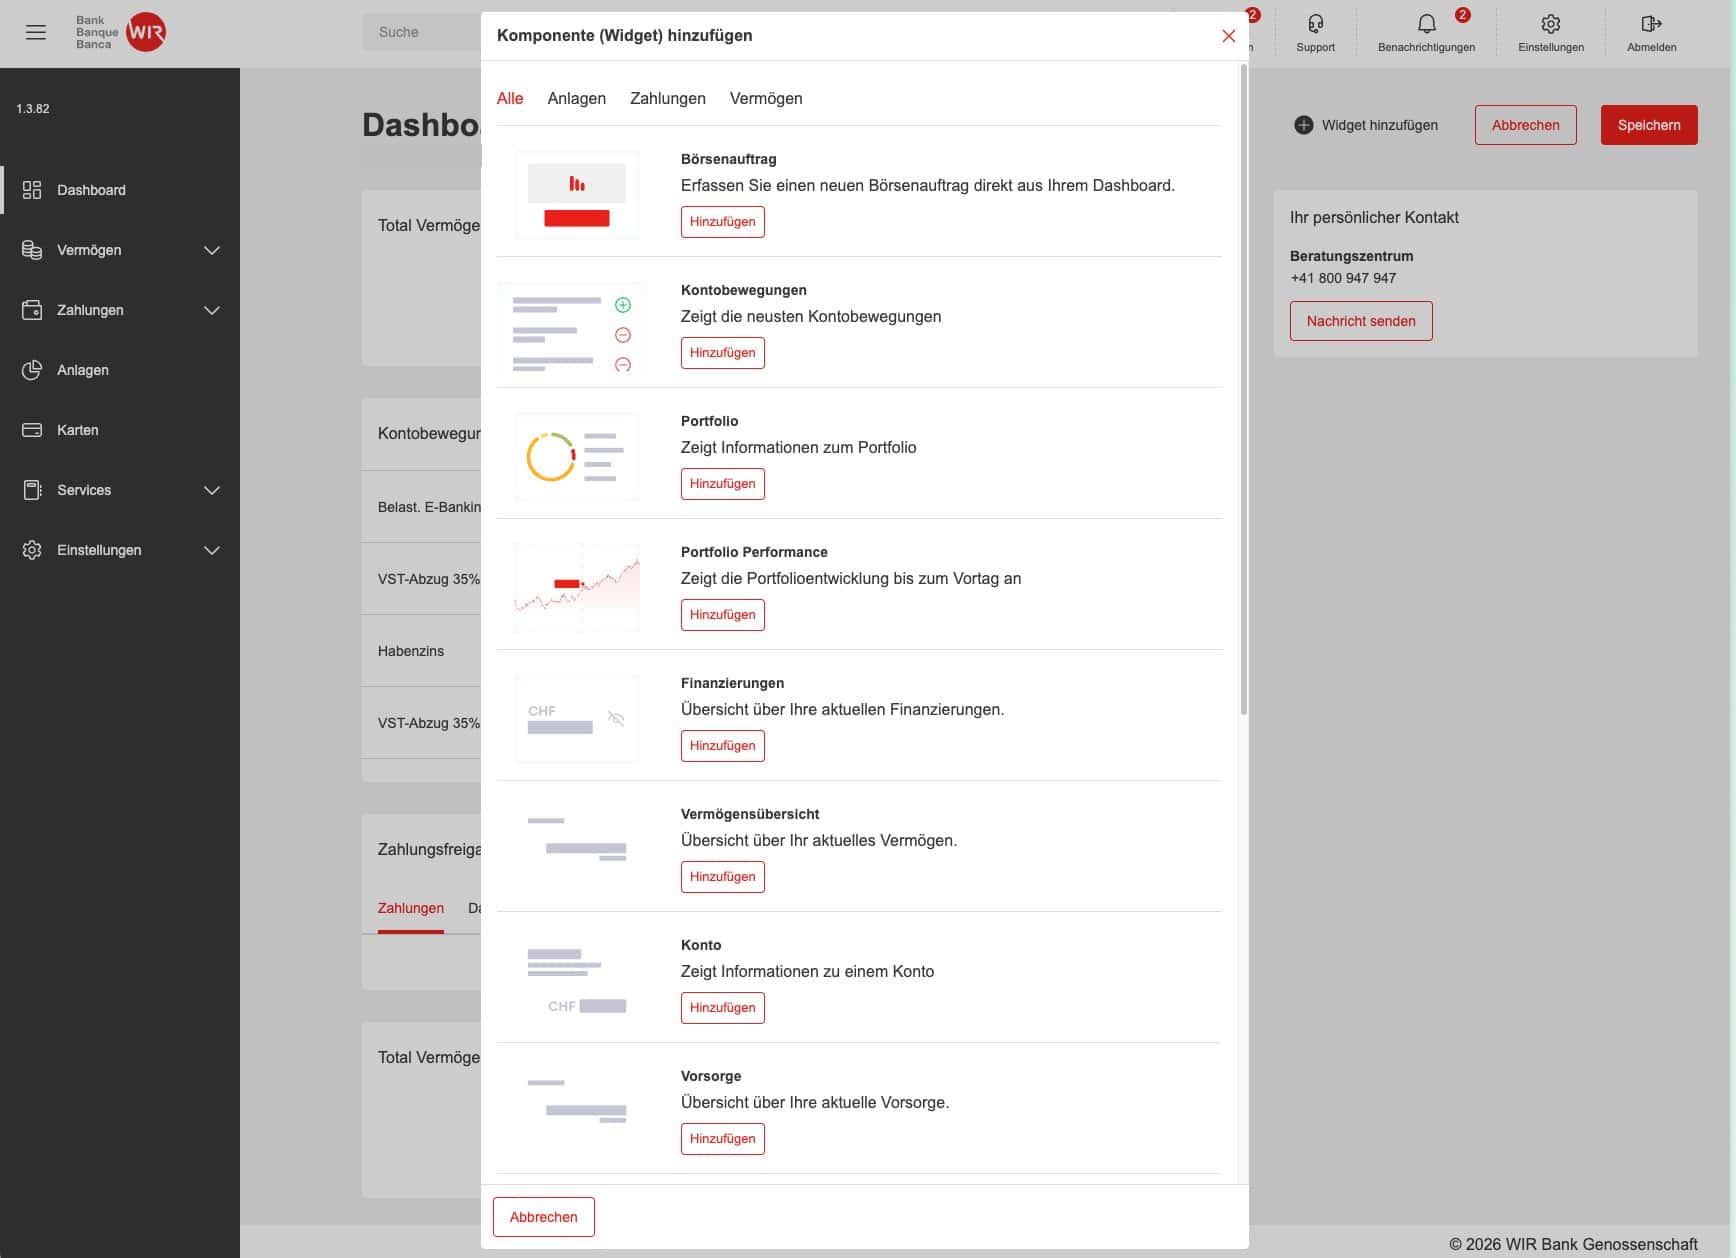
In return, you get what pure app-based banks often lack: a fully-fledged online banking service on your computer, branches and an advice centre on 0800 947 947, Monday to Friday from 8 am to 5 pm. There’s also a chat service and a call-back service.
My experience with customer service has been a mixed bag. On one occasion, I was given the go-ahead over the phone, but later I still received documents in the post that I had to submit. And most recently, my wife and I were locked out of our savings account, even though we use it. It’s been sorted out now, but it took two or three phone calls. For me, it was sorted straight away over the phone. My wife, on the other hand, had to wait for a document to arrive in the post, even though, according to my adviser, it was the same issue.
These are isolated cases, but they paint a clear picture: WIR Bank is a traditional co-operative bank offering fintech terms and conditions, not a fintech company with a banking licence. Some processes are still handled by post and on paper. That doesn’t make it any worse, but you should be aware of this before you open an account.
How to open the 'top' banking package
CHF 50 starting balance for the ‘top’ banking package
If you open the ‘top’ banking package via our partner link and deposit at least CHF 250 within 30 days, WIR Bank will credit your account with CHF 50. You don’t need a code. This also applies if you’re already a customer and are opening the package for the first time.
* Affiliate link: If you open an account via this link, Schwiizerfranke will receive a commission. This will not affect your terms and conditions, and our review remains independent.
As a new customer you can open the ‘top online’ banking package. Via our Affiliate link you’ll receive CHF 50 in starting credit:
- Affiliate link Open it and fill in the form on the promotion page with your email address.
- Open a Bankpaket account online, using your ID card for verification. Use the same email address as on the form.
- Your login details for online banking and your card will be sent by post.
- Deposit at least CHF 250 into your new account within 30 days. You will then receive the CHF 50.
Are you already a customer of Bank WIR, With a savings account, for example, the process is slightly different. This is how I did it myself:
- Check your email address under ‘Contact details’ in online banking. Mine wasn’t listed there.
- On the Promotional page Fill in the form with this exact address and select «I already use e-banking».
- In online banking, go to ‘Services’, then ‘Open a product’, then ‘Pay’ to open the ‘top’ banking package.
- Deposit at least CHF 250 into the new account within 30 days.
That’s how my account opening went. There was no mention anywhere of how long the activation would take:
| Time | What happened |
|---|---|
| 10.07 am | The request was submitted after about two minutes of typing. After that, the only message displayed was that the request had been submitted. |
| 10.24 am | Message in online banking: Account opened. I didn’t receive an email. |
| 11.15 am | The new account is not yet visible in online banking, neither under ‘Accounts’ nor under ‘Cards’. Online banking continued to recommend opening the ‘top’ banking package. |
A pitfall: if you select «I already use e-banking» on the campaign page and enter an email address that isn’t listed in your profile, you’ll be redirected to an error page. So make sure you check the address in your e-banking first. Full details on the starting balance You can find them on our vouchers page.
How secure is WIR Bank?
Bank WIR is a reputable Swiss bank based in Basel. It is listed in the Commercial Register as WIR Bank Genossenschaft. It was founded in 1934 and is regulated by FINMA. It has its origins in the WIR system, a proprietary clearing currency which SMEs still use to make payments amongst themselves to this day. Until 2000, it was purely a commercial bank with its own currency; since then, it has also held accounts in Swiss francs for private individuals. For you as a private customer, WIR money is irrelevant.
How is Bank WIR faring? The key figures for the 2025 financial year provide an indication of the situation at the end of 2025, but offer no guarantee as to the future. As with any Swiss bank, your deposits are protected by esisuisse, across all your accounts with Bank WIR.
| Bank WIR at a glance | |
|---|---|
| Legal form and registered office | Co-operative, Basel |
| Founded | 1934 |
| Supervision | FINMA |
| Total assets in 2025 | CHF 6.74 billion |
| Profit in 2025 | CHF 17.7 million |
| Leverage ratio 2025 | 9.1 per cent (minimum 8 per cent) |
| Deposit protection | esisuisse, up to CHF 100,000 per customer |
A point regarding data protection is included. Section A.1.3 of the General Terms and Conditions dated 1 January 2026 states: «The customer waives, in full, the protection afforded by banking secrecy.» This clause applies to the entire customer relationship. Partial waivers, for example for outsourced services or payments abroad, are included in the terms and conditions of many banks. The wording used by Bank WIR goes further. A separate privacy policy governs how the bank processes personal data. We asked Bank WIR what the clause means in practice. We have included their response here.
Advantages and disadvantages
This speaks in favour of Bank WIR
✓ No parcel charges: The account and Mastercard debit card are free of charge once a certain condition has been met.
✓ Strong abroad: Interbank exchange rate with no surcharge; 24 free cash withdrawals per year worldwide.
✓ Joint account at no extra cost: two cards, two e-banking accounts.
✓ Full-service bank: Online banking, branches, telephone banking, savings accounts, Pillar 3a and mortgages – all under one roof.
✓ Fair terms and conditions for years to come: No hidden fees in my day-to-day life.
This is a point against Bank WIR
✕ Terms and conditions: This package is only available in combination with salary payments, pension contributions, a mortgage or share certificates.
✕ Share certificate: CHF 200, with a maximum refund of CHF 20.
✕ Instructions: Online banking is less user-friendly than with neobanks, and there are separate apps for cards and TWINT.
✕ Customer service: somewhat cumbersome, with queries sent by post.
✕ No interest on the personal account and no credit card in the parcel.
✕ Bank customer confidentiality: Waiver in the Terms and Conditions.
Bank WIR, neon or Yuh?
Bank WIR is on a par with the neobanks when it comes to costs. The difference lies in the business model. neon and Yuh are standalone apps with partner banks operating in the background: You can open an account in minutes; everything is done via a single app, and there are no conditions attached to a free account. WIR Bank is a fully-fledged bank offering online banking via your computer, branches and telephone support.
WIR Bank is a better choice if you’re looking for a main account for your salary and often pay by card abroad. A neobank is a better choice if the app is more important to you than anything else, or if you don’t meet any of the criteria. Our experience with neon and Yuh can be found in the relevant reports. The table below provides an overview of all accounts, including charges and interest: Bank comparison.
Conclusion: Is Bank WIR worth it?
Our conclusions based on our experience with Bank WIR: The 'Bankpaket top' is currently one of the best main accounts in Switzerland if your salary is paid into it. The main reason is the card: when abroad, you pay the interbank exchange rate, with no surcharge. The exception is anyone who is primarily looking for a nice app or who doesn’t meet the eligibility criteria. For them, a neobank is more convenient.
This is for you if …
✓ You’re looking for a free main account for your wages.
✓ You often pay in foreign currency when abroad or online.
✓ You want a joint account with no fees.
It’s not for you if …
✕ You’re just looking for a secondary account with no strings attached.
✕ A modern app is more important to you than your last few francs.
✕ You want to earn interest on your current account.
Your next step: Check whether your salary can be paid into your account. If so, open the ‘top’ banking package via our link and get your CHF 50 starting balance.
* Affiliate link. CHF 50 starting credit if you deposit at least CHF 250 within 30 days. Schwiizerfranke receives a commission; your terms and conditions remain unchanged.
Frequently asked questions about Bank WIR
Is WIR Bank safe?
Yes. Bank WIR is a Swiss cooperative bank based in Basel, founded in 1934 and regulated by FINMA. Your deposits are protected up to CHF 100,000 per customer through esisuisse. In 2025, it posted a profit of CHF 17.7 million on total assets of CHF 6.74 billion.
Is WIR Bank a reputable bank?
Yes. Bank WIR is a well-established Swiss bank with a banking licence, branches and an advisory centre. Please note, however, that in the terms and conditions you waive your right to the protection afforded by banking secrecy.
Is WIR money still around?
Yes. The WIR currency, or CHW for short, is still in use, but only for companies within the WIR network. SMEs use it to make payments amongst themselves, often in combination with Swiss francs. For private customers with the ‘top’ banking package, WIR money is not relevant; you simply use standard Swiss francs.
Is the ‘Top’ banking package really free?
Yes, if you meet one of the following four conditions: monthly deposits of CHF 1,500 or more, pension assets of CHF 20,000 or more held with Bank WIR, a mortgage of CHF 300,000 or more with Bank WIR, or a share certificate. In that case, the account and the Debit Mastercard are free of charge.
What fees does Bank WIR charge?
There are hardly any fees in the ‘Bankpaket top’ package. From the 25th cash withdrawal of the year onwards, each withdrawal costs CHF 2. Payments in other foreign currencies, transfers of Swiss francs abroad or euros outside the SEPA area cost CHF 5 per transaction. Closing the account costs CHF 15.
How much does a share certificate in Bank WIR cost?
CHF 200, comprising a nominal value of CHF 20 and a current premium of CHF 180. If the bank redeems it upon your withdrawal, it will pay no more than the nominal value of CHF 20, in accordance with the Articles of Association. In return, you have one vote at the Annual General Meeting. The General Meeting decides on the dividend each year; for 2025, it was CHF 11.
Can I open the ‘Bankpaket top’ as a joint account?
Yes, at no extra cost. You’ll receive two Mastercard debit cards and two e-banking accounts. The 24 free cash withdrawals apply to both cards combined.
Does the bank offer WIR TWINT and Apple Pay?
Yes. You can activate TWINT via the WIR Bank TWINT app. You can add the debit Mastercard to Apple Pay, Google Pay or Samsung Pay.
How much interest does the ‘Savings Account Plus’ pay?
0.50 per cent on new deposits of up to CHF 250,000, for accounts opened by 14 January 2027, guaranteed until 30 September 2027. According to the product page, it will then automatically convert to a participation savings account with a base rate currently standing at 0.05 per cent.
As an existing customer, will I also receive the CHF 50 starting credit?
Yes, if you open a new ‘Bankpaket top’ account. Fill in the form on the promotional page using the email address registered in your online banking, and then open the account via online banking. You must then deposit at least CHF 250 within 30 days.
How long does it take to open an account with Bank WIR?
The form takes just a few minutes to complete. As an existing customer, it took me two minutes to submit the application via online banking, and 17 minutes later the bank confirmed that the account had been opened. The card will be sent by post.
Is the ‘Bankpaket’ a good choice as a second account?
Only to a limited extent. Without a salary being paid into the account, the share certificate is usually the only condition. It costs CHF 200; if you close the account, the bank will refund a maximum of CHF 20. If you’re looking for a straightforward secondary account with no conditions attached, you’re often better off with a neobank.
* Transparency: If you open an account via our link, Schwiizerfranke receives a commission. You don’t pay anything for this; instead, you benefit from it. Our review remains independent. This is not investment advice.
Sources: WIR Bank, Top Banking Package · Bank WIR, Interest Rates and Terms and Conditions (valid from 21 October 2026) · WIR Bank, Plus Savings Account · WIR Bank, Membership · WIR Bank, Participation Certificates · Articles of Association of the WIR Bank Co-operative · Bank WIR’s Terms and Conditions (1 January 2026) · Bank WIR, 2025 Annual Results · Bank WIR, Annual Report 2025 · Example calculation for exchange rates: based on our own assumption of a 1.5 per cent surcharge. As at 17 November 2026.