To provide you with an optimised experience, we use technologies such as cookies to store and/or access device information. If you consent to these technologies, we may process data such as browsing behaviour or unique IDs on this website. If you do not give or withdraw your consent, certain features and functions may be impaired.
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service expressly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
The technical storage or access is necessary for the legitimate purpose of storing preferences not requested by the subscriber or user.
Technical storage or access for statistical purposes only.
Technical storage or access used solely for anonymous statistical purposes. Without a subpoena, the voluntary consent of your Internet service provider or additional records from third parties, the information stored or accessed for this purpose alone cannot generally be used to identify you.
The technical storage or access is necessary to create user profiles, to send advertising or to track the user on a website or across several websites for similar marketing purposes.




Hello Eric
Thank you for your contribution! My partner and I have each paid the full amount into Pillar 3a so far – with the exception of 2026, as we bought a flat that year.
Due to the renovation work, which we will be carrying out mainly this year and next, we expect to be able to deduct around CHF 40,000 from our taxable income in 2026 and a further CHF 30,000 in 2027.
In principle, we could continue to pay the full 3a contributions by selling ETF units. However, we have so far deliberately chosen not to do so, as we would prefer to make up the shortfall in contributions retrospectively in 2028/2029. We expect the tax deductions to be more beneficial to us then, as our taxable income is likely to be higher again by that time.
Does this line of thinking make sense to you, or are we overlooking something here?
Hi Ben
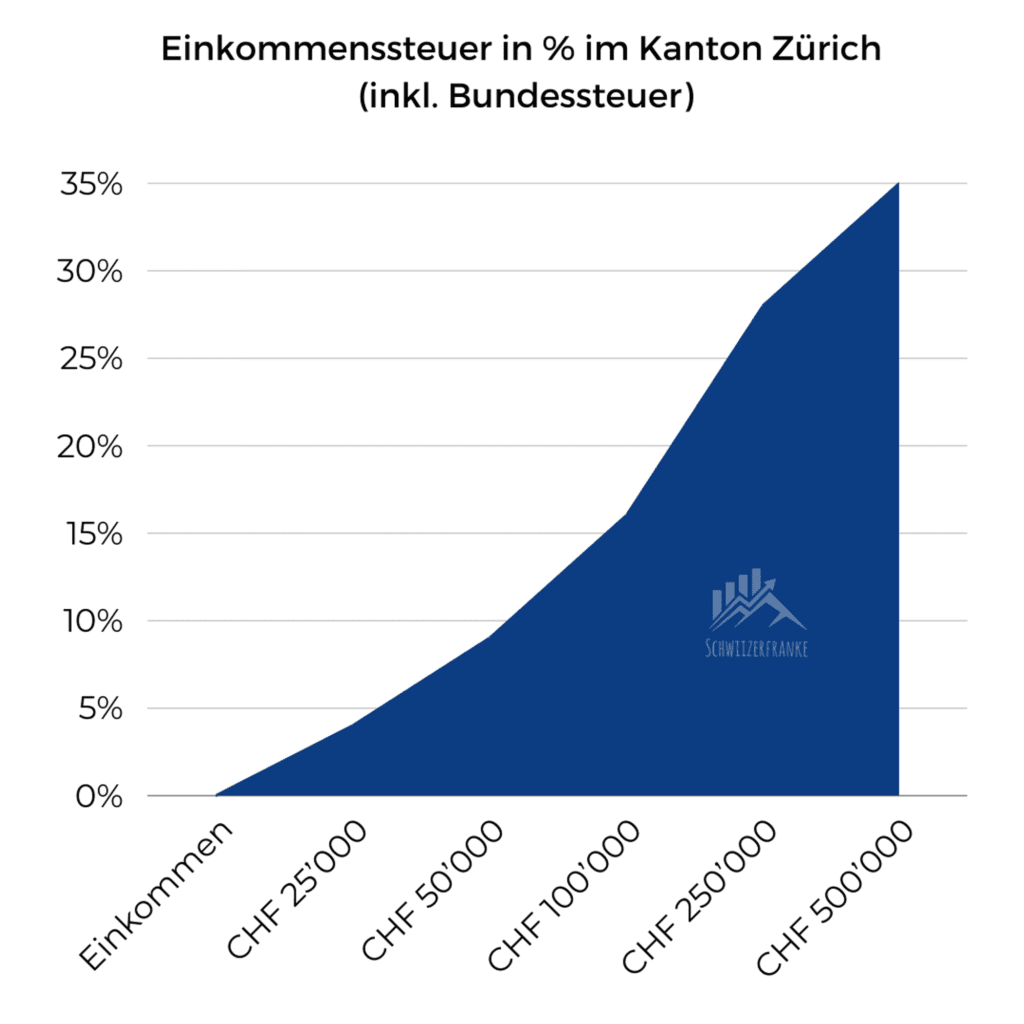
Your point makes sense. The higher your marginal tax rate is in the year of the deduction, the more a tax deduction is worth. If the renovations significantly reduce your taxable income in 2026, a 3a deduction will be worth less that year.
Just bear in mind:
– Not all renovation costs are tax-deductible. Work carried out to maintain the property’s value is deductible, but work that increases its value is not. You should therefore check by how much your taxable income actually decreases.
– In the year in which you make an additional payment, you must first pay in the standard maximum amount. Only then can you make an additional payment. You therefore need sufficient funds to cover both.
– From 1 January 2029, the imputed rental value will be abolished, and with it the deduction for maintenance costs and, to a large extent, for interest on debts. This will affect your tax bill. You should therefore compare the figures for 2028 and 2029 before deciding on a date.
Kind regards
Eric
Hello Eric
In fact, I was able to make a supplementary payment into Pillar 3a for 2025 (the maximum amount). This was after I had previously paid in the maximum amount for 2026.
So far, so good.
But how does this work from a tax perspective?
This is because the local authority has already finalised my tax return for the calendar year 2025. I ended up paying quite a bit more tax for 2025 because I didn’t have the Pillar 3a deduction.
Will the double deduction now be granted for the forthcoming tax return covering the calendar year 2026?
Or will the tax authorities make some sort of reversal entry for the 2025 tax year?
Do you know any more about this?
Carmen
Hi Carmen
There is no carry-back to 2025. You can claim the additional payment as a deduction in the year in which you make it. Your 2025 tax assessment therefore remains as it is.
In your 2026 tax return, you’ll claim both amounts: the standard maximum amount for 2026 and the back payment for 2025. Your provider will show the back payment separately on your tax certificate.
How much you save as a result depends on your income in 2026. This recoups some of the savings you missed out on in 2025; depending on your marginal tax rate, the amount may be more or less.
Kind regards
Eric
Hi Eric
Am I right in understanding that additional payments can only be paid into one account as a one-off deposit, and cannot be split between your 5–6 3a accounts?
Hi Michel
Almost. The rule is: only one contribution is permitted per gap year. In practice, providers do not allow contributions to be split across multiple accounts. You apply to your provider to make the contribution to a specific account.
More importantly, however, there is a pitfall that many people overlook. Here’s an example: in 2025, you have a shortfall of CHF 4,000, but can only afford to pay CHF 3,000. If you top up the CHF 3,000, the remaining CHF 1,000 is lost forever. A second top-up for 2025 is no longer permitted, even though the 10-year period would still be running.
That’s why it’s better to wait until you can fill the entire gap in one go. Incidentally, with a single contribution, you can also fill several gap years at once, though up to a maximum of the small 3a limit per year.
You can continue to spread your regular deposits across all your accounts.
Kind regards
Eric
Hello Eric
Thank you very much for your informative article. Do you know what the situation is if I have already made a Pillar 3A withdrawal at a young age to finance an owner-occupied property? Am I right in assuming that this counts as a withdrawal and that I have therefore missed the opportunity to make retroactive purchases into pillar 3A?
Thank you very much for answering my question and best regards,
Pascal
Hello, Pascal,
Correct, unfortunately it was implemented in such a way that gaps that arise from 2025 onwards can only be closed.
After all, you were already using pillar 3a at the time, so you simply withdrew the money beforehand.
It is particularly unfortunate for people who have not used the 3a in the past or have not been able to use it.
But at least that will change in the future.
Dear greetings
Eric
Hello Eric
So I can only pay retroactively from 2026? -> In other words, in 2036 for the year 2026, but not in 2026 for the year 2016/2017/2018, etc... ?
So if I always pay in the full amount now, but was unable to do so in the years 2016-2022, will nothing change for me at the moment?
Hello N,
Correct, that is the current political status. However, we will certainly receive more information by 2026 - the article will then of course be updated.
Hello Eric
Thank you for your easy-to-understand article and for publicising this important approach!
However, when I did some research on the internet, I came across an article in NZZ that states that past contribution gaps are excluded and only future gaps can be closed. As the proposal only comes into force from 2026, your example of repayment in 2025 is not correct, or am I misunderstanding something?
As you write it, I can go back 10 years, i.e. gaps up to 2016 can be closed? Can you please briefly specify this? I myself, and I'm sure many others, may have had the spontaneous thought (which would be cool, of course, if it is possible) of not paying in the maximum amount for 2024 "because I had less income in that year due to unpaid leave", but I can optimise my taxes accordingly in 2026....
Hello Marcel
thanks for asking, I have now formulated the article a little more clearly - it is (unfortunately) really only about gaps, which to introduction. Here is the sentence from the official notification from the Federal Council: "Contribution gaps that arise after the new provisions come into force should be able to be closed at a later date with purchases."
i.e. from 2026, CHF 14,112 is the new maximum amount?
No, but with the current annual amount it is no more than two annual contributions. For example, with CHF 7,056 as the basis x2 = CHF 14,112
I think this is very good for solo self-employed people, because although they can pay in up to 20% in the current tax year, they can only calculate this 20% precisely after the annual accounts - i.e. in the following year. As a self-employed person, you therefore either pay too little or too much in the current year. With the new regulation, unused amounts of 3A can also be paid later.
It's a shame that the whole thing only applies from 2026. I still have one or two gaps from previous years that I would like to have filled for my old age.
Hello Lars,
Absolutely, it's really brilliant for the self-employed - especially because turnover is often not as constant as a fixed salary.
However, I think the restriction on AHV years is a pity. Unfortunately, this makes it impossible for anyone moving to Switzerland to make up for missing contribution years and provide for their - rather expensive - pension in Switzerland.